










Purohit Construction Limited Sets Q2 FY27 Results Review
Key highlights
- Purohit Construction will consider Q2 and H1 FY27 unaudited results at a board meeting on November 6, 2026.
- Purohit Construction reported a ₹78.75 lakh net loss in Q1 FY27, compared with a ₹9.98 lakh loss a year earlier.
- A ₹69.45 lakh GST-related provision was the main stated reason for the Q1 FY27 loss increase.
- FY26 total income rose 58.33% to ₹19 lakh, while the annual net loss widened to ₹34.40 lakh.
powered by IRIS
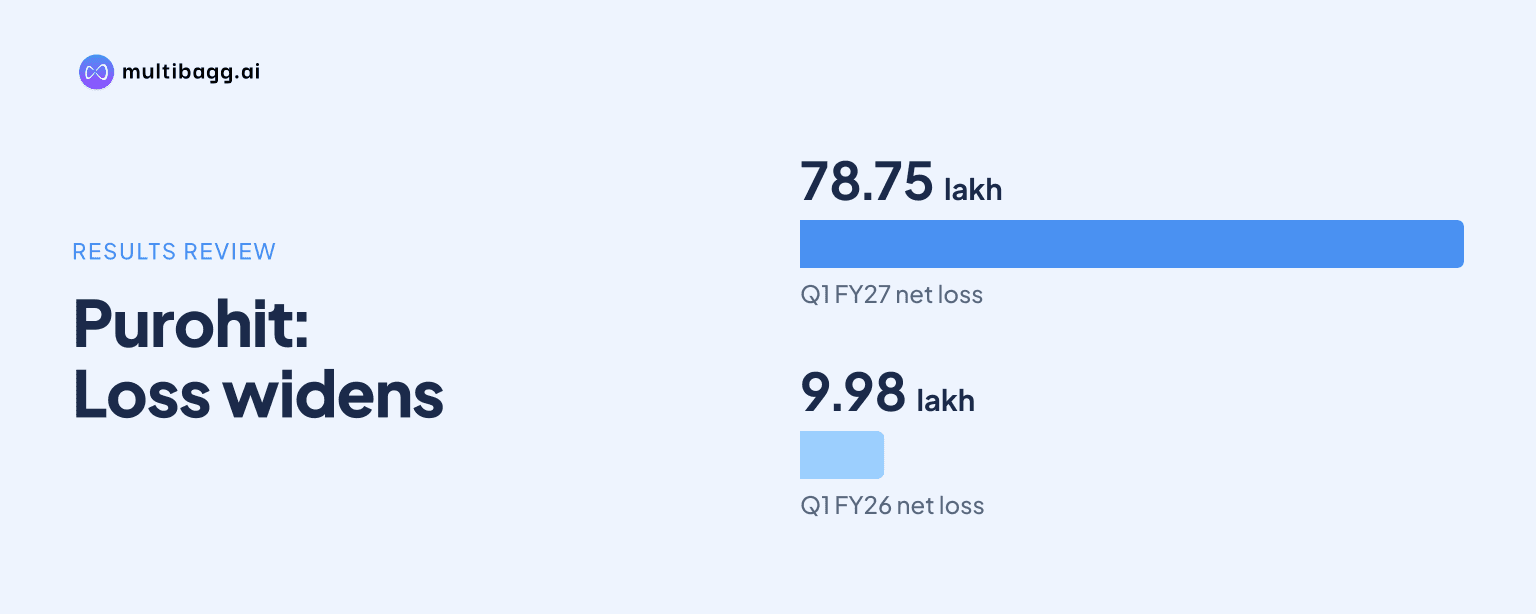
Purohit Construction Limited has scheduled a board meeting on November 6, 2026, to approve unaudited Q2 and first-half FY27 results, following a ₹78.75 lakh net loss in Q1 FY27 that included a ₹69.45 lakh GST-related provision. The filing matters because the company reported no revenue from operations in the June quarter.
Know Purohit Construction inside out
Results, valuation, peers and who's buying, in one view.
When will Purohit Construction announce Q2 FY27 results?
Purohit Construction will hold its board meeting on Friday, November 6, 2026, to consider and approve standalone unaudited financial results for the quarter ended September 30, 2026. The company’s intimation identifies the second quarter and half year ended September 30 as the agenda for the meeting.
The available disclosure is a board-meeting intimation, not the Q2 FY27 financial result itself. It therefore does not provide September-quarter revenue, profit or loss, balance-sheet figures, or a management commentary. Investors will need to rely on the financial statements released after board approval for those details.
The company had previously communicated that its trading window would close from October 1, 2026. It will remain closed until 48 hours after declaration of the unaudited results for the quarter and half year ended September 30, 2026. Such a closure is a standard restriction intended to prevent trading by designated persons while unpublished price-sensitive information is pending.
What did Purohit Construction report in Q1 FY27?
Purohit Construction reported a standalone net loss of ₹78.75 lakh in Q1 FY27, compared with a ₹9.98 lakh loss in Q1 FY26. Revenue from operations was nil in both periods, according to the June-quarter result cited in the available information.
The sharp increase in the loss was attributed primarily to a ₹69.45 lakh provision related to a Goods and Services Tax demand after an appeal rejection. Operating expenses were ₹78.62 lakh against negligible income. The board approved the June-quarter standalone unaudited results on August 14, 2026, and the results were subsequently published in newspapers on August 15.
The June-quarter figures indicate that the GST provision was the main driver of the period’s reported loss. Without a reported operating revenue stream, exceptional or statutory charges can have a substantial effect on the company’s quarterly profit and loss statement.
How did Purohit Construction perform in FY26?
Purohit Construction reported total income of ₹19 lakh for FY26, up 58.33% from ₹12 lakh in FY25. Despite the increase in income, the company’s loss widened during the year, underscoring the gap between its reported income base and expenses.
Profit before tax was a loss of ₹33.86 lakh in FY26, compared with a loss of ₹26.61 lakh in FY25. Profit after tax was a loss of ₹34.40 lakh, wider than the ₹25.21 lakh loss reported for the preceding year. Earnings per share stood at negative ₹0.78 in FY26, against negative ₹0.57 in FY25.
For the March 2026 quarter, the company reported a net loss of ₹10 lakh, compared with a ₹2 lakh profit in the March 2025 quarter. No sales were reported in the March 2026 quarter, versus ₹12 lakh in the corresponding quarter a year earlier. These figures provide context for the absence of operating revenue reported in the subsequent June 2026 quarter.
Got a follow-up? Ask IRIS
Why does the November 6 board meeting matter to investors?
The November 6 meeting matters because it will provide the first reported financial update after the June-quarter GST provision and the second quarter without currently disclosed figures. The Q2 filing should show whether Purohit Construction generated revenue from operations during the September quarter and how its loss position changed after Q1.
The half-year result will also combine the June and September quarters, making it relevant for assessing the company’s FY27 financial position to date. In particular, investors can examine the treatment of the GST matter, other expenses, liabilities and equity after the June-quarter loss.
The available June-quarter information stated that equity stood at ₹62.15 lakh while non-current liabilities were ₹77.31 lakh. Those balance-sheet figures, alongside nil revenue, place emphasis on the upcoming result’s disclosures on financial position and operating activity. The current information does not establish whether these measures improved or deteriorated in Q2.
What should investors look for in the Q2 FY27 filing?
Investors should look first for revenue from operations, net profit or loss, and any explanation of unusual expenses in the September-quarter results. Since the company reported nil operating revenue in Q1 FY27, a disclosed change in revenue would be material to understanding its current activity level.
The filing may also clarify whether any additional cost connected to the GST demand was recognised after the ₹69.45 lakh provision recorded in Q1. The available information confirms the earlier appeal rejection and provision but does not disclose any subsequent resolution, payment, reversal or fresh charge.
Investors can also compare the updated equity and liability position with the June-quarter figures. The board-meeting notice confirms the timing and scope of the review, but it does not contain guidance, projections, order-book data, project milestones, or any outlook for the remainder of FY27.
Conclusion
Purohit Construction’s November 6 board meeting is the scheduled point for release of Q2 and first-half FY27 numbers. The forthcoming filing follows a June quarter marked by nil operating revenue and a ₹78.75 lakh loss, largely affected by a ₹69.45 lakh GST provision, while FY26 ended with a ₹34.40 lakh loss despite a 58.33% increase in total income.
The next item to watch is the company’s unaudited results for the quarter and half year ended September 30, 2026, once approved by the board. Key disclosures will include September-quarter revenue, the reported loss or profit, treatment of the GST matter, and any updated information on equity and liabilities.