










Radico lifts FY27 premium growth target after 36% Q2 surge
Key highlights
- Radico raised its FY27 Prestige & Above volume-growth target to 30% after Q2 FY27 growth of 36%.
- Prestige & Above volume reached a record 5.28 million cases in Q2 FY27.
- Radico reported Q2 FY27 revenue of Rs 1,746 crore, EBITDA of Rs 356 crore and a 20.4% EBITDA margin.
- Packaging-material volatility had an approximately Rs 27 crore impact in Q2 FY27.
powered by IRIS
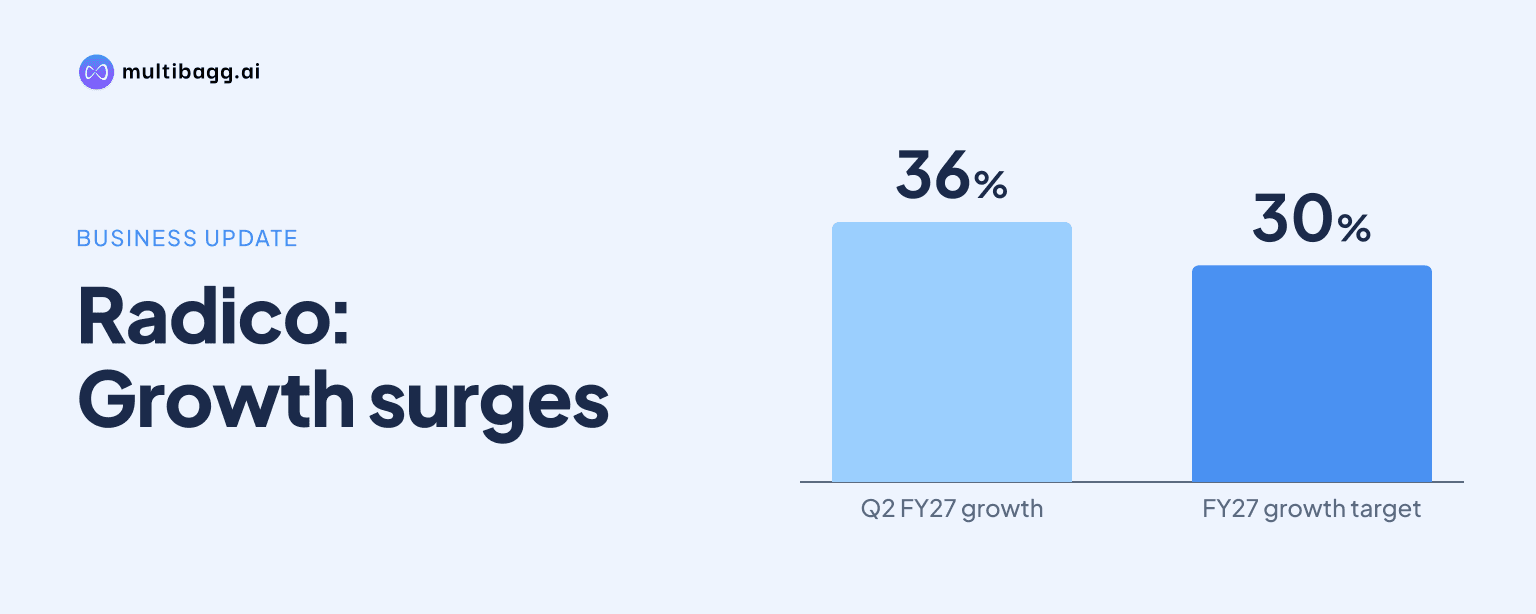
Radico Khaitan Limited raised its FY27 Prestige & Above volume-growth target to 30% after the portfolio grew 36% to a record 5.28 million cases in Q2 FY27. Radico retained its around-20% EBITDA, or earnings before interest, tax, depreciation and amortisation, margin outlook after reporting Rs 356 crore of quarterly EBITDA.
Know Radico Khaitan inside out
Results, valuation, peers and who's buying, in one view.
Why did Radico raise its FY27 Prestige & Above target?
Radico raised its FY27 Prestige & Above volume-growth target to 30% because the portfolio grew 36% in Q2 FY27 and reached its highest-ever quarterly volume of 5.28 million cases. Management said premiumization remained central to performance and was improving the company’s sales mix through the first two quarters of FY27.
The target revision followed what management called Radico’s strongest quarter in its history, with record volume, revenue and profitability. Total Indian-made foreign liquor, or IMFL, volume exceeded 10 million cases, up 7% year on year, while Q2 FY27 revenue was Rs 1,746 crore and EBITDA was Rs 356 crore. The 30% target applies to Prestige & Above volumes rather than total IMFL volumes.
Prestige & Above expanded substantially faster than the overall portfolio in Q2 FY27. Its 36% volume growth was 29 percentage points above total IMFL volume growth of 7%, reflecting a change in the quarterly sales mix. Management attributed the result to brand momentum and premiumization-led mix improvement rather than identifying a single label as the principal driver.
What supported Radico’s premium-volume growth in Q2 FY27?
Radico said brand momentum across vodka, whisky and luxury products supported premium-volume growth in Q2 FY27. In vodka, the company launched Magic Moments Aam Panna in August through a digital-first campaign, while management described consumer response as encouraging and said tertiary offtake across the Magic Moments family remained healthy.
Vodka’s share of IMFL reached 6.3% in Q2 FY27, compared with 4.5% in 2026 and 3.7% in 2025, according to management. Radico linked that shift to flavoured vodka and changing consumption among younger consumers and women. Management said Magic Moments was participating in this category expansion, which supports its broader premiumization plan.
In whisky, Radico said After Dark’s new packaging was resonating in the market’s largest segment and was being extended to more states. It also cited momentum and market-share gains for 8PM Premium Black, while Royal Ranthambore continued to perform in civil and Canteen Stores Department channels. The company did not disclose brand-level case volumes or growth rates for these labels in Q2 FY27.
Radico also cited Rampur Indian Single Malt, Jaisalmer Indian Craft Gin and Virasat Indian Single Malt as luxury brands receiving a positive response in India and abroad. Its Q2 FY27 activity included on-trade advocacy sessions, curated consumer experiences, key-account partnerships and shop-in-shop formats. Internationally, Radico entered four major United Kingdom airports and said it was present in around 70 duty-free locations, against an objective of 100 outlets.
Got a follow-up? Ask IRIS
Can Radico sustain its 20% EBITDA-margin outlook?
Radico said it remains confident of sustaining an EBITDA margin of around 20% in FY27 despite volatility in grain and packaging-material costs. Its Q2 FY27 EBITDA margin was 20.4%, an expansion of 462 basis points year on year. One basis point equals one-hundredth of a percentage point.
Gross margin was 48.0% in Q2 FY27, up 440 basis points year on year but down 109 basis points quarter on quarter. Management said product mix and premiumization added 510 basis points to gross margin, while price increases added 85 basis points. Those gains were partly offset by packaging-material volatility, which had an approximately Rs 27 crore financial impact during the quarter.
Management said the sequential gross-margin decline reflected cyclical brand-mix change and grain-price inflation. Its disclosed measures to manage costs include sharper procurement, value engineering, integrated manufacturing and a richer product mix. Radico had also built higher raw-material inventories, which management said supported Q2 FY27 amid rising grain prices.
What could affect Radico’s FY27 premium and margin plan?
The principal disclosed risk to Radico’s FY27 margin plan is continued volatility in grain, packaging and other input costs. Packaging costs alone created the approximately Rs 27 crore impact in Q2 FY27, equivalent to about 155 to 160 basis points at the gross-margin level. Management nevertheless retained its around-20% EBITDA-margin guidance for the full year.
Radico made a deliberate working-capital investment in Q2 FY27 to support premium-portfolio growth, new launches and purchases of raw and packaging materials. Management called this a temporary build and said it expects working capital to normalize in the second half of FY27. It also said both return on equity and return on capital employed improved during the quarter, without disclosing the ratios.
Regular-volume decline was a contrasting factor in Q2 FY27, when total IMFL volume still grew 7% year on year. Management attributed the regular decline to a higher Q2 FY26 base after a route-to-market change in Andhra Pradesh, as well as policy changes in Maharashtra and Karnataka. The revised 30% Prestige & Above target therefore depends on premium growth continuing alongside the company’s procurement and mix-management actions.
Conclusion
Radico’s revised 30% FY27 Prestige & Above growth target follows a Q2 FY27 result in which premium volumes rose 36% to 5.28 million cases, compared with 7% growth in total IMFL volume. That mix shift coincided with Rs 356 crore of EBITDA and a 20.4% EBITDA margin, despite an approximately Rs 27 crore packaging-cost impact.
The next disclosures to watch are whether Prestige & Above growth remains close to the Q2 FY27 rate and whether working capital normalizes in the second half of FY27 as management expects. Management also plans to pursue its objective of reaching 100 travel-retail outlets from around 70 locations, while relying on procurement, value engineering and product mix to maintain its around-20% EBITDA-margin outlook.