










Radico Khaitan retains 20% FY27 margin after Q2 cost hit
Key highlights
- Radico Khaitan reported a 20.4% EBITDA margin in Q2 FY27, up 462 bps year on year.
- Radico Khaitan’s Q2 FY27 gross margin was 48.0%, up 440 bps year on year but down 109 bps sequentially.
- Packaging-material volatility created an approximately Rs 27 crore Q2 FY27 impact, equal to about 155-160 bps of gross margin.
- Prestige & Above volume rose 36% to 5.28 million cases in Q2 FY27, and Radico Khaitan raised its FY27 growth target to 30%.
powered by IRIS
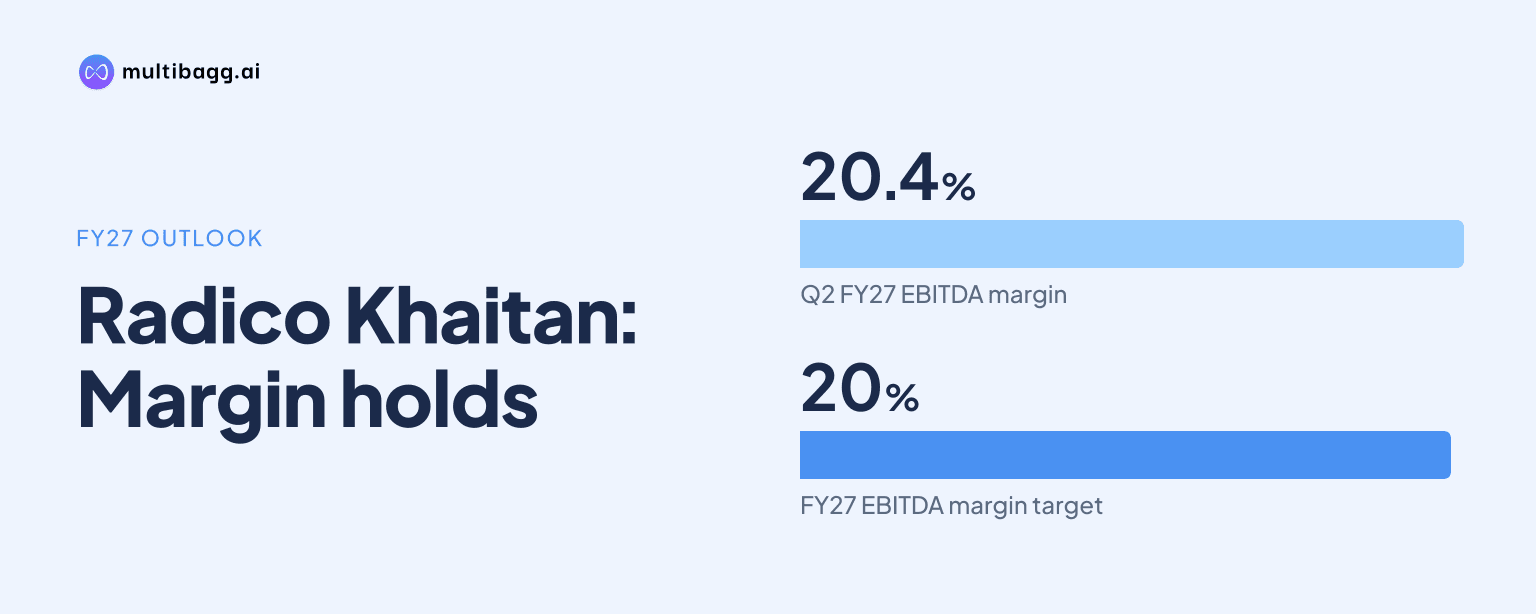
Radico Khaitan Limited retained its around-20% FY27 EBITDA, or earnings before interest, taxes, depreciation and amortisation, margin guidance after a Rs 27 crore packaging-cost impact in Q2 FY27. Radico Khaitan reported a 20.4% Q2 EBITDA margin and 48.0% gross margin, while management expects grain prices to stabilise from November.
Know Radico Khaitan inside out
Results, valuation, peers and who's buying, in one view.
How large was Radico Khaitan’s Q2 FY27 packaging-cost hit?
Radico Khaitan said recent volatility in packaging-material prices created an approximately Rs 27 crore financial impact in Q2 FY27. In the earnings-call question-and-answer session, management quantified that effect at roughly 155 to 160 basis points, or bps, of gross margin. The company nevertheless reported quarterly revenue of Rs 1,746 crore and EBITDA of Rs 356 crore.
The cost pressure came as the wider input environment became more volatile in Q2 FY27. Management specifically linked the packaging disruption to the West Asia war, citing higher prices for glass bottles, polyethylene terephthalate, or PET, resin and certain laminates. It described the situation as unpredictable rather than providing a precise end-date or a cost forecast for those materials.
Radico Khaitan described Q2 FY27 as its strongest quarter in history for volume, revenue and profitability, with Indian-made foreign liquor, or IMFL, volume exceeding 10 million cases. That scale did not prevent the cost effect, but the reported 20.4% EBITDA margin remained above management’s around-20% full-year expectation.
Why did Radico Khaitan’s gross margin change across periods?
Radico Khaitan’s gross margin increased 440 bps year on year to 48.0% in Q2 FY27, but fell 109 bps sequentially. Management attributed the year-on-year expansion chiefly to premiumisation: product mix and premiumisation added 510 bps, while price increases added another 85 bps. The Rs 27 crore packaging-material effect offset part of those gains.
The quarter-on-quarter compression had different drivers. Management cited a cyclical brand-mix change and inflation in grain prices, rather than saying that packaging alone caused the 109-bps decline. This distinction matters because Q2 IMFL volume exceeded 10 million cases, up 7% year on year, while the higher-margin Prestige & Above portfolio reached 5.28 million cases.
The Prestige & Above portfolio’s volume rose 36% in Q2 FY27, compared with 7% growth in total IMFL volume. Management said this mix improvement helped profitability despite grain and packaging pressure. Regular-category volume declined because Q2 FY26 had a higher base following a route-to-market change in Andhra Pradesh, alongside policy changes in Maharashtra and Karnataka.
The 510-bps contribution from mix and premiumisation was larger than the 85-bps contribution from price increases in the year-on-year gross-margin bridge. Radico Khaitan did not disclose the proportion of its portfolio with pricing freedom or the typical lag between input-cost increases and price changes when an analyst asked about those issues.
Got a follow-up? Ask IRIS
How is Radico Khaitan managing grain and packaging volatility?
Radico Khaitan said it had built higher grain stocks to mitigate much of the effect of rising grain prices, and that inventory supported Q2 FY27 performance. The company did not disclose the quantity, purchase cost or expected duration of those stocks. It also made what management called a deliberate temporary working-capital investment for premium growth, new launches and key raw-material and packaging procurement.
Management expects that temporary working-capital build to normalise during the second half of FY27. Its mitigation approach also includes sharper procurement, value engineering, integrated manufacturing and a richer product mix. These are the operational measures management identified while maintaining its around-20% full-year EBITDA-margin expectation.
For grain, management expects conditions to become more benign from November, when the new crop season starts. It also pointed to Food Corporation of India, or FCI, allocation of 72 lakh metric tonnes under the year’s ethanol policy as a factor that should stabilise the market. This is management’s outlook, not a disclosed grain-price target.
Packaging costs remain less predictable than the grain outlook, according to management’s comments on Q2 FY27. Glass bottles, PET resin and laminate prices were the materials specifically identified, while the company’s stated response was to combine procurement and manufacturing actions with a premium product mix rather than cite a separate packaging-cost target.
Why does Radico Khaitan retain its FY27 EBITDA-margin guidance?
Radico Khaitan retains its guidance because management believes premiumisation, operating efficiencies and cost discipline can offset volatile inputs, as reflected in the 20.4% Q2 FY27 EBITDA margin. The company explicitly reaffirmed an EBITDA margin of around 20% for FY27 despite the Rs 27 crore Q2 impact. It also upgraded its Prestige & Above volume-growth expectation to 30% for the full year.
The underlying portfolio performance was the main evidence management offered. Prestige & Above grew 36% in Q2 FY27 to a record 5.28 million cases, and management said the category continued to enrich the sales mix. In vodka, Radico Khaitan said the category’s share of IMFL reached 6.3% in Q2, compared with 4.5% in 2026 and 3.7% in 2025.
Management also cited state-level momentum. It said premium volumes in Karnataka grew by more than 100% during the quarter after duty reduction and freer pricing, although Karnataka represented 6% of Radico Khaitan’s saliency. Maharashtra Prestige & Above returned to growth in Q2, according to management, aided by vodka’s share reaching about 10% of the state’s industry.
Radico Khaitan also said it grew non-vodka Prestige & Above volume by 20% in Q2 FY27 and vodka volume by about 49%. Management compared that performance with industry Prestige & Above growth of about 5.8% to 6%, while maintaining that the portfolio, rather than a single state, supported the upgraded 30% FY27 Prestige & Above target.
Conclusion
Radico Khaitan’s Q2 FY27 results indicate that mix-led profitability absorbed a Rs 27 crore packaging-cost impact without changing management’s around-20% EBITDA-margin objective. Gross margin reached 48.0%, up 440 bps year on year but down 109 bps sequentially, showing that premiumisation offset part of input inflation while grain prices and brand mix affected the quarter.
The next disclosed factors to watch are whether the new crop season from November and the 72 lakh metric-tonne FCI ethanol allocation stabilise grain costs as management expects. Radico Khaitan also expects its temporary working-capital build to normalise in the second half of FY27 and has set a 30% FY27 Prestige & Above volume-growth target.