










Rossell Techsys targets 18%-23% EBITDA margin as scale builds
Key highlights
- Rossell Techsys reported Q2 FY 2027 revenue of Rs 185.56 crore, up 47% year on year.
- Rossell Techsys reported Q2 FY 2027 EBITDA of Rs 29 crore and PBT of Rs 12.91 crore.
- Management reaffirmed Rossell Techsys’s target of becoming an 18%-23% EBITDA-margin company.
- Inventory carrying levels fell to 6.67 months in Q2 FY 2027 from 7.98 months a year earlier.
powered by IRIS
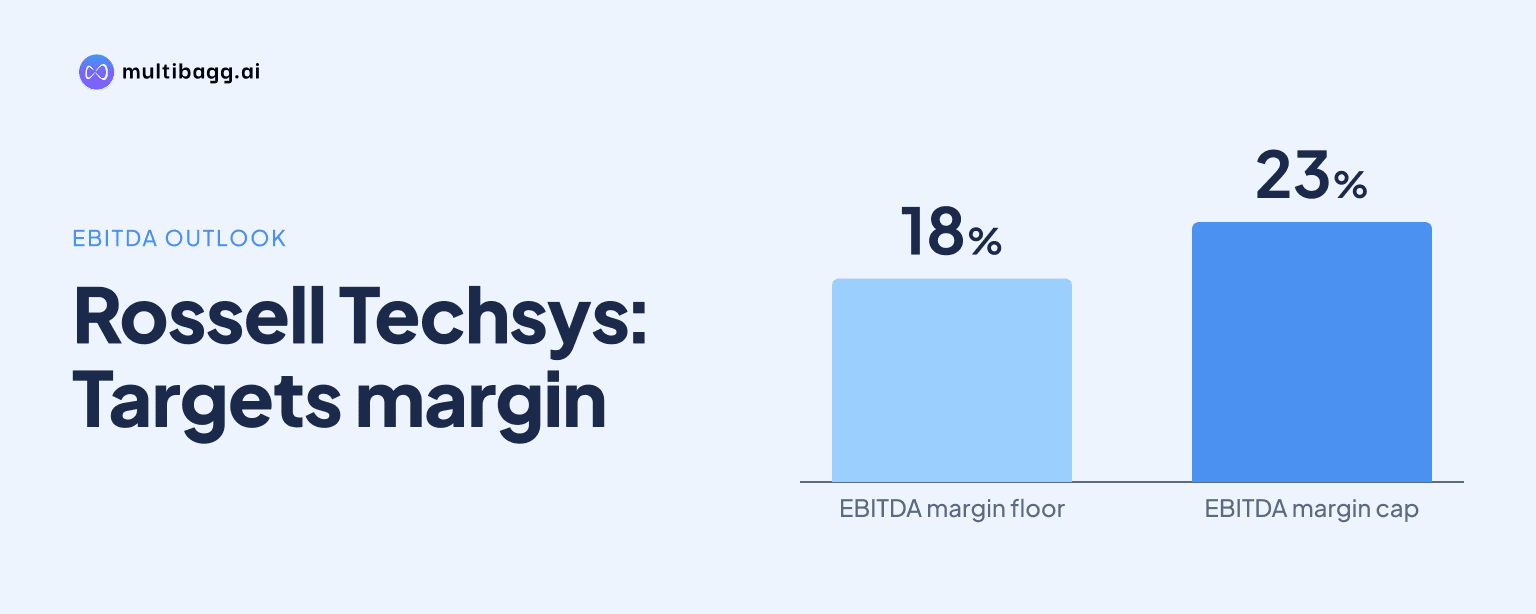
Rossell Techsys Limited reaffirmed its target of becoming an 18%-23% EBITDA-margin company after reporting Q2 FY 2027 EBITDA of Rs 29 crore on record revenue of Rs 185.56 crore. Management said increasing scale, operating leverage and repayment of working-capital limits from its Rs 300 crore raise should improve profitability, with finance-cost savings expected from Q3 FY 2027.
Know Rossell Techsys inside out
Results, valuation, peers and who's buying, in one view.
What EBITDA margin is Rossell Techsys targeting?
Rossell Techsys is targeting an earnings before interest, tax, depreciation and amortisation, or EBITDA, margin of 18% to 23%. Managing Director Rishab Mohan Gupta stated the range in response to a question on a previously discussed 17%-20% range, saying the company remained on track and had further room for improvement as revenue scales.
The 18%-23% range is a management target, not quantified FY 2027 guidance. Q2 FY 2027 EBITDA of Rs 29 crore on revenue of Rs 185.56 crore implies a margin of about 15.6%, below the stated range. Management attributed the potential for expansion to operating leverage and scale, without providing a quarter-by-quarter margin timetable.
Rossell Techsys reported Rs 345 crore of revenue and Rs 52 crore of EBITDA in H1 FY 2027, which management said reflected increasing operating leverage, execution efficiencies and scale. The call did not provide EBITDA by aerospace and defence, semiconductor, space or industrial activity, so the margin contribution of individual business lines was not disclosed.
How did Rossell Techsys perform in Q2 and H1 FY 2027?
Rossell Techsys reported its highest quarterly revenue, EBITDA and profit before tax, or PBT, in Q2 FY 2027. Revenue rose 47% year on year to Rs 185.56 crore, EBITDA reached Rs 29 crore and PBT was Rs 12.91 crore, the first quarterly PBT above Rs 10 crore in the company’s history.
Q2 contributed Rs 185.56 crore of H1 revenue of Rs 345 crore, leaving Rs 159.44 crore for the other quarter of the half-year by calculation. Likewise, Q2 EBITDA of Rs 29 crore exceeded the implied Rs 23 crore in the other quarter. This indicates higher revenue and EBITDA in the second quarter, although Rossell Techsys did not separately disclose Q1 figures on the call.
Management said the third and fourth quarters have historically been Rossell Techsys’s best quarters over the past 10 years and expects the pattern to continue in FY 2027. Gupta declined to provide exact revenue guidance when asked, but said the company should see quarter-on-quarter growth through the second half.
How will the Rs 300 crore raise affect Rossell Techsys profitability?
Rossell Techsys expects to use part of its Rs 300 crore capital raise to repay working-capital limits, which management said should substantially reduce finance costs and increase profitability from Q3 FY 2027. Gupta described the proceeds as a mix for balance-sheet strengthening, loan repayment, future growth, operational excellence and infrastructure.
Management did not disclose the amount of working-capital borrowings to be repaid, the applicable interest rate or a rupee estimate of finance-cost savings. When asked to quantify the reduction, management said a significant portion of the saving should be visible in Q3 results rather than providing a forward estimate.
The Rs 300 crore raise was intended to support Rossell Techsys’s growth requirements for the next three years, according to management. Gupta also said the company did not plan another fundraise anytime soon. As only part of the proceeds is allocated to loan repayment, the eventual profit impact will depend on deployment between debt reduction, infrastructure and operating growth.
Got a follow-up? Ask IRIS
Which operating changes could support Rossell Techsys’s margin plan?
Rossell Techsys is pursuing lower inventory holdings, additional capacity and a larger non-aerospace and defence business to support scale. Inventory carrying levels improved to 6.67 months in Q2 FY 2027 from 7.98 months in Q2 FY 2026, a reduction of 1.31 months despite the larger revenue base.
Management’s internal goal is to become a three-turn inventory company, equivalent to four months of inventory, over the next 24 months. This would require a further 2.67-month reduction from the Q2 FY 2027 level. Management linked the progress to planning, procurement practices and tighter execution controls, without quantifying the associated cash release.
The revenue mix is also changing. Of H1 FY 2027 revenue of Rs 345 crore, management said approximately Rs 130 crore to Rs 140 crore came from non-aerospace and defence activities, and it expects an approximately 50:50 aerospace and non-aerospace split by the end of FY 2027. Rossell Techsys also said space and semiconductor revenue had crossed Rs 140 crore in the first two quarters, compared with Rs 100 crore for those businesses in the prior year.
Rossell Techsys has leased a new Aerospace Park facility of about 140,000 square feet, with an option to expand to 210,000 square feet, and expected it to begin operations early in the following quarter. Management said it would add capacity for semiconductor and other non-defence work. The company also reported Rs 910 crore of confirmed purchase orders for execution over 2.5 years and strategic agreements exceeding Rs 3,100 crore over five years.
Conclusion
Rossell Techsys’s profitability plan combines a stated 18%-23% EBITDA-margin target with higher operating scale, lower inventory carrying levels and a changing revenue mix that includes semiconductor and space activity. Q2 FY 2027 revenue of Rs 185.56 crore, EBITDA of Rs 29 crore and PBT of Rs 12.91 crore provide the reported starting point for that plan.
The next disclosed milestone is Q3 FY 2027, when management expects savings from repayment of working-capital limits to begin appearing in finance costs. Other measures to watch are progress toward the four-month inventory target within 24 months, commissioning of the 140,000-square-foot facility and execution of the Rs 910 crore confirmed order book over 2.5 years.