










S Chand & Company Ltd Reports Q1 FY27 Revenue of ₹114 Crore
Key highlights
- S Chand reported Q1 FY27 revenue of ₹114 crore, up 11.62% year on year from ₹102 crore.
- The company recorded a Q1 FY27 operating loss of ₹20 crore and a net loss of ₹18 crore.
- S Chand retained FY27 operating revenue growth guidance of 10%-15% and EBITDA margin guidance of 17%-19%.
- The company targets content licensing revenue above ₹40 crore in FY27 and plans to increase clients from 5 to 10.
powered by IRIS
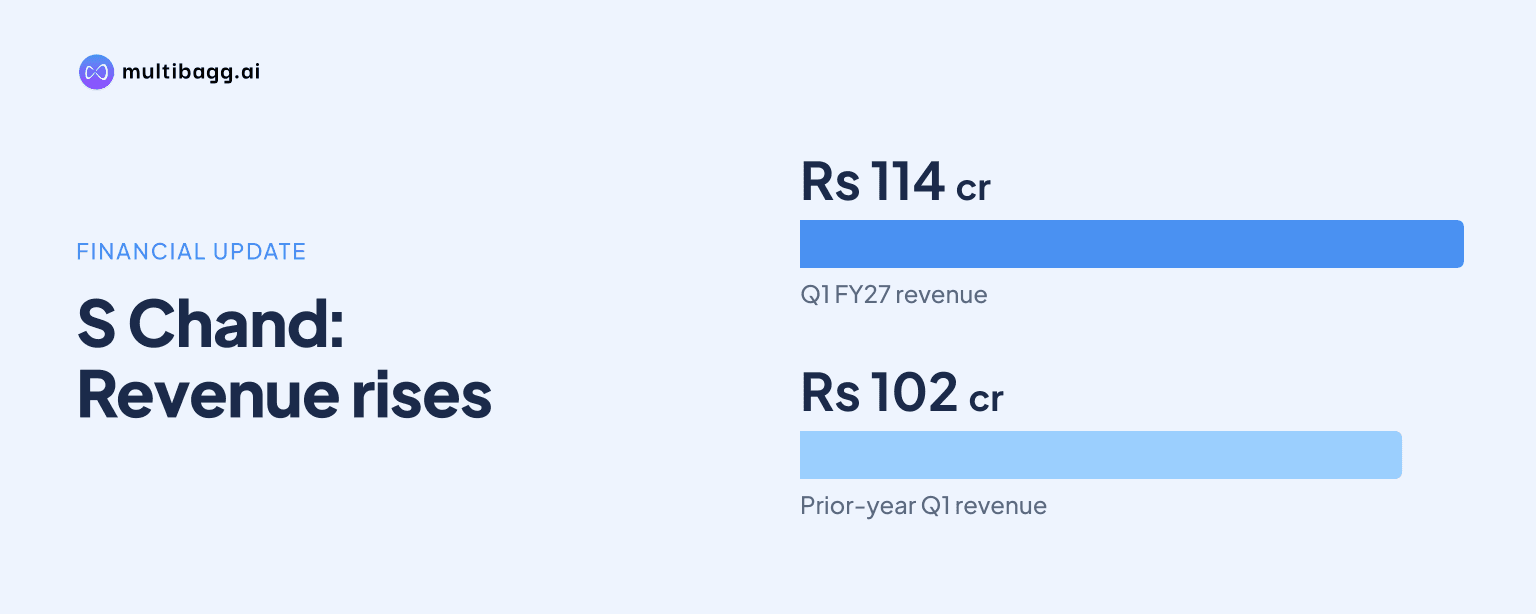
S Chand & Company Ltd reported Q1 FY27 revenue of ₹114 crore, up 11.62% year on year, while recording a consolidated net loss of ₹18 crore for the June 2026 quarter. The result matters because revenue growth continued despite a weak first-quarter profit outcome, and the company has retained its FY27 operating revenue growth guidance of 10%-15%.
Know S Chand & Company inside out
Results, valuation, peers and who's buying, in one view.
What were S Chand's Q1 FY27 financial results?
S Chand reported revenue of ₹114 crore in Q1 FY27, compared with ₹102 crore in Q1 FY26, translating into year-on-year growth of 11.62%. Another company summary described consolidated revenue as ₹114.5 crore, or INR 1,145 million, and cited 12% growth. The small difference reflects rounding in the reported figures.
The company recorded an operating loss of ₹20 crore and a net loss of ₹18 crore in the quarter. The results summary showed that the net loss was 33.21% lower year on year, indicating an improvement from the comparable period even though profitability remained negative. Gross profit was also negative at ₹20 crore in the reported quarter.
The quarter followed a much stronger March 2026 period in the company's historical quarterly data, when sales were reported at ₹548 crore and operating profit at ₹246 crore. Revenue in the June 2026 quarter was reported at ₹115 crore in that quarterly series, which is broadly consistent with the ₹114 crore earnings-results figure after rounding.
Why did S Chand report a loss despite revenue growth?
S Chand's disclosed results show that revenue expansion did not translate into a quarterly operating profit, with an operating loss of ₹20 crore and a net loss of ₹18 crore. The material provided does not specify a single reason for the loss, so the reported figures do not support attributing it to any particular cost item, business segment, or exceptional charge.
The June quarter also showed a sharp sequential movement. Revenue was down 79.09% quarter on quarter, while gross profit and net profit moved into negative territory versus the immediately preceding quarter. The company's quarterly sales pattern shows materially higher revenue in March quarters, including ₹437 crore in March 2024, ₹471 crore in March 2025 and ₹548 crore in March 2026.
This pattern is relevant for investors assessing the June-quarter numbers. S Chand operates in education content, services and solutions, where academic-cycle timing can create uneven quarterly revenue and profit recognition. A single first-quarter loss should therefore be read alongside the company's seasonal sales history and full-year guidance.
What is S Chand's FY27 growth and margin guidance?
S Chand expects operating revenue to grow by 10%-15% in FY27 and has guided for an EBITDA margin of 17%-19%. The guidance provides a full-year benchmark against which investors can compare the 11.62% revenue growth recorded in Q1 FY27.
The company has also set a content licensing revenue target of more than ₹40 crore for FY27. It aims to increase content-licensing clients from five to 10. These targets indicate that licensing is expected to be a measured part of the company's revenue mix during the year.
Management has said that its core business could grow at a steady 10%-12% annually over the next two to three years. It also highlighted repeat adoptions of refreshed curriculum products, including Mylestone, MyZen, SmartK and Solid Steps, in the school education segment during Q1 FY27.
Got a follow-up? Ask IRIS
How is S Chand expanding its education portfolio?
S Chand is expanding its education portfolio through curriculum capabilities aimed at India and Asian markets, according to the information provided. The company said these capabilities fill a gap in its product portfolio and position it for a fast-growing segment.
The group is also marketing the recently acquired CPD Singapore company in India and the Middle East. It expects those international markets to develop over two to three years. The disclosed strategy is focused on building the acquired brand in these markets rather than reporting an immediate financial contribution from the expansion.
The company has stated that it expects the acquired business to cross ₹0.1 crore in revenue by the end of the year. It has also referred to a J-curve growth profile over one to two academic cycles as the brand becomes established in India and the Middle East. These are company expectations, not reported Q1 revenue outcomes.
What does the Q1 result mean for S Chand investors?
S Chand's Q1 result presents two contrasting data points for investors: revenue grew by 11.62% year on year, but the company remained loss-making during the quarter. The revenue growth is within the broad range of the company's FY27 operating revenue guidance, while the operating and net losses make progress on annual margin guidance an important area to monitor.
The market reaction cited alongside the Q1 result showed the share price at ₹141.63, down 2.53%. This movement was reported with the earnings update and should be viewed as a point-in-time market reference. The available information does not establish that the price move was caused solely by the quarterly result.
The next disclosed earnings date is November 5, 2026, for Q2 FY26-27. S Chand's board meeting announcement said the board would consider unaudited standalone and consolidated financial results, with the trading window remaining closed until 48 hours after the results. That update will provide the next reported measure of revenue growth, profitability and progress toward FY27 guidance.
Conclusion
S Chand delivered year-on-year revenue growth in Q1 FY27, reporting ₹114 crore of revenue against ₹102 crore a year earlier. However, the ₹18 crore net loss and ₹20 crore operating loss show that revenue growth had not yet produced a profitable June quarter. The company's historical quarterly figures also point to a business with significant variation across the academic cycle.
Investors will next watch the Q2 FY26-27 results scheduled for November 5, 2026, particularly for updates on the 10%-15% FY27 revenue-growth target, the 17%-19% EBITDA margin guidance, content licensing revenue above ₹40 crore, and the development of CPD Singapore in India and the Middle East.