










Saraswati Saree Depot Reports ₹144.47 Crore Q3 FY26 Revenue
Key highlights
- Saraswati Saree Depot reported Q3 FY26 revenue from operations of ₹144.47 crore.
- Q3 FY26 EBITDA was ₹4.75 crore, with an EBITDA margin of 3.29%.
- Nine-month FY26 revenue rose 4.3% year-on-year to ₹497.63 crore.
- Nine-month FY26 PAT was ₹20.07 crore, with a PAT margin of 4.03%.
powered by IRIS
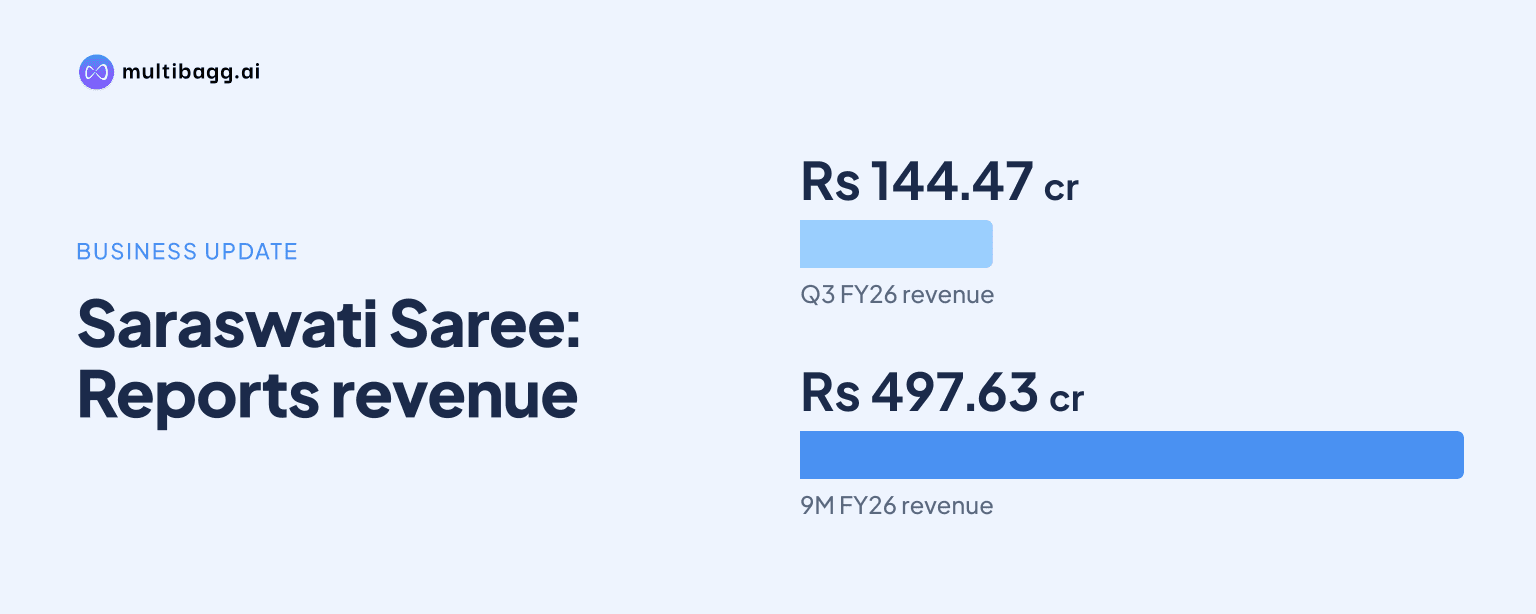
Saraswati Saree Depot Limited (SSDL) reported revenue from operations of ₹144.47 crore in Q3 FY26, while its nine-month revenue increased 4.3% year-on-year to ₹497.63 crore. The quarter reflected seasonal softness, higher input costs and operating deleverage, which reduced EBITDA and profit margins from the comparable period a year earlier.
Know Saraswati Saree Depot inside out
Results, valuation, peers and who's buying, in one view.
Why did SSDL's Q3 FY26 margins decline?
SSDL said its Q3 FY26 EBITDA declined to ₹4.75 crore, with the EBITDA margin narrowing to 3.29% from 12.82 crore in Q3 FY25. The company attributed the pressure to input cost inflation that affected gross margins and to lower operating leverage as sales volumes fell against a relatively fixed cost base.
The company also described Q3 FY25 as a high-base quarter that had benefited from stronger festive demand. In its investor presentation for the quarter ended December 31, 2025, management said the latest quarter saw seasonal softness. Revenue for Q3 FY26 was ₹144.47 crore, while profit after tax stood at ₹3.21 crore.
PAT margin was 2.22% in Q3 FY26, compared with profit after tax of ₹7.88 crore in Q3 FY25. The disclosed figures show that the margin impact was broader than only gross costs, as lower volumes limited the absorption of fixed operating expenses during the quarter.
Management said it expected demand conditions to improve in Q4 FY26, supported by the wedding season. This was presented as the company's outlook for the following quarter, rather than a reported financial result.
What do SSDL's nine-month FY26 results show?
SSDL's revenue from operations for the first nine months of FY26 rose 4.3% year-on-year to ₹497.63 crore, indicating growth over the longer period despite the softer third quarter. The company said this performance reflected underlying momentum in its business.
Nine-month EBITDA was ₹27.79 crore, translating into an EBITDA margin of 5.58%. That compared with a margin of 6.91% in the corresponding nine months of FY25. The difference shows that the cost and operating-leverage pressures identified in the third quarter also affected profitability across the year-to-date period.
PAT for the nine-month period was ₹20.07 crore, with a PAT margin of 4.03%. The company reported that the corresponding nine-month PAT margin in FY25 was 4.93%. Revenue growth therefore did not translate into a higher margin rate during the reported period.
For context, the company had reported H1 FY25 revenue of ₹296.59 crore, up 14%, and PAT of ₹15.67 crore, up 29.9%, in its November 2024 presentation. The FY26 disclosures point to a more challenging margin environment than that earlier period.
What were SSDL's key Q3 and nine-month financial figures?
SSDL reported lower quarterly profitability amid a high festive-demand base, while its nine-month revenue remained higher year-on-year. The following table summarises the figures disclosed in the Q3 FY26 investor presentation.
All monetary figures in the table are stated in crore rupees. The reported EBITDA and PAT comparisons underline the difference between revenue growth over nine months and the margin performance during the period.
The company did not disclose a quarterly revenue figure for Q3 FY25 in the provided presentation extract. It instead noted that the earlier quarter had benefited from seasonally stronger festive demand, making it the comparison base for the Q3 FY26 performance.
Got a follow-up? Ask IRIS
How does SSDL's business model shape its results?
SSDL operates in India's business-to-business saree wholesale segment, with sarees accounting for more than 90% of its main revenue, according to the company presentation. It also manufactures and wholesales dress materials and other women's traditional and ethnic wear, including kurtis, blouse pieces, lehengas, bottoms and accessories.
The company sells through its stores and online channels. It manages two stores in Maharashtra, located in Kolhapur and Ulhasnagar, and reported a total area of more than 235,000 square feet. Its business is classified under a single apparel segment in its integrated filing.
The company traces its origins to 1966 and described its formal launch as occurring in 1993. Its headquarters are in Kolhapur, Maharashtra. The operating model is therefore closely tied to wholesale apparel demand, including seasonal sales patterns associated with festivals and weddings.
The Q3 FY26 update illustrates how seasonal demand and product-input costs can influence the financial profile of an apparel wholesaler. Stronger wedding-season demand is important to the company's stated expectation of a Q4 FY26 recovery, while procurement costs and sales volumes remain relevant to margin performance.
What does the Q3 FY26 update mean for investors?
The Q3 FY26 update shows that SSDL maintained nine-month revenue growth but faced a significant reduction in quarterly EBITDA and PAT as margins contracted. For investors, the disclosed 3.29% quarterly EBITDA margin and 2.22% PAT margin are central indicators of the impact from input-cost pressure and lower operating leverage.
The comparison with the nine-month period provides a broader view. Revenue was higher by 4.3%, but the EBITDA margin declined by 133 basis points to 5.58%, while the PAT margin declined by 90 basis points to 4.03%. These disclosed changes indicate that profitability grew more slowly than revenue over the period.
SSDL is listed on the National Stock Exchange under the symbol SSDL and on BSE under scrip code 544230. The investor presentation was released under Regulation 30 of the Securities and Exchange Board of India (Listing Obligations and Disclosure Requirements) Regulations, 2015.
The company has not provided a quantified Q4 FY26 revenue or margin target in the supplied information. Its stated expectation is for a recovery supported by wedding-season demand, while the level of input costs and the ability to improve operating leverage remain relevant factors in assessing subsequent results.
Conclusion
SSDL's Q3 FY26 performance combined ₹144.47 crore of quarterly revenue with lower profitability, as seasonal softness, input cost pressure and lower operating leverage compressed margins. At the same time, nine-month revenue rose 4.3% to ₹497.63 crore, showing that the business remained ahead of the prior year on a cumulative sales basis despite the weaker quarter.
The next point to watch is the company's reported Q4 FY26 performance, given management's expectation that wedding-season demand could support recovery. Investors will also be able to assess whether EBITDA and PAT margins improve from the Q3 FY26 levels as volume conditions and input costs develop.