










Saraswati Saree Depot Limited flags senior-team alignment
Key highlights
- Saraswati Saree Depot reported H1 FY27 revenue of Rs 290.977 crore, down 17.6% year on year.
- Saraswati Saree Depot's Q2 FY27 revenue declined 31.2% to Rs 143.387 crore as Diwali shifted into Q3.
- Saraswati Saree Depot's inventory rose by Rs 60.81 crore to Rs 181.501 crore in September 2026 for festive dispatches.
- Saraswati Saree Depot reported liquidity above Rs 88.5 crore, net worth of Rs 196.3 crore and no debt.
powered by IRIS
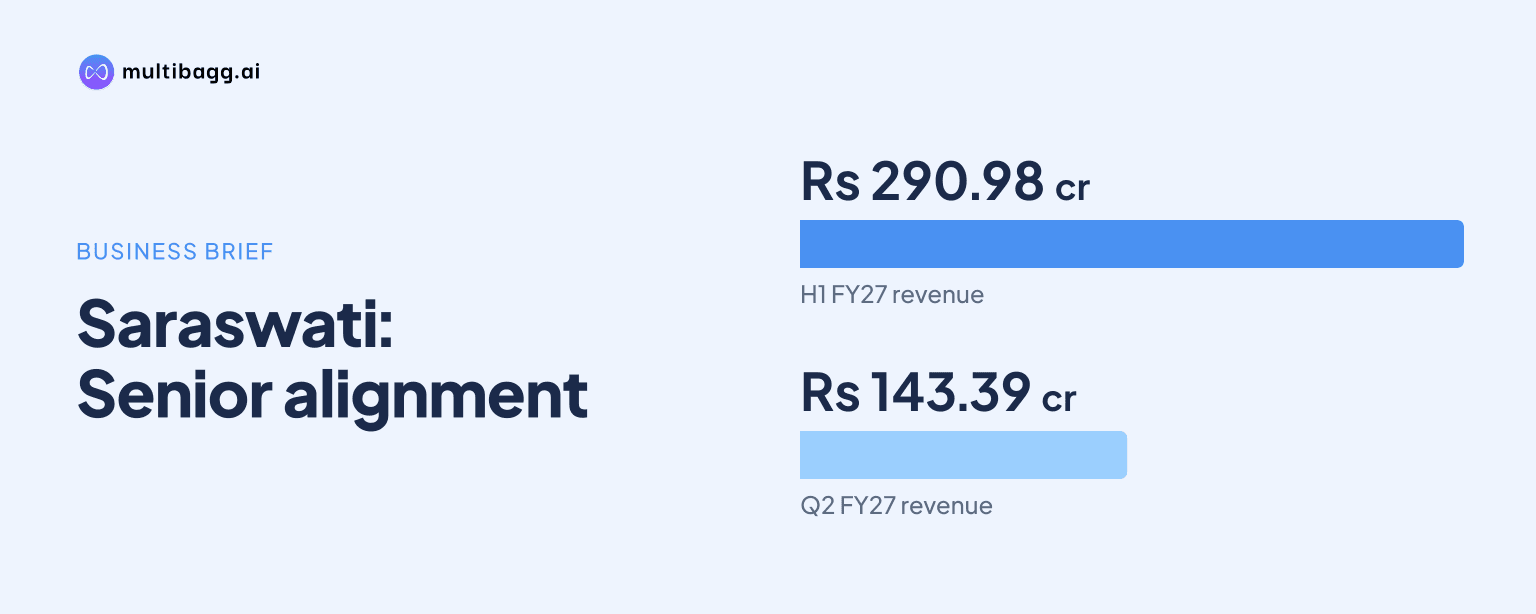
Saraswati Saree Depot said senior-team differences on priorities, sequencing and execution affected operating consistency in H1 FY27, when revenue declined 17.6% year on year to Rs 290.977 crore. The chairman said internal misalignment and subdued retailer demand could weigh on the order book over the next few quarters.
Know Saraswati Saree Depot inside out
Results, valuation, peers and who's buying, in one view.
Why is Saraswati Saree Depot flagging an execution risk?
Saraswati Saree Depot is flagging an execution risk because its Board observed that operational decision-making had not always matched the pace of its strategic agenda. Chairman Rajesh Dulhani said differing views within the senior team had emerged on the sequencing of initiatives, priorities and the manner of execution as the company expanded across multiple locations, responsibilities and a developing retail footprint.
The chairman described the matter as an alignment issue rather than a reflection on the ability or intent of any individual. He said the business has moved beyond its earlier focused wholesale model, and internal alignment had at times needed to catch up with the Board's direction. The stated effect has been on the pace and consistency of operating decisions, which is relevant while the company manages wholesale demand, procurement and retail expansion.
Saraswati Saree Depot said the senior-management issue is one of two reasons it expects the operating environment to remain subdued for a few more quarters. The other is weak demand at retailer counters, where the chairman said both footfalls and conversion remain subdued. Since the company sells through a wholesale retailer network, slower retail sell-through can reduce the pace of fresh orders placed with it.
How did Saraswati Saree Depot perform in H1 FY27?
Saraswati Saree Depot reported lower revenue, earnings before interest, tax, depreciation and amortisation (EBITDA), and profit after tax in H1 FY27. Revenue from operations declined 17.6% year on year to Rs 290.977 crore, while profit after tax fell to Rs 13.992 crore from Rs 16.861 crore in H1 FY26. Basic earnings per share declined to Rs 3.53 from Rs 4.26.
Saraswati Saree Depot's EBITDA margin decreased to 5.66% in H1 FY27 from 6.52% a year earlier, a decline of 0.86 percentage points. Managing Director and Chief Executive Officer Vinod Dulhani attributed the lower profitability largely to higher procurement costs, partly offset by reductions in finance costs, depreciation and overheads. He said management is addressing procurement costs through better vendor engagement.
The half-year comparison differed from the sequential Q2 trend. Q2 FY27 profit after tax was Rs 7.387 crore, about 12% above Rs 6.605 crore in Q1 FY27, despite marginally lower revenue. The Managing Director and Chief Executive Officer attributed the quarter-on-quarter profit movement to tighter cost control during Q2.
Got a follow-up? Ask IRIS
How much did the Diwali timing affect Saraswati Saree Depot's sales?
Saraswati Saree Depot said the Diwali calendar shift moved a substantial part of pre-festive wholesale buying from Q2 FY27 into Q3 FY27. Q2 revenue from operations was Rs 143.387 crore, down 31.2% from Rs 208.381 crore in Q2 FY26. Management said Diwali fell in Q2 in the prior year but falls in Q3 in FY27, making the two second quarters not directly comparable.
The company said Q2 FY27 should instead be assessed alongside Q3 performance because festive wholesale offtake has shifted into that later period. This timing effect accounted for most of the H1 revenue decline, according to the Managing Director and Chief Executive Officer. It does not, however, eliminate the separate risk from slower retailer trading conditions, which management said had started to affect fresh purchase orders.
Inventory rose to Rs 181.501 crore in September 2026 from Rs 120.691 crore in March 2026, an increase of Rs 60.81 crore. Saraswati Saree Depot said this was a deliberate inventory build-up ahead of festive dispatches. The inventory movement gives a balance-sheet measure of the sales expected to be served during the later festive period.
What is Saraswati Saree Depot doing to address management misalignment and demand?
Saraswati Saree Depot has initiated a structured review of decision-making authority, inter-functional cadence, performance measurement and accountability frameworks. The chairman said the review began over the past few months and is intended to improve internal alignment, information-sharing and single-voice execution in the quarters ahead. The presentation does not identify a management change or name a specific executive responsible for the issue.
On demand, Saraswati Saree Depot said it is staying close to retailer customers, calibrating procurement and offering flexible commercial terms where those terms help retailers rotate stock. Management also said it aims to avoid excess channel inventory that could reduce future demand. These actions address a wholesale environment in which retailer footfalls are softer and stock rotation has slowed.
For the rest of FY27, the Managing Director and Chief Executive Officer listed a sharper product mix, a measured and disciplined retail-footprint rollout, and profitable growth as operating priorities. The chairman said Saraswati Saree Depot remained debt-free, with liquidity above Rs 88.5 crore and net worth of Rs 196.3 crore. He said that balance-sheet position gives the company scope to take long-term decisions while preserving financial flexibility.
Conclusion
Saraswati Saree Depot's disclosure combines a calendar-driven sales shift, weaker retailer demand and an internal execution issue. H1 FY27 revenue fell by Rs 62.149 crore from the prior-year period, while EBITDA margin declined to 5.66% from 6.52%. The Board has explicitly linked senior-team differences on priorities and execution to the consistency of operational decision-making.
The next disclosed milestones are Q3 FY27 festive dispatches after September 2026 inventory reached Rs 181.501 crore, and the progress of the review of decision rights, inter-functional coordination and accountability. Management has also said retailer footfalls, conversion and stock rotation may remain subdued for the next few quarters, making the pace of fresh wholesale orders a continuing unresolved matter.