










Sarthak welding sales reach Rs 19.9 crore, nearing annual target
Key highlights
- Sarthak’s flux cored wire revenue reached Rs 19.9 crore in the twelve months to 30 September 2026.
- Flux cored wire volume rose 25% from 1,415 tonnes in FY26 to 1,764 tonnes in TTM Sep-26.
- Sarthak reported Q2 FY27 welding revenue of Rs 5.6 crore, up 49% year on year.
- The welding plant is about 50% utilised, while management’s annual sales target is Rs 25 crore.
powered by IRIS
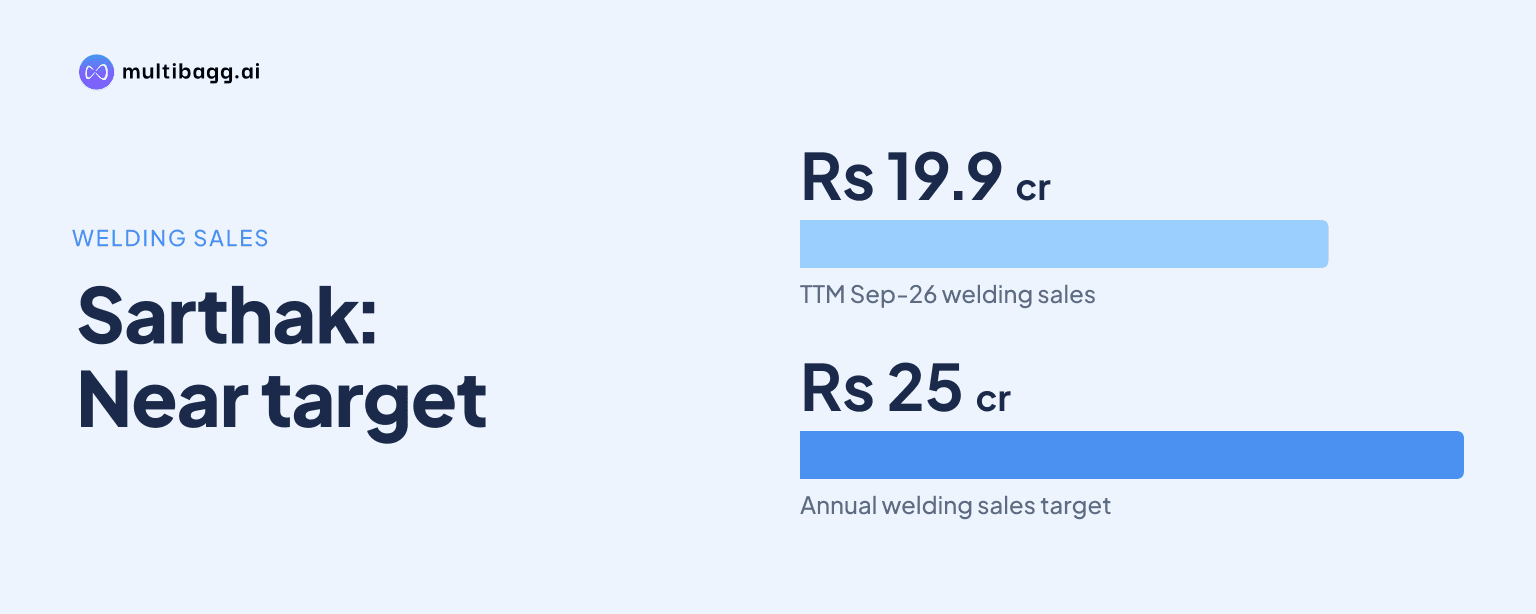
Sarthak Metals Limited recorded Rs 19.9 crore of flux cored wire revenue in the twelve months to 30 September 2026, equal to about 80% of management’s Rs 25 crore annual sales target. The welding unit sold 1,764 tonnes over that period, while its plant was only about half utilised.
Know Sarthak Metals inside out
Results, valuation, peers and who's buying, in one view.
How close is Sarthak to its Rs 25 crore welding target?
Sarthak was about 80% of management’s Rs 25 crore annual welding-sales target, based on Rs 19.9 crore of trailing 12-month revenue to September 2026. The flux cored wire business reported Rs 5.6 crore of revenue in Q2 FY27, up 49% year on year, and Rs 10.7 crore in the first half of fiscal year 2027, or H1 FY27, up 66%.
The reported revenue base has expanded since the unit’s initial disclosed period. Sales were Rs 5.5 crore in FY25, which covers July 2024 to March 2025, then rose to Rs 15.7 crore in FY26 and Rs 19.9 crore in the trailing 12 months, or TTM, to September 2026. The TTM figure was Rs 4.2 crore above FY26, although it is a rolling 12-month measure rather than a completed financial year.
What is driving Sarthak’s welding sales growth?
Sarthak’s welding-sales growth was primarily volume-led, as TTM volume increased 25% to 1,764 tonnes from 1,415 tonnes in FY26 while realisation moved only to Rs 113 per kilogram from Rs 111 per kilogram. The source describes growth as almost entirely volume-led because realisation remained within a Rs 111-Rs 116 per kilogram range across the reported periods.
Quarterly volumes have also increased consistently for two years. Flux cored wire volume rose from 126 tonnes in Q2 FY25 to 465 tonnes in Q2 FY27, while the 1,764 tonnes sold in TTM Sep-26 were nearly four times the 472 tonnes reported for the nine months of FY25. Revenue rose in line with this throughput, from Rs 5.5 crore in FY25 to Rs 19.9 crore in TTM Sep-26.
Can Sarthak grow welding output without a new plant?
Sarthak says its flux cored wire plant is only about half utilised, so the business can grow without major new investment. At the current TTM scale of Rs 19.9 crore and 1,764 tonnes, this provides disclosed spare operating capacity, although Sarthak does not state total production capacity in tonnes.
Sarthak’s stated route to higher utilisation includes taking its welding range into more states through existing dealers. Management says this approach widens reach without adding much cost, and it is being pursued from a relatively small base: welding revenue was Rs 5.6 crore in Q2 FY27, against Rs 38.6 crore for the larger cored wire business in the same quarter.
Certifications support the distribution and customer-access plan. Sarthak cites Bureau of Indian Standards certification, CE certification and Research Designs and Standards Organisation approval for Indian Railways as qualifications that provide access to institutional and government buyers. These approvals do not establish future orders, but they are part of the company’s disclosed plan to convert spare utilisation into sales.
Got a follow-up? Ask IRIS
What market conditions affect Sarthak’s welding expansion?
Sarthak operates in a domestic flux cored wire market that management estimates at Rs 500-Rs 600 crore. It identifies Ador Welding, ESAB, Royal Arc, D&H and Hyundai Welding as established competitors, while stating that product quality, certifications and responsive local supply form its competitive positioning.
Management links demand for flux cored wire to automation, productivity needs in shipbuilding and fabrication, and quality norms of the Bureau of Indian Standards. The presentation also says India imported an average of about 14,500 tonnes of flux cored wire a year during 2020-22, while management estimates Sarthak’s TTM Sep-26 revenue at Rs 19.9 crore within the domestic market it sizes at Rs 500-Rs 600 crore.
Welding remains smaller than Sarthak’s core cored wire operation. Cored wire generated Rs 151.3 crore of revenue in TTM Sep-26, and Q2 FY27 sales were Rs 38.6 crore, compared with Rs 5.6 crore from welding and Rs 4.4 crore from aluminium flipping coils. Welding expansion can therefore add to group sales, but the disclosed segment data show it was not the principal business at September 2026.
How does Sarthak’s financial position support its welding plan?
Sarthak reported no long-term debt at September 2026, while short-term working-capital borrowings fell to Rs 2.6 crore from Rs 6.6 crore in March 2026. Gross cash, comprising cash, bank balances and other financial assets, increased by Rs 2.3 crore during H1 FY27 to about Rs 17.0 crore, and net worth stood at about Rs 127 crore.
Cash from operations was Rs 4.1 crore in H1 FY27, compared with a cash outflow for the full FY26. Management attributed the movement to customer collections and lower inventory, and its stated priorities include faster receivable collection, lean inventory and capital discipline in newer initiatives. Sarthak has invested about Rs 50 lakh in a biotechnology pilot research and development facility at Nagpur, with further capital contingent on clearer commercial viability.
At the group level, H1 FY27 revenue was Rs 107.6 crore, up 30% year on year, and net profit was Rs 2.6 crore, up 43%. Q2 FY27 revenue was Rs 52.4 crore, up 44%, while net profit was Rs 1.28 crore, up 68%. These figures provide the financial context for management’s welding expansion plan, rather than a commitment to a specific future revenue outcome.
What should investors track in Sarthak’s next welding updates?
Sarthak’s next reported welding indicators will include volume after the 465 tonnes recorded in Q2 FY27, revenue after Rs 5.6 crore in that quarter, and the movement in realisation from Rs 113 per kilogram in TTM Sep-26. These measures will show whether further sales gains remain driven by tonnage, as they were between FY26 and TTM Sep-26.
Investors can also track working-capital execution as Sarthak expands distribution. Short-term borrowings declined by Rs 4.0 crore between March and September 2026, while H1 FY27 operating cash flow reached Rs 4.1 crore. Management has said it will scale welding toward its annual target while improving receivables and keeping inventory lean.
Conclusion
Sarthak’s welding unit has grown from Rs 5.5 crore of revenue in its nine-month FY25 reporting period to Rs 19.9 crore in TTM Sep-26. The disclosed increase was led by volume, which reached 1,764 tonnes, while realisation remained in a narrow Rs 111-Rs 116 per kilogram range. About half of plant utilisation leaves disclosed capacity for additional output without major immediate investment.
The next issue is whether dealer expansion, certifications and institutional access can lift quarterly sales beyond the Rs 5.6 crore reported in Q2 FY27. Management’s disclosed plan is to pursue the Rs 25 crore annual sales target while maintaining working-capital discipline, but the target remains a management objective and competition in the estimated Rs 500-Rs 600 crore domestic market remains relevant.