










Shakti Pumps (India) Ltd gains 9.36% weekly despite pressure
Key highlights
- Shakti Pumps gained 9.36% in the reported week, versus a 1.26% rise in the Sensex.
- Q2 FY27 revenue rose 12% year on year to Rs. 746 crore, while EBITDA fell 52.9% to Rs. 64 crore.
- The share was down 47.49% over one year but up 120.08% over three years in the supplied return table.
- October collections of about Rs. 400 crore reduced borrowings from around Rs. 830 crore to below Rs. 500 crore, according to management.
powered by IRIS
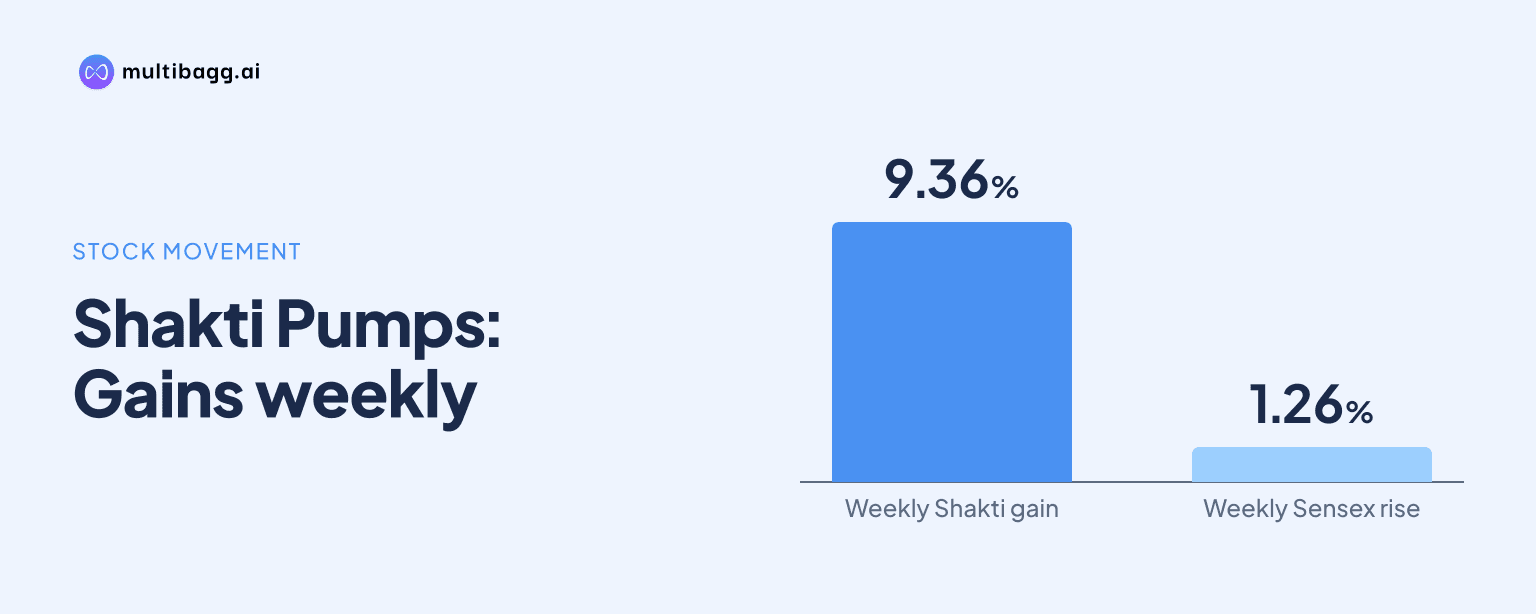
During the reported week, Shakti Pumps (India) Ltd gained 9.36%, outpacing the Sensex's 1.26% rise, although the recovery followed substantial declines across longer periods and came alongside weaker profitability in Q2 FY27. The move reflected a sharp rally followed by a valuation reassessment in the supplied market discussion.
Why did Shakti Pumps gain 9.36% in a week?
Shakti Pumps gained 9.36% during the reported week as sentiment improved around solar-pump execution and its working-capital position. The stock's weekly advance exceeded the Sensex's 1.26% increase, even after a day of decline within the week. Another cited market snapshot put the one-week gain at 9.91%, underlining that the rebound was sharp but accompanied by volatile trading.
The immediate discussion centred on installations, collections and debt reduction rather than a confirmed new major order announcement. Solar-pump installations rose 29.3% year on year to 51,543 units in H1 FY27. Management said it received about Rs. 400 crore of delayed collections in October, which reduced borrowings from roughly Rs. 830 crore to below Rs. 500 crore.
How has Shakti Pumps performed beyond the weekly rebound?
Shakti Pumps has delivered strong multiyear returns, but its recent share-price record remains weak. The supplied return data show a 47.49% decline over one year and a 120.08% gain over three years. A separate market update cited a 46.50% year-to-date fall and a 46.97% decline over one year, while also reporting a 124.13% three-year gain.
This contrast matters for portfolio assessment. A weekly recovery does not by itself reverse a six-month decline of 28.2% or the stated one-year fall. Over the past 52 weeks, the share traded between Rs. 345.00 and Rs. 796.20, indicating the scale of the price swings investors have faced.
What do Shakti Pumps' Q2 FY27 results show?
Shakti Pumps' Q2 FY27 results show revenue growth but significant pressure on operating profit and net profit. Consolidated revenue from operations increased 12% year on year to Rs. 746 crore, compared with Rs. 666.4 crore in the corresponding quarter. However, EBITDA fell 52.9% to Rs. 64 crore from Rs. 136 crore.
Profitability weakened despite higher revenue and installation activity. Q2 FY27 net profit was about Rs. 38.5 crore, down roughly 58% year on year, while EBITDA margin contracted to 8.6% from 20.4% a year earlier. The supplied discussion attributed the pressure to lower realisations, higher raw-material prices and logistics costs.
The broader recent financial trend is also mixed. Revenue was reported to have fallen for two consecutive periods from Rs. 869.01 crore to Rs. 758.48 crore, while net profit declined from Rs. 51.59 crore to Rs. 38.51 crore. The stated trailing P/E ratio was 30.30, making earnings recovery and margin performance relevant to how investors view the valuation.
Got a follow-up? Ask IRIS
What could improve Shakti Pumps' liquidity and outlook?
Shakti Pumps could benefit from faster collection of receivables, execution of its existing order book and continued solar-pump demand under government programmes. The outstanding order book stood at Rs. 751 crore, including GST, as of October 23, 2026. The October collections were notable because delayed government receivables had contributed to higher borrowings and pressure on cash flows.
The company also began trial production in October at its first 0.5 GW solar-module facility, part of a planned 2.2 GW capacity. Management and market commentary identified expectations around PM-KUSUM 2.0 and further orders under Maharashtra's Magel Tyala solar-pump scheme as important sentiment drivers. Choice Broking maintained an add rating with a Rs. 410 target price, while saying it remained cautious pending a renewed KUSUM scheme announcement.
Ownership data showed a small rise in retail investor holdings to 42.55% in the September 2026 quarter from 42.17%. Mutual fund holdings, however, decreased to 1.69% from 2.33%. These changes do not determine future share performance, but they add context to the differing views on the company's near-term outlook.
Conclusion
Shakti Pumps' 9.36% weekly gain points to renewed attention on installations, delayed-payment collections and lower borrowings. Yet the wider portfolio picture is more complex: the share remains materially lower over one year, while Q2 FY27 revenue growth did not prevent a sharp decline in EBITDA, margin and net profit. Its long-term return record and recent operating pressure therefore present two different signals for investors.
The next indicators to watch are execution of the Rs. 751 crore order book, the effect of lower borrowings after October collections, and whether margins recover from the Q2 FY27 level. Developments around PM-KUSUM 2.0, Maharashtra solar-pump orders and scaling of the planned solar-module capacity will also remain relevant to the outlook.