










Shellz India H1 FY27 PAT Rises 31% as Margin Hits 18.41%
Key highlights
- Shellz India reported H1 FY27 revenue from operations of Rs 95.66 crore, up 4.1% from Rs 91.87 crore.
- Shellz India’s H1 FY27 EBITDA was Rs 17.61 crore and EBITDA margin was 18.41%, versus 15.78% in H1 FY26.
- Shellz India’s H1 FY27 PAT rose 30.9% to Rs 8.19 crore, with PAT margin increasing to 8.56%.
- Shellz India’s H1 FY27 figures are consolidated, while H1 FY26 figures are standalone.
powered by IRIS
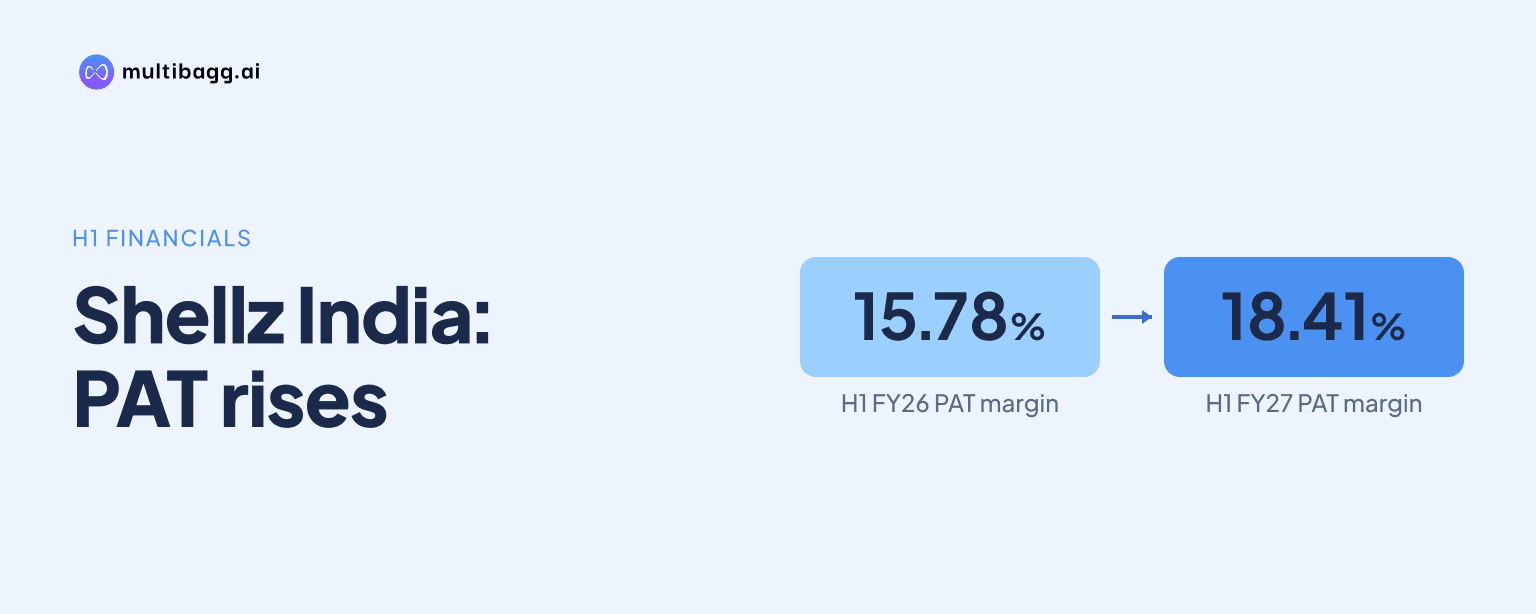
Shellz India Limited reported profit after tax of Rs 8.19 crore for the six months ended September 30, 2026, up 30.9% from Rs 6.26 crore, while EBITDA margin reached 18.41% from 15.78%. Revenue from operations rose 4.1% to Rs 95.66 crore, although the H1 FY27 consolidated results are compared with standalone H1 FY26 figures.
Know Shellz India inside out
Results, valuation, peers and who's buying, in one view.
How did Shellz India perform in H1 FY27?
Shellz India reported revenue from operations of Rs 95.66 crore in H1 FY27, compared with Rs 91.87 crore in H1 FY26. Total income rose to Rs 96.23 crore from Rs 92.10 crore, with other income increasing to Rs 0.58 crore from Rs 0.24 crore over the same six-month periods.
Shellz India reported EBITDA of Rs 17.61 crore, up 21.4% from Rs 14.50 crore in H1 FY26, and its EBITDA margin rose by 2.63 percentage points to 18.41%. The presentation defines EBITDA as profit before tax and exceptional items plus finance costs plus depreciation and amortisation, less other income.
Why did Shellz India’s profit rise faster than revenue?
Shellz India’s reported profit after tax rose by Rs 1.93 crore to Rs 8.19 crore, exceeding the Rs 3.79 crore increase in revenue from operations. PAT margin increased to 8.56% from 6.82%, while EBITDA rose by Rs 3.11 crore and the EBITDA margin increased to 18.41%.
The income statement shows total expenses of Rs 84.55 crore in the half year ended September 30, 2026, compared with Rs 83.37 crore a year earlier, an increase of Rs 1.18 crore. Total income increased by Rs 4.13 crore, profit before tax rose to Rs 11.68 crore from Rs 8.74 crore, and neither period recorded exceptional items.
Are Shellz India’s H1 FY27 and H1 FY26 results directly comparable?
No, Shellz India’s H1 FY27 and H1 FY26 figures use different reporting perimeters. The six months ended September 30, 2026 are consolidated financial results, while the six months ended September 30, 2025 are standalone because Shellz Overseas Private Limited became a subsidiary in March 2026.
This scope difference applies to the reported 4.1% revenue growth, 21.4% EBITDA growth and 30.9% PAT growth. The presentation identifies FY26, ended March 31, 2026, as audited and consolidated, reporting revenue of Rs 192.62 crore, EBITDA of Rs 31.54 crore and PAT of Rs 13.16 crore; FY25 figures are restated standalone financials.
The earnings-per-share comparison also has a stated share-structure difference. Basic and diluted EPS was Rs 9.40 in H1 FY27 and was not annualised, while H1 FY26 EPS of Rs 90.32 was reported before a 1:1 sub-issue.
Got a follow-up? Ask IRIS
How do Shellz India’s H1 FY27 margins compare with FY26?
Shellz India’s H1 FY27 EBITDA margin of 18.41% was 2.03 percentage points above the 16.38% reported for FY26. Its PAT margin of 8.56% was 1.73 percentage points above FY26’s 6.83%, based on the September 2026 half-year financial results and audited March 2026 figures.
The presentation’s reported full-year margin series shows EBITDA margin at 11.7% in FY24, 12.2% in FY25 and 16.4% in FY26. PAT margin moved from 3.2% in FY24 to 4.4% in FY25 and 6.8% in FY26, but FY24 and FY25 are standalone while FY26 and H1 FY27 are consolidated.
What do Shellz India’s balance sheet and cash flow show?
Shellz India’s total borrowings were Rs 128.26 crore at September 30, 2026, up from Rs 100.83 crore at March 31, 2026. Long-term borrowings increased to Rs 51.06 crore from Rs 45.98 crore, short-term borrowings rose to Rs 77.20 crore from Rs 54.85 crore, and shareholders’ funds increased to Rs 68.36 crore from Rs 60.16 crore.
Capital work-in-progress increased to Rs 65.18 crore at September 30, 2026 from Rs 11.33 crore at March 31, 2026. The cash-flow statement recorded Rs 35.81 crore of operating cash inflow, Rs 59.20 crore of net cash used in investing activities and Rs 22.84 crore generated from financing activities during H1 FY27.
Shellz India closed H1 FY27 with cash and cash equivalents of Rs 0.59 crore, down from Rs 1.14 crore at March 31, 2026. The presentation says advances to suppliers include advances for plant and machinery for the Sonipat facility, which remain in short-term loans and advances until machinery is received and capitalised.
What should readers watch in Shellz India’s next results?
Readers should watch for a comparable consolidated prior-period disclosure, because the reported H1 FY27 growth rates compare consolidated figures with standalone H1 FY26 figures. The reported H1 FY27 revenue of Rs 95.66 crore, EBITDA of Rs 17.61 crore and PAT of Rs 8.19 crore therefore reflect a changed reporting perimeter after March 2026.
Readers should also track capital work-in-progress of Rs 65.18 crore and total borrowings of Rs 128.26 crore at September 30, 2026. The presentation links supplier advances to machinery for the Sonipat facility, while H1 FY27 investing outflow of Rs 59.20 crore exceeded the Rs 35.81 crore operating cash inflow.
Conclusion
Shellz India reported H1 FY27 profit growth ahead of revenue growth, with PAT increasing 30.9% to Rs 8.19 crore on 4.1% revenue growth to Rs 95.66 crore. EBITDA increased 21.4% to Rs 17.61 crore, and EBITDA margin rose to 18.41%, while total expenses increased by Rs 1.18 crore against a Rs 4.13 crore rise in total income.
The next disclosures will show whether machinery advances for the Sonipat facility are received and capitalised from the Rs 65.18 crore capital work-in-progress balance. They will also clarify borrowing and cash-flow developments after total borrowings rose by Rs 27.43 crore during the six months ended September 30, 2026, and whether a consolidated comparable period is provided.