










Shilpa Medicare Limited Posts ₹538 Crore Q2 Revenue, ₹79 Crore PAT
Key highlights
- Shilpa Medicare reported record Q2 FY27 revenue of ₹538 crore, up 35% year on year on the earnings call.
- Q2 FY27 EBITDA reached ₹151 crore, up 37% year on year, with a 28% margin.
- First-half FY27 revenue rose 44% to ₹1,007 crore, crossing ₹1,000 crore for the first time.
- Shilpa Medicare spent ₹252 crore on H1 FY27 capex while net debt remained at ₹612 crore.
powered by IRIS
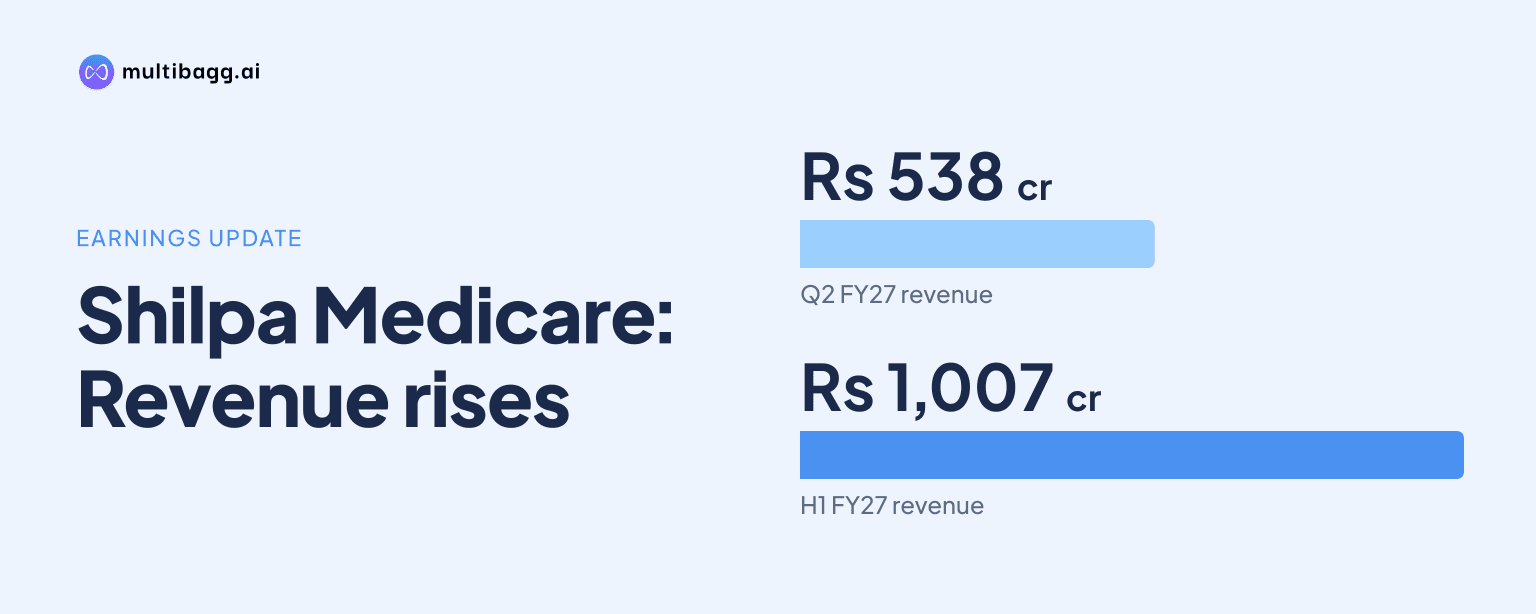
Shilpa Medicare Limited reported record Q2 FY27 revenue of ₹538 crore, up 35% year on year, and profit after tax of about ₹79 crore. The quarter also delivered EBITDA of ₹151 crore at a 28% margin, while first-half revenue crossed ₹1,000 crore for the first time.
Know Shilpa Medicare inside out
Results, valuation, peers and who's buying, in one view.
What did Shilpa Medicare report for Q2 FY27?
Shilpa Medicare reported its highest-ever quarterly revenue of ₹538 crore for Q2 FY27, according to management's earnings-call remarks on 5 November 2026. CFO Alpesh Dalal said the figure represented 35% year-on-year growth, while EBITDA increased 37% to ₹151 crore and the EBITDA margin stood at 28%.
The company reported quarterly PAT of ₹79 crore on the call. Separately, the reported-results summary stated revenue from operations of ₹529.1 crore, up 43.0% year on year, and net profit of ₹79.2 crore, up 79.6%. The investor presentation also cited Q2 revenue of ₹538 crore, but described its growth as 45% year on year. These figures use different reported labels or bases in the supplied disclosures, and the available material does not reconcile the revenue-growth differences.
How did the first-half performance and API business develop?
Shilpa Medicare recorded first-half FY27 revenue of ₹1,007 crore, a 44% year-on-year increase, marking the first time its half-year revenue exceeded ₹1,000 crore. First-half EBITDA was ₹290 crore, up 40%, with a 29% margin, while PAT was ₹180 crore. Management described the first-half profit growth as nearly 100% from the prior-year period.
The non-captive API business contributed ₹255 crore in quarterly revenue, up 24% year on year. For the first half, non-captive API revenue was ₹470 crore, a 20% increase. Management said the broader quarterly performance was supported by growth across its business verticals, though the supplied call extract does not provide revenue figures for each of the other segments.
Operating profit before the share of profit from joint ventures and associates, and before exceptional items, was ₹104 crore in Q2 and ₹202 crore in the first half. These measures indicate that the company generated higher operating earnings alongside revenue growth during the period.
What products and capacity plans did management outline?
Shilpa Medicare said it remains on track to complete more than 15 new oncology generic products during FY27. Management also highlighted a pipeline of more than 25 non-captive CDMO client programmes and said it expects four partner programmes to commercialise over the next 18 to 24 months.
The company is building integrated peptide manufacturing capacity and said commissioning of the facility, described by management as one of the largest such capacities, remains on track by the end of FY27. These initiatives reflect its stated strategy around complex finished dosage forms, CDMO services, biologics and recombinant human albumin, or rHA.
On Ondansetron, management said an India launch would follow final central marketing approval. It added that state-level approvals, licences and permissions would still be required after central approval, indicating that commercial availability depends on completion of the regulatory process.
Got a follow-up? Ask IRIS
What do margins, capital spending and debt show?
Shilpa Medicare's reported EBITDA margin was 28% in Q2 and 29% for the first half, despite an earnings-call summary stating that gross margin declined by roughly 700 basis points. The supplied management remarks provide EBITDA figures but do not give a detailed explanation or a numerical gross-margin bridge for that decline.
Capital expenditure was ₹252 crore in the first half of FY27 and was primarily funded through internal accruals, according to management. Net debt stood at ₹612 crore and was described as stable despite the stepped-up capital-expenditure programme. The company reported return on capital employed of 13.3%, compared with 9% in FY25, and adjusted ROCE of 18.3%.
How should investors read the Q2 FY27 disclosures?
Shilpa Medicare's results show strong growth in revenue, EBITDA and profit, supported by the API business and management's wider product and CDMO plans. The first-half revenue milestone and the increase in ROCE are relevant because they indicate improved scale and operating leverage while the company continues to invest in capacity.
At the same time, investors have limited detail in the supplied transcript excerpt on the gross-margin movement, segment-wise profitability and the basis for differences between the call, presentation and results-summary revenue metrics. No share-price movement or market reaction was provided in the material. Management's programme commercialisation and peptide-capacity targets therefore remain important disclosed markers for tracking execution.
Conclusion
Shilpa Medicare delivered record quarterly revenue of ₹538 crore, EBITDA of ₹151 crore and PAT of about ₹79 crore in Q2 FY27, while first-half revenue reached ₹1,007 crore. The results point to improved operating scale, but the reported gross-margin decline and differing revenue-growth references require careful reading of the underlying disclosures.
The next disclosed milestones are completion of more than 15 oncology generic products in FY27, commissioning of peptide manufacturing capacity by FY27-end, and potential commercialisation of four CDMO partner programmes over the next 18 to 24 months. Final marketing authorisation and subsequent state approvals will also determine the timing of an Ondansetron launch in India.