










Shristi faces going-concern uncertainty after net-worth erosion
Key highlights
- Auditors said Shristi’s net worth was fully eroded at September 30, 2026.
- Cumulative unprovided and defaulted interest on Srei Equipment Finance borrowings was Rs 137.5222 crore.
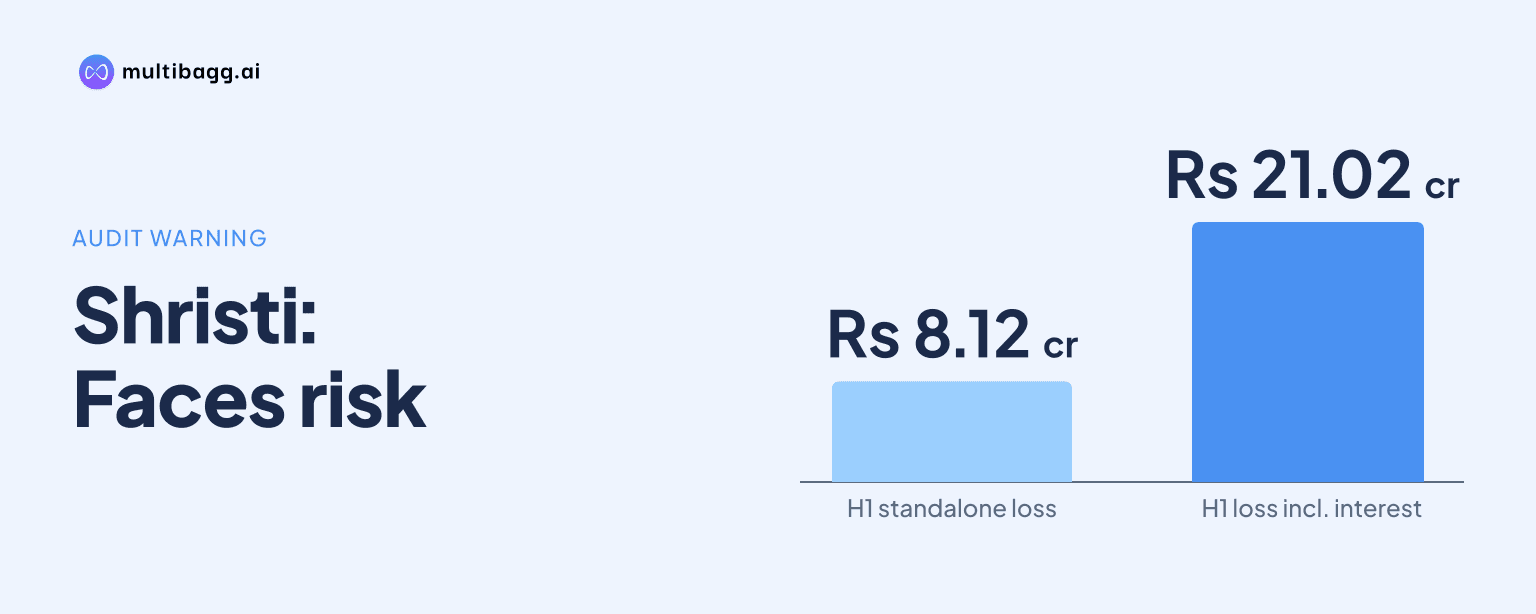
- Recognising the interest would widen standalone half-year loss from Rs 8.1203 crore to Rs 21.0167 crore.
- The arbitration award cited in the filing is Rs 761 crore plus Rs 13.9 crore of interest calculated to April 30, 2019.
powered by IRIS
Shristi Infrastructure Development Corporation Limited faces material uncertainty over its ability to continue as a going concern after reporting a half-year loss, losses for more than three consecutive years and fully eroded net worth at September 30, 2026, according to its auditor’s November 14, 2026 review report.
Know Shristi Infrastructure Development Corporation inside out
Results, valuation, peers and who's buying, in one view.
Why did auditors flag a going-concern uncertainty at Shristi?
Auditors flagged the uncertainty because Shristi reported a loss for the half year ended September 30, 2026, had incurred losses for more than three consecutive years and had fully eroded net worth at that date. R Kothari & Co LLP said those conditions indicate a material uncertainty that may cast significant doubt on Shristi’s ability to continue as a going concern.
The auditor said the use of the going-concern basis in the September 30, 2026 financial statements is critically dependent on management’s view and projected future cash flows. Its conclusion was not modified specifically for this matter, although the limited review report contained a qualified conclusion over interest expense on borrowings.
The same material-uncertainty wording appeared in both the standalone and consolidated reports for the quarter and half year ended September 30, 2026. The consolidated report covers nine entities, comprising eight subsidiaries and one joint venture, including 59.99%-owned Shristi Urban Infrastructure Development Limited.
What does the auditor’s qualification say about Shristi’s results?
The qualification says Shristi did not provide Rs 6.4834 crore of interest expense for the quarter and Rs 12.8964 crore for the half year ended September 30, 2026 on borrowings from Srei Equipment Finance Limited. The auditor said the non-provision and default did not comply with Indian Accounting Standard 23 on borrowing costs and Indian Accounting Standard 109 on financial instruments.
Cumulative unprovided and defaulted interest totalled Rs 137.5222 crore at September 30, 2026. The auditor said the omission understated finance costs and had consequential effects on other financial statement items, a matter linked to the reported erosion of Shristi’s net worth.
For the half year ended September 30, 2026, standalone finance cost would have been Rs 20.404 crore rather than reported Rs 7.5076 crore if the interest had been recognised. Total expenses would have risen from Rs 24.7014 crore to Rs 37.5978 crore, while the reported loss of Rs 8.1203 crore would have widened to Rs 21.0167 crore.
How would recognising the interest change Shristi’s balance sheet?
Recognising the cumulative interest would deepen Shristi’s reported negative other equity and increase current financial liabilities at September 30, 2026. In the standalone accounts, other equity would have been negative Rs 241.6258 crore instead of the reported negative Rs 104.1036 crore, according to the auditor’s calculation.
Standalone other current financial liabilities would have been Rs 169.7048 crore rather than reported Rs 32.1826 crore at September 30, 2026. The Rs 137.5222 crore difference corresponds to the cumulative interest cited in the qualification and affects both period expenses and balance-sheet liabilities.
The consolidated calculations show a comparable effect at September 30, 2026. Consolidated other equity would have been negative Rs 329.8275 crore instead of reported negative Rs 192.3053 crore, while other current financial liabilities would have been Rs 177.4026 crore rather than Rs 39.8804 crore; consolidated half-year loss would have been Rs 24.2237 crore instead of Rs 11.3273 crore.
Got a follow-up? Ask IRIS
Which subsidiary and legal matters remain unresolved for Shristi?
Recoverability of amounts tied to Sarga Udaipur Hotels & Resorts Private Limited remains uncertain because the National Company Law Tribunal, Kolkata Bench admitted the subsidiary to the Corporate Insolvency Resolution Process on April 29, 2022. The auditor said it could not comment on the realisability of Shristi’s Rs 1.95 crore investment and Rs 18.6579 crore interest-free loan receivable from the subsidiary.
The auditor also could not comment on the realisability of a Rs 3 crore investment and a Rs 7.3566 crore loan, including interest, receivable from Shristi Urban Infrastructure Development Limited in connection with Sarga Udaipur Hotels & Resorts Private Limited. It said the consequential effect on financial results for the September 30, 2026 period could not be ascertained.
A separate matter concerns Sarga Hotel Private Limited, an erstwhile material subsidiary. The National Company Law Tribunal approved a resolution plan on January 4, 2024, and the National Company Law Appellate Tribunal upheld it on April 4, 2024; after Shristi filed a civil appeal, the Supreme Court directed mediation on August 19, 2025, and the company continues to carry the balances at book values.
What is the scale of Shristi’s arbitration exposure?
An arbitration tribunal issued a final award in favour of Rishima SA Investments LLC, Mauritius, for Rs 761 crore plus Rs 13.9 crore of interest calculated to April 30, 2019. The filing says the award also contains an alternative payment structure if the principal amount is declared unenforceable by a court or tribunal.
Under that alternative, Shristi would pay Rs 160.2 crore for the investment in Sarga Hotel, Rs 26.21 crore of interest calculated to April 30, 2019 and Rs 18.08 crore in aggregate costs, damages and related items. Pending enforcement proceedings before the Delhi High Court, management said, based on legal opinion obtained by the company, that it does not consider a provision necessary.
The auditor separately noted that certain trade receivable, trade payable and borrowing balances at September 30, 2026 remained subject to confirmation or reconciliation. It said the consequential impact on the reported financial statements was unascertained, adding to the unresolved matters identified in the review.
Conclusion
Shristi’s September 2026 review combines an explicit going-concern warning with a qualified conclusion on Rs 137.5222 crore of cumulative unprovided interest. The auditor’s standalone adjustment would change the reported quarterly profit of Rs 5.0664 crore into a Rs 1.417 crore loss and would further widen negative equity and current liabilities.
The next issues to watch are management’s projected cash flows supporting the going-concern basis, the pending Delhi High Court enforcement proceedings in the Rishima arbitration, and progress in the Supreme Court-directed mediation ordered on August 19, 2025 for the Sarga Hotel matter. The Corporate Insolvency Resolution Process involving Sarga Udaipur Hotels & Resorts Private Limited, admitted on April 29, 2022, also remains unresolved.