










Shristi Q2 profit becomes loss after Srei interest charge
Key highlights
- Shristi’s Rs 6.48 crore unprovided Q2 Srei interest would change standalone profit of Rs 5.07 crore into a Rs 1.42 crore loss.
- Cumulative unprovided and defaulted Srei interest stood at Rs 137.52 crore on 30 September 2026.
- The consolidated qualification narrative calculates a Rs 3.20 crore Q2 loss after the interest adjustment.
- Shristi’s Rs 145 crore NCD interest payment and redemption were both due on 30 November 2026.
powered by IRIS
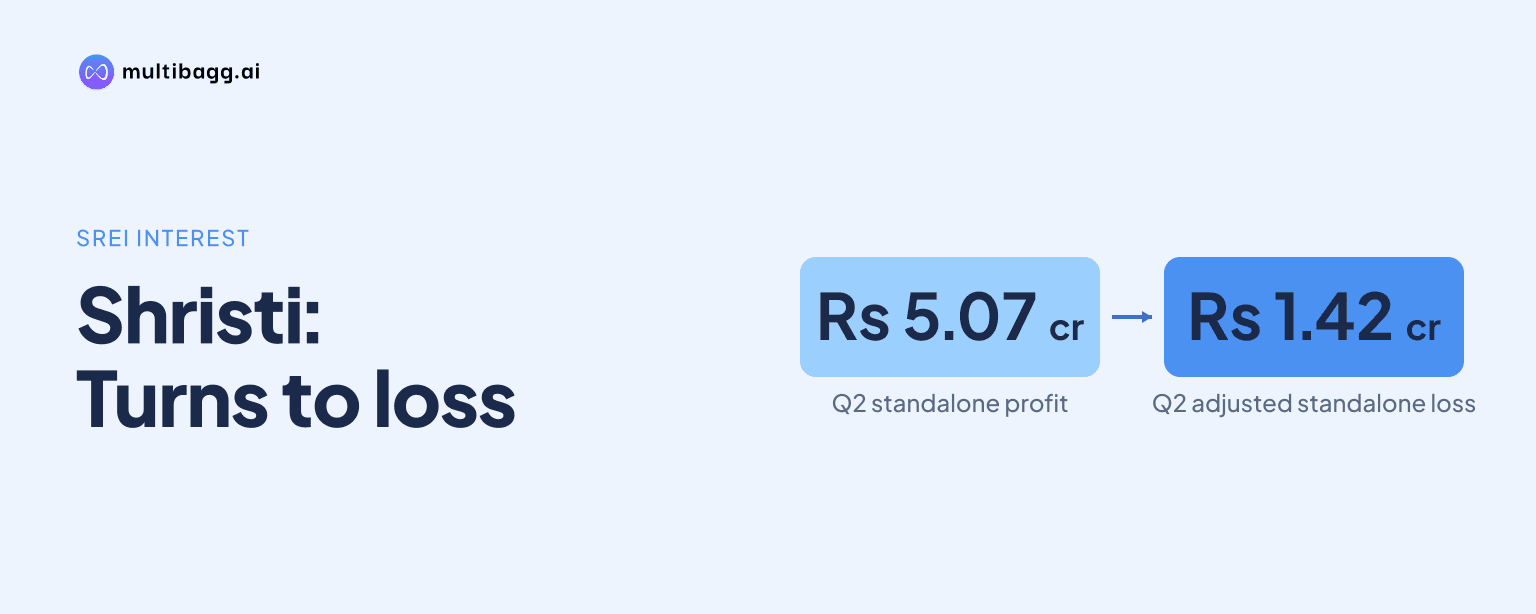
Shristi Infrastructure Development Corporation Limited’s reported standalone profit of Rs 5.07 crore for the quarter ended 30 September 2026 would become a Rs 1.42 crore loss if Rs 6.48 crore of unprovided interest on Srei Equipment Finance Limited borrowings were recognised, according to the auditor’s qualified limited-review opinion.
Know Shristi Infrastructure Development Corporation inside out
Results, valuation, peers and who's buying, in one view.
Why did Shristi receive a qualified opinion on its Q2 results?
Shristi received a qualified opinion because it did not provide for Rs 6.48 crore of interest expense for the quarter ended 30 September 2026 on borrowings from Srei Equipment Finance Limited. The auditor said the interest was in default and that the non-provision was inconsistent with Ind AS 23, Borrowing Costs, read with Ind AS 109, Financial Instruments.
The same qualification identified unprovided interest of Rs 12.90 crore for the half year ended 30 September 2026. Cumulative interest non-provisioning and default on the Srei Equipment Finance Limited borrowing totalled Rs 137.52 crore at that date. The auditor said the omission understated finance cost and had consequential effects on other financial measures.
Shristi’s filing classifies the qualification as repetitive in both the standalone and consolidated statements on the impact of qualifications. Management’s response was that the qualification was self-explanatory. The company’s Note 9 also states that Rs 6.48 crore of term-loan interest had not been provided during the September 2026 quarter.
How would Srei interest change Shristi’s standalone Q2 result?
Recognising the omitted interest would change Shristi’s standalone net profit after tax from Rs 5.07 crore to a loss of Rs 1.42 crore for the quarter ended 30 September 2026, the auditor calculated. Finance cost would increase from the reported Rs 3.82 crore to Rs 10.31 crore, while total expenditure would increase from Rs 3.34 crore to Rs 9.83 crore.
For the half year ended 30 September 2026, standalone loss after tax would widen from Rs 8.12 crore as reported to Rs 21.02 crore after the adjustment. Half-year finance cost would rise from Rs 7.51 crore to Rs 20.40 crore, and total expenditure would rise from Rs 24.70 crore to Rs 37.60 crore.
The adjustment would also turn standalone total comprehensive income from Rs 5.14 crore into a loss of Rs 1.34 crore for the September quarter. The difference is specifically the Rs 6.48 crore interest expense that the auditor says should have been recognised, rather than a revised revenue or operating-income estimate.
What would the interest adjustment mean for Shristi’s consolidated accounts?
The consolidated qualification narrative says recognising the same Rs 6.48 crore interest charge would change Shristi’s consolidated September-quarter result from a profit of Rs 3.28 crore to a loss of Rs 3.20 crore. Consolidated total expenditure would rise from Rs 3.35 crore to Rs 9.83 crore, while total comprehensive income would move from Rs 3.35 crore positive to a Rs 3.13 crore loss.
The filing contains an internal difference in the consolidated presentation. Its summary table reports consolidated net profit of Rs 5.06 crore before adjustment, while the detailed qualification narrative uses Rs 3.28 crore as the reported profit for calculating the adjusted loss. The detailed narrative is the source of the Rs 3.20 crore adjusted-loss calculation.
For the half year ended 30 September 2026, the consolidated qualification narrative calculates a loss after tax of Rs 24.22 crore after interest recognition, compared with a reported loss of Rs 11.33 crore. Finance cost for that half year would increase from Rs 7.51 crore to Rs 20.40 crore, matching the identified Rs 12.90 crore omitted interest.
Got a follow-up? Ask IRIS
How would the qualification affect Shristi’s balance-sheet measures?
On a standalone basis, the cumulative interest adjustment would increase other current financial liabilities at 30 September 2026 from Rs 32.18 crore to Rs 169.70 crore. Other equity would decline from negative Rs 104.10 crore to negative Rs 241.63 crore, according to the auditor’s quantified qualification.
On a consolidated basis, other current financial liabilities would rise from Rs 39.88 crore to Rs 177.40 crore. Consolidated other equity would move from negative Rs 192.31 crore to negative Rs 329.83 crore. These changes reflect the cumulative Rs 137.52 crore of non-provisioning and defaulted interest cited by the auditor through 30 September 2026.
Shristi reported standalone net worth of negative Rs 81.90 crore and consolidated net worth of negative Rs 170.11 crore at 30 September 2026. The company stated that it had incurred losses in each of the previous three years and that its net worth had been fully eroded, while saying debt restructuring would be reflected in future periods.
What other audit uncertainties did Shristi disclose?
The auditor could not comment on the recoverability of Shristi’s Rs 1.95 crore investment and Rs 18.66 crore interest-free loan receivable from Sarga Udaipur Hotels & Resorts Private Limited. Corporate insolvency resolution process, or CIRP, began for that subsidiary under a National Company Law Tribunal, Kolkata Bench, order dated 29 April 2022.
The auditor also could not comment on the recoverability of Shristi’s Rs 3 crore investment and Rs 7.36 crore loan receivable, including interest, from Shristi Urban Infrastructure Development Limited. That entity is the holding company of Sarga Udaipur Hotels & Resorts Private Limited, and the auditor said the resulting effect on the September-quarter and half-year figures could not be ascertained.
These recoverability matters are unquantified, unlike the Srei interest matter, for which the auditor specified a Rs 6.48 crore quarterly effect. Shristi said it had stopped recognising interest income on its loan to Shristi Urban Infrastructure Development Limited from 1 July 2023 as a matter of prudence.
What scheduled financial events should Shristi investors watch?
Shristi’s listed non-convertible debentures, or NCDs, totalled Rs 145 crore at 30 September 2026. They were secured by a first pari passu charge on land in Guwahati, Assam, with a stated requirement to maintain minimum asset cover of 1.5 times during the NCD tenor.
The company disclosed 30 November 2026 as both the next NCD interest-payment date and the NCD redemption date. It said the preceding NCD interest payment had been due and paid on 30 November 2025. Management also said it expected operational profits from the current financial year, citing real-estate activity and traction, while continuing to prepare accounts on a going-concern basis.
Shristi separately reversed Rs 19.31 crore of revenue in the September 2026 quarter after cancellations of units for which revenue had been recognised in the previous year under Ind AS 115. The reversal increased corresponding inventory by Rs 17.10 crore, adding a separate reported movement in quarterly operating figures.
Conclusion
Shristi’s reported September-quarter profit does not include the Rs 6.48 crore Srei Equipment Finance Limited interest expense identified by the auditor. On the auditor’s standalone calculation, that omission changes a Rs 5.07 crore profit into a Rs 1.42 crore loss, while cumulative unprovided interest of Rs 137.52 crore would materially increase reported current financial liabilities.
The next disclosed event is 30 November 2026, when Rs 145 crore of NCDs were due for both interest payment and redemption. Future filings will show whether the debt restructuring is reflected, whether the repeated Srei interest qualification is resolved, and whether the auditor can assess recoverability of Rs 31.96 crore of investments and loans connected to the CIRP-linked subsidiaries.