










Sical Q2 revenue growth coincides with mining margin collapse
Key highlights
- Sical's Q2FY27 consolidated revenue rose 17.4% to Rs 105.5 crore.
- Sical's Q2FY27 consolidated EBITDA margin fell to 9.1% from 20.2%.
- Sical's Mining Logistics EBITDA margin fell to 0.8% from 28.4% in Q2FY26.
- Sical received a five-year Central Coalfields contract valued at about Rs 534.7 crore, including goods and services tax.
powered by IRIS
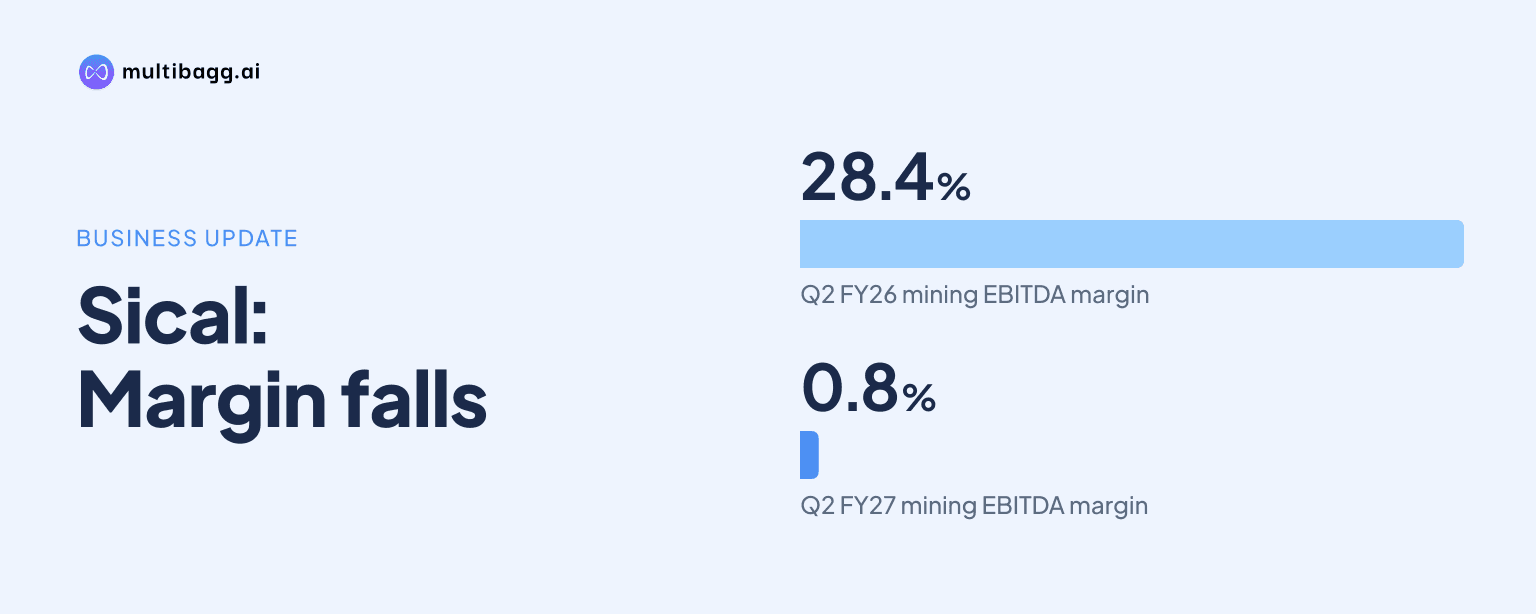
Sical Logistics Limited reported Q2FY27 revenue growth of 17.4% to Rs 105.5 crore, but its consolidated EBITDA margin fell to 9.1% from 20.2% as Mining Logistics margin declined to 0.8% from 28.4%. Management attributed the Mining Logistics margin pressure to prolonged monsoon conditions, heavy rainfall and higher fuel costs.
Know Sical Logistics inside out
Results, valuation, peers and who's buying, in one view.
Why did Sical's Q2FY27 margin fall despite revenue growth?
Sical's consolidated EBITDA fell to Rs 9.6 crore in Q2FY27 from Rs 18.1 crore in Q2FY26, even as revenue rose by Rs 15.7 crore to Rs 105.5 crore. The EBITDA margin consequently declined by 11.1 percentage points to 9.1% in the quarter ended September 30, 2026, meaning higher revenue did not convert into higher operating profit.
Mining Logistics was the principal source of the compression: revenue increased 31.4% to Rs 47.7 crore from Rs 36.3 crore, while EBITDA declined to Rs 40 lakh from Rs 10.3 crore. Its EBITDA margin therefore fell by 27.6 percentage points to 0.8%. Management said prolonged monsoon and heavy rainfall affected operations during Q2FY27, while higher fuel costs also reduced mining-logistics margins.
Mining Logistics was Sical's largest disclosed Q2FY27 segment by revenue, contributing Rs 47.7 crore of the three reported segments' combined Rs 105.5 crore revenue. The company stated that mining-business revenue includes dredging income, so the segment figure does not represent mining logistics alone. EBITDA, or earnings before interest, tax, depreciation and amortisation, excludes other income under the presentation's definition.
Which Sical businesses supported Q2FY27 profitability?
Terminals generated the largest disclosed segment EBITDA in Q2FY27 at Rs 8.2 crore, compared with Rs 7 crore a year earlier, while its margin rose to 21.2% from 20.6%. Revenue increased 13.2% to Rs 38.6 crore from Rs 34.1 crore. Management linked the performance to the development of multimodal logistics facilities after Chennai MMLP operations began in Q1FY27.
Warehousing & 3PL, or third-party logistics, increased EBITDA to Rs 1 crore in Q2FY27 from Rs 80 lakh in Q2FY26, although revenue edged down to Rs 19.2 crore from Rs 19.4 crore. Its margin rose to 5.2% from 3.9%. Management said the business focused on operating discipline and optimising its activity mix, but these gains did not offset the Rs 9.9 crore decline in Mining Logistics EBITDA.
The three segments recorded contrasting outcomes within Sical's Rs 105.5 crore Q2FY27 revenue total. Terminals increased both revenue and margin, while Warehousing & 3PL increased its margin despite a Rs 20 lakh revenue reduction. Mining Logistics added Rs 11.4 crore in revenue but produced Rs 40 lakh of EBITDA, compared with Rs 10.3 crore in the comparable quarter.
Got a follow-up? Ask IRIS
What does Sical's H1FY27 performance show?
Sical's H1FY27 revenue rose 27.1% to Rs 238 crore from Rs 187.4 crore in H1FY26, while EBITDA declined to Rs 34.5 crore from Rs 41 crore. The consolidated financial-performance table reports an EBITDA margin of 14.0%, below 18.7% a year earlier. A separate H1FY27 highlight gives a 14.5% margin, creating a 0.5-percentage-point difference within the release.
Mining Logistics remained the largest disclosed H1FY27 revenue segment at Rs 118.7 crore, up from Rs 80.2 crore, but EBITDA fell to Rs 14.4 crore from Rs 23.4 crore. Its margin declined to 12.1% from 29.2%. The first-half figures show that segment profitability had already fallen year on year before the Q2FY27 monsoon and fuel-cost pressure cited by management.
Terminals recorded H1FY27 revenue of Rs 83 crore and EBITDA of Rs 17.9 crore, compared with Rs 70 crore and Rs 15.9 crore in H1FY26. Its margin eased to 21.6% from 22.8%, unlike its Q2FY27 improvement. Warehousing & 3PL revenue declined to Rs 36.4 crore from Rs 37.1 crore, while EBITDA rose to Rs 2.2 crore from Rs 1.7 crore and margin increased to 6.1% from 4.6%.
What is Sical planning for H2FY27?
Sical received a Letter of Acceptance from Central Coalfields Limited on September 1, 2026, for hiring heavy earth-moving machinery for overburden removal and coal extraction at a diverted 143-hectare patch of lower seams at SDOC Mine in Jharkhand's Dhori Area. Management said the five-year contract is worth about Rs 534.7 crore, including goods and services tax, with contribution dependent on mobilisation and project execution.
Management said it is mobilising the Dhori and Dalli mechanised mine projects in line with contractual timelines and advancing the Porda-Chintapani/Kanchan OCM arrangement. It also plans to increase utilisation at Chennai MMLP and container freight station facilities. Management said the mining operating environment had improved in the second half of FY27 and expects a stronger H2FY27 than H1FY27, with improving profitability.
The Central Coalfields contract adds to Sical's stated order book of more than Rs 4,200 crore, although the release gives no schedule for revenue recognition from the award. The company identified disciplined execution, cost management and higher operating-asset utilisation as priorities after Mining Logistics EBITDA fell to Rs 40 lakh in Q2FY27 despite Rs 47.7 crore of segment revenue.
Conclusion
Sical's Q2FY27 results combined revenue growth with materially lower operating profitability: consolidated revenue increased 17.4% to Rs 105.5 crore, while EBITDA margin fell to 9.1% from 20.2%. The central change was in Mining Logistics, where a 0.8% margin replaced 28.4% a year earlier, while Terminals increased Q2FY27 EBITDA to Rs 8.2 crore and Warehousing & 3PL raised its margin to 5.2%.
The next disclosed test is whether Sical can mobilise and execute the approximately Rs 534.7 crore Central Coalfields contract, the Dhori and Dalli projects, and higher utilisation at Chennai MMLP and container freight station facilities. Management expects H2FY27 to outperform H1FY27, but it said the new contract's contribution depends on mobilisation and execution, while the H1FY27 performance table reported a 14.0% consolidated EBITDA margin.