










Smartworks raises FY27 growth outlook after 39% Q2 revenue gain
Key highlights
- Smartworks reported Q2 FY27 revenue from operations of ₹591 crore, up 39% year-on-year.
- Normalised EBITDA rose 68% year-on-year to ₹117 crore, with margin expanding 340 basis points to 19.8%.
- Normalised PAT increased 136% year-on-year to ₹43 crore in Q2 FY27.
- Smartworks raised FY27 revenue growth guidance to 33-35% from 28-30%.
powered by IRIS
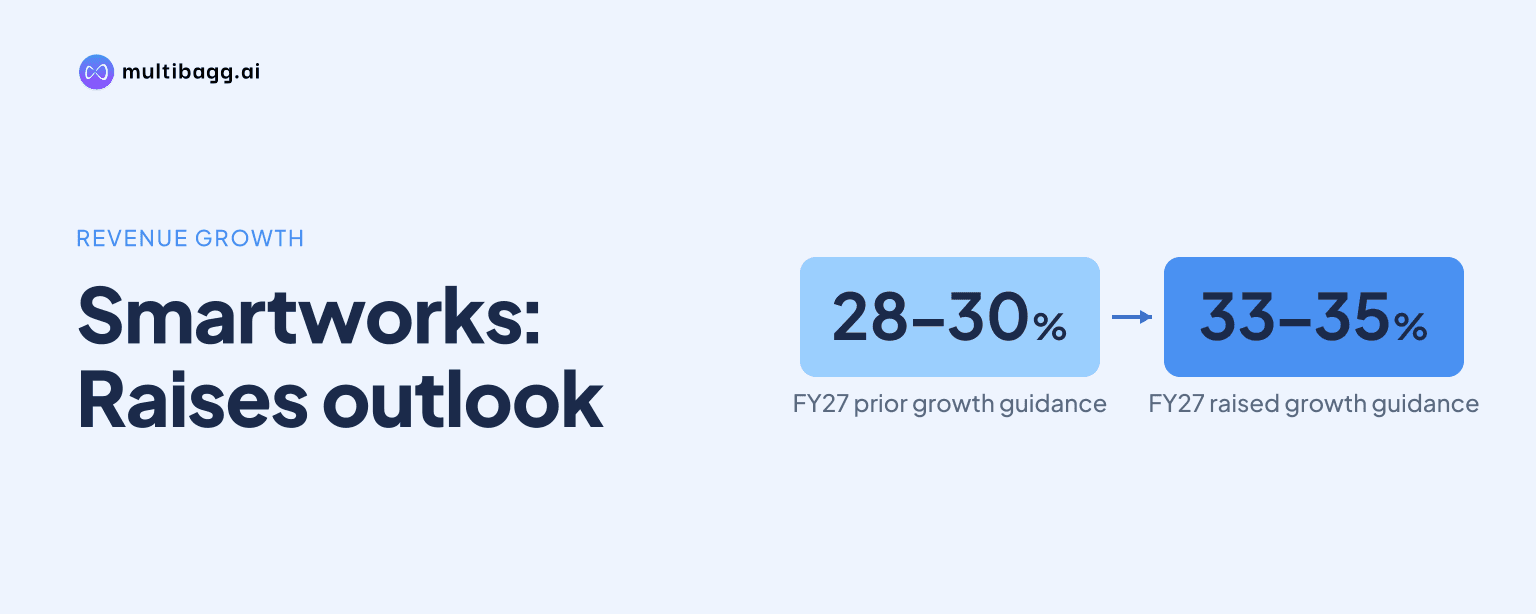
Smartworks Coworking Spaces Limited raised its FY27 revenue growth guidance to 33-35% after reporting Q2 FY27 revenue from operations of ₹591 crore, up 39% year-on-year, supported by continued sequential growth and contracted rental revenue exceeding ₹5,800 crore.
Know Smartworks Coworking Spaces inside out
Results, valuation, peers and who's buying, in one view.
What did Smartworks report for Q2 FY27?
Smartworks reported revenue from operations of ₹591 crore for the quarter ended September 30, 2026, representing 39% year-on-year growth and 8% quarter-on-quarter growth. Management said this was the sixth consecutive quarter of sequential revenue growth since the company’s listing.
Normalised EBITDA increased 68% year-on-year to ₹117 crore. The normalised EBITDA margin was 19.8%, an expansion of 340 basis points from a year earlier. Normalised profit after tax rose 136% year-on-year to ₹43 crore, indicating that profitability grew faster than revenue on this measure.
The company’s consolidated quarterly results also showed reported net profit of ₹26 crore, compared with a loss of ₹3 crore in the corresponding quarter of the prior year. Smartworks separately presented normalised PAT in its earnings commentary, so the two profit figures should not be treated as the same metric.
Why did Smartworks raise its FY27 revenue guidance?
Smartworks raised its FY27 revenue growth guidance to 33-35% from its earlier 28-30% range because management said the company was ahead of the plan outlined in April. The revised outlook followed Q2 revenue growth of 39% year-on-year and 8% sequential growth.
Management said contracted rental revenue had exceeded ₹5,800 crore, providing visibility on future revenue. It also said supply for FY27 was fully secured. The company retained its normalised EBITDA margin guidance of 19-20%, rather than increasing the margin range alongside the upgraded revenue outlook.
Smartworks described client lock-ins as covering rent commitments to landlords by about two times. Management also said there was no asset-liability mismatch through FY2030, an important operating consideration for a managed-office platform that enters lease commitments and serves enterprise clients through longer-duration contracts.
What operating capacity supports the revised outlook?
Smartworks said its platform covered 17.5 million square feet across 71 centres at the end of Q2 FY27. Of this, 10.9 million square feet across 58 centres was operational, while 4.3 million square feet was under fit-out or awaiting handover.
The company plans to launch about 45,000 seats during the second half of FY27 across upcoming mega campuses. Management said profitability is expected to grow alongside revenue as newly opened campuses ramp up, while its stated EBITDA-margin guidance remains unchanged.
Got a follow-up? Ask IRIS
How does the office market backdrop affect Smartworks?
The office-leasing backdrop remains relevant because Smartworks operates enterprise-focused managed office campuses. Management cited CBRE data showing that India leased a record 66.4 million square feet of office space in the first nine months of 2026, an 8% increase from a year earlier.
This wider office-market growth provides context for Smartworks’ expansion, but the company’s results also depend on execution at individual centres, customer demand and the pace at which newly launched campuses reach operating scale. The Q2 call attributed the improved outlook to demand for flexible workspaces, its growing platform and the secured supply pipeline.
Smartworks positions itself as India’s largest managed-office platform and leases bare-shell buildings before operating them as enterprise campuses. Its asset-light model and contracted client arrangements are central to management’s argument that revenue can grow without a comparable increase in funding needs.
What should investors monitor after the Q2 update?
Investors should monitor occupancy ramp-up at new campuses, the timeline for fit-outs and handovers, and whether the company maintains the 19-20% normalised EBITDA-margin guidance as it adds capacity. These factors are relevant because 4.3 million square feet of the current platform is not yet operational.
Cash-flow conversion and progress towards positive free cash flow are also key monitorables identified in the earnings-call commentary. The company has cited a self-funded growth model, including the cash-flow-funded acquisition of Workstudio, but no new financing announcement was disclosed with the Q2 FY27 results.
The revised revenue guidance reflects management’s confidence in contracted demand and secured supply, while the unchanged margin range signals that the company has not assumed further margin expansion in its FY27 outlook. For shareholders, the next evidence points will be execution in the second half, new-seat launches and the financial contribution from campuses as they mature.
Conclusion
Smartworks delivered stronger Q2 FY27 growth across revenue, normalised EBITDA and normalised PAT, and used that performance to raise its full-year revenue growth outlook to 33-35%. Revenue of ₹591 crore, a 19.8% normalised EBITDA margin and contracted rental revenue above ₹5,800 crore underpin management’s stated visibility.
The next items to watch are the planned launch of about 45,000 seats in H2 FY27, the conversion of 4.3 million square feet under fit-out or awaiting handover into operational capacity, and the company’s ability to hold its 19-20% normalised EBITDA-margin guidance.