










South West Pinnacle Exploration Q2 PAT falls 52.4% YoY
Key highlights
- South West Pinnacle Exploration reported Q2 FY27 PAT of Rs 4 crore, down 52.4% year on year.
- SWPE's Q2 FY27 EBITDA margin fell 886 basis points to 14.38% from 23.24%.
- SWPE's H1 FY27 revenue rose 16.3% to Rs 119.4 crore and PAT increased 23.1% to Rs 13.3 crore.
- SWPE reported an H1 FY27 order book of Rs 767.1 crore, including an Oman order exceeding Rs 6 crore.
powered by IRIS
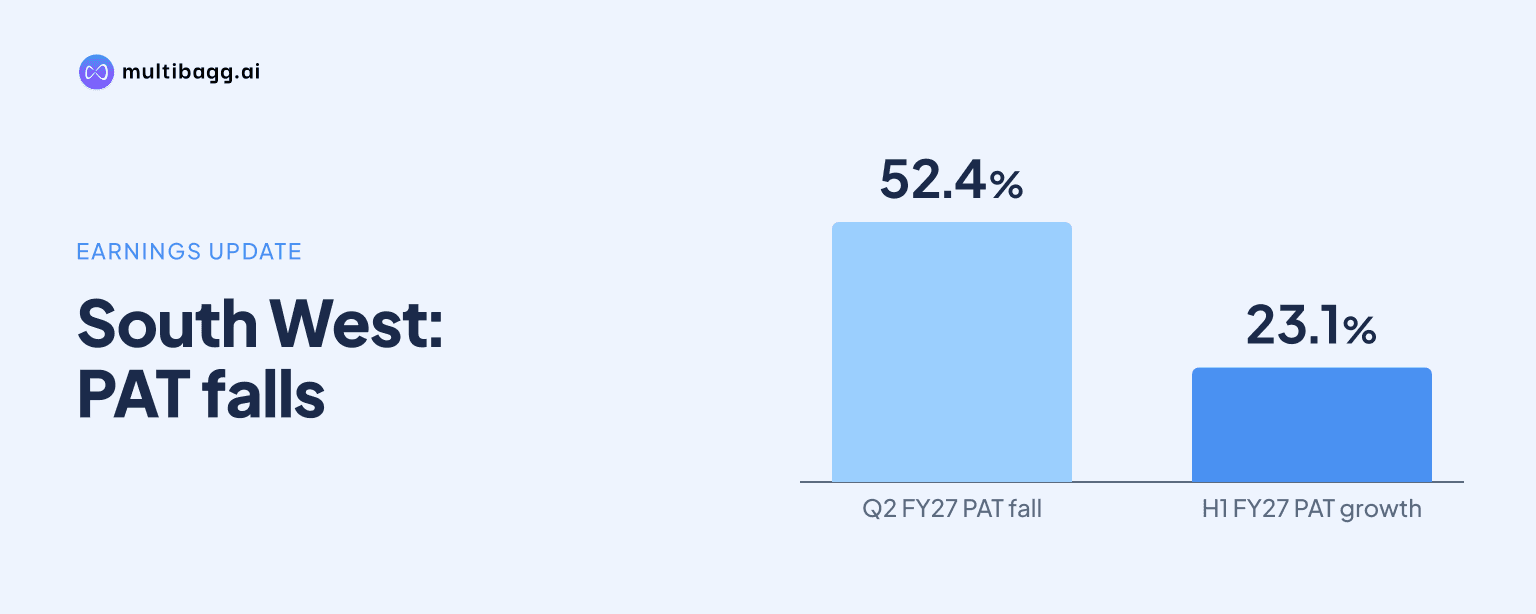
South West Pinnacle Exploration reported profit after tax of Rs 4 crore in the second quarter of fiscal year 2027 (Q2 FY27), down 52.4% year on year, as revenue fell 7.5% and earnings before interest, tax, depreciation and amortisation (EBITDA) margin declined 886 basis points to 14.38%. Management cited monsoon disruption, scheduled maintenance, higher diesel prices and other input costs.
Know South West Pinnacle Exploration inside out
Results, valuation, peers and who's buying, in one view.
Why did SWPE's Q2 FY27 profit fall?
SWPE's Q2 FY27 profit fell because operational revenue declined while total expenses increased. Revenue from operations fell to Rs 57.7 crore from Rs 62.4 crore in Q2 FY26, while total expenses rose 3.1% to Rs 49.4 crore from Rs 47.9 crore. Management said heavy monsoons affected project execution, while scheduled equipment maintenance also constrained quarterly activity.
The revenue-and-cost movement reduced EBITDA by 42.8% to Rs 8.3 crore from Rs 14.5 crore. Management also attributed the decline in profit after tax, or PAT, to higher diesel prices and other input costs. It described the factors as operational and cost-related challenges rather than a change in the underlying business fundamentals or growth prospects.
Below EBITDA, depreciation rose 17.2% to Rs 3.4 crore from Rs 2.9 crore, although finance cost declined 26.1% to Rs 1.7 crore from Rs 2.3 crore. Profit before tax decreased 54.5% to Rs 5 crore from Rs 11 crore. SWPE's share of profit from joint ventures rose to Rs 90 lakh from Rs 80 lakh, but the increase did not offset lower operating profit.
How far did SWPE's Q2 FY27 margins decline?
SWPE's EBITDA margin declined to 14.38% in Q2 FY27 from 23.24% in Q2 FY26, a fall of 886 basis points. PAT margin declined to 6.93% from 13.46%, or 653 basis points. Expenses increased despite the 7.5% fall in revenue, producing a sharper contraction in the operating margin than the change in sales alone.
The lower operating result flowed through to profit before tax, while tax expense fell to Rs 1 crore from Rs 2.6 crore. Diluted earnings per share fell 55.1% to Rs 1.23 from Rs 2.74. Other income was unchanged at Rs 90 lakh in both Q2 FY27 and Q2 FY26, so it did not materially alter the year-on-year earnings comparison.
Despite the decline in PAT, total comprehensive income rose 20.0% to Rs 10.2 crore from Rs 8.5 crore. The difference reflected other comprehensive income of Rs 6.1 crore in Q2 FY27, compared with Rs 10 lakh a year earlier. This comprehensive-income movement was separate from the quarter's Rs 4 crore PAT result.
Got a follow-up? Ask IRIS
Why did SWPE's H1 FY27 revenue and PAT rise?
SWPE's first-half fiscal year 2027 (H1 FY27) revenue and PAT rose because revenue from operations increased 16.3% to Rs 119.4 crore from Rs 102.7 crore, outweighing the weaker Q2 performance. EBITDA increased 14.3% to Rs 23.2 crore from Rs 20.3 crore, while PAT increased 23.1% to Rs 13.3 crore from Rs 10.8 crore.
The half-year operating-margin comparison was narrower than the profit growth suggests. Total expenses increased 16.7% to Rs 96.2 crore, marginally faster than revenue, and EBITDA margin declined 34 basis points to 19.43% from 19.77%. By contrast, PAT margin rose to 11.14% from 10.52% as finance cost fell 19.0% to Rs 3.4 crore and SWPE's joint-venture profit share doubled to Rs 2.2 crore.
H1 FY27 total comprehensive income was Rs 20.1 crore, against Rs 10.8 crore in H1 FY26, including other comprehensive income of Rs 6.8 crore. Diluted earnings per share rose 20.2% to Rs 4.23 from Rs 3.52. The historical financial presentation also shows H1 FY27 EBITDA margin of 19.43% below the 23.99% reported for the full fiscal year 2026, although those periods are not directly comparable because H1 FY27 is a six-month period.
What does SWPE expect in H2 FY27?
SWPE management expects execution capacity, revenue and operating profitability to improve in the second half of FY27 as monsoon-related disruption recedes and new drilling rigs and equipment are deployed in Q3 FY27. Management said funding for the planned capital expenditure has been secured and that the equipment should accelerate mobilisation of pending work orders and improve utilisation.
The outlook is supported by an all-time-high order book of Rs 767.1 crore, which includes an Oman exploration-services order exceeding Rs 6 crore. SWPE reported 20 operations across eight states and zero lost-time injuries. The order book is a measure of pending contracted work, while the presentation does not provide a schedule for converting the full amount into revenue.
On the Jharkhand coal block, SWPE said exploration has been completed and the Geological Report has been approved. The mining plan is at an advanced stage, with submission expected shortly. Management identifies that submission as the next milestone for the long-term asset.
SWPE also cited developments in its Oman operations. The second Oman joint venture finalised a Geological Report after an airborne survey covering more than 1,400 square kilometres identified 12 prospective copper-gold targets; surface geophysical work is expected before targeted drilling. During H1 FY27, CRISIL upgraded the company's rating to BBB+/Stable/A2 from BBB/Positive/A3+.
Conclusion
SWPE's Q2 FY27 result shows a sharp quarterly earnings reversal within an otherwise higher first half. Revenue fell to Rs 57.7 crore as expenses rose to Rs 49.4 crore, reducing EBITDA margin by 886 basis points and PAT by 52.4%. H1 revenue and PAT still increased 16.3% and 23.1%, respectively, but the H1 EBITDA margin was 34 basis points below the prior-year level.
The next items to watch are delivery and deployment of the new rigs and equipment in Q3 FY27, which management expects to improve mobilisation and operating efficiency, and submission of the Jharkhand mining plan. Management's H2 FY27 expectations also depend on improved post-monsoon utilisation and execution against the Rs 767.1 crore order book.