










Spandana Sphoorty Financial Limited new loans reach 96% MFI AUM
Key highlights
- Spandana’s new MFI portfolio reached Rs 4,726 crore in September 2026, representing 96% of standalone MFI AUM.
- The new portfolio was 98.7% current in September 2026, although its delinquent share increased from 0.5% in April to 1.3%.
- PAR 30+ declined to 3.1% in September 2026 from 9.5% a year earlier and 4.4% in June 2026.
- Standalone pan-India X-bucket collection efficiency was 99.6% in September 2026, while Q2FY27 net collection efficiency improved to 97.4% from 96.6% in Q1FY27.
powered by IRIS
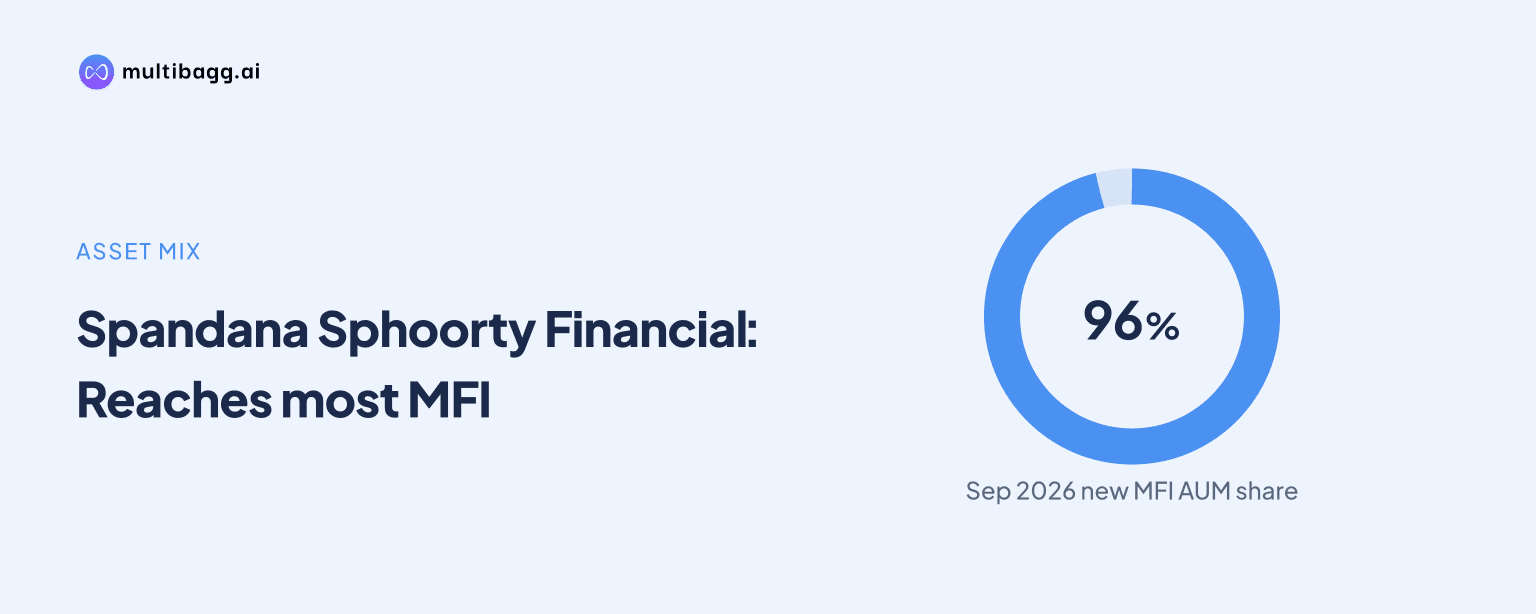
Spandana Sphoorty Financial Limited reported that loans disbursed since 1 April 2025 accounted for 96% of its standalone microfinance institution (MFI) assets under management (AUM) in September 2026. The Rs 4,726 crore new portfolio was 98.7% current, while portfolio at risk (PAR) over 30 days fell to 3.1% from 9.5% a year earlier.
Know Spandana Sphoorty Financial inside out
Results, valuation, peers and who's buying, in one view.
How quickly has Spandana replaced its old MFI portfolio?
Spandana replaced most of its legacy MFI portfolio within a year. The new book rose from Rs 961 crore in September 2025 to Rs 4,726 crore in September 2026, while the old book declined from Rs 2,457 crore to Rs 178 crore. The presentation defines the new portfolio as standalone disbursements made since 1 April 2025 under new credit rules.
New loans represented 96% of the Rs 4,905 crore standalone MFI portfolio in September 2026, compared with 28% of Rs 3,417 crore in September 2025. Total MFI AUM first declined to Rs 3,296 crore in December 2025, then rose in each reported period through September 2026 as new disbursements exceeded the reduction in legacy balances. Overall AUM, a broader measure than standalone MFI AUM, was Rs 5,364 crore in September 2026, up 10% from Rs 4,887 crore in June 2026.
How current are Spandana loans originated since April 2025?
Spandana’s new portfolio was 98.7% current in September 2026 and 1.3% delinquent. This compares with 99.5% current and 0.5% delinquent in April 2026. The reported figures cover standalone loans disbursed since 1 April 2025, providing six months of disclosed repayment-status data for the portfolio originated under the new rules.
The current share declined in every reported month, from 99.4% in May to 98.9% in August and 98.7% in September. Separately, 98.6% of customers were current when their loans were disbursed, while 1.4% were one to 30 days past due (dpd). This origination measure is based on credit-bureau data at the time of disbursement, rather than subsequent repayment performance.
Got a follow-up? Ask IRIS
What do Spandana collection and delinquency data show?
Spandana reported standalone pan-India X-bucket collection efficiency of 99.6% in September 2026, compared with 99.4% in April 2026. The metric reached 99.7% in July and August before easing by 0.1 percentage point in September. Movement from X-bucket to special mention account-0 was 0.5% in September, versus 0.3% in August.
The five listed states recorded X-bucket collection efficiency of 99.6% in Andhra Pradesh, Bihar, Madhya Pradesh and West Bengal, while Odisha recorded 99.8% in September. Consolidated collection efficiency was 99.5% that month. PAR 30+ declined to 3.1% in September 2026 from 9.5% in September 2025 and 4.4% in June 2026; PAR 90+ fell from 5.6% to 2.5% over the year. Net collection efficiency improved to 97.4% in Q2FY27 from 96.6% in Q1FY27.
Are Spandana borrowers carrying fewer lender relationships?
Spandana reported that 76% of customers in the new portfolio had no more than one additional lender relationship at disbursement. Of these borrowers, 40% were unique customers with only Spandana listed and 36% had Spandana plus one other lender. The remaining 24% had Spandana plus two lenders, based on credit-bureau data at the time of disbursement.
Household outstanding loans were below Rs 1 lakh for about 90% of new customers: 64% had less than Rs 50,000 and 26% had Rs 50,000 to Rs 1 lakh. Another 9% had Rs 1 lakh to Rs 1.5 lakh outstanding, and 1% had Rs 1.5 lakh to Rs 2 lakh. In the overall standalone borrower mix, customers with Spandana plus at least three other lenders fell to 3.8% in September 2026 from 12.6% in September 2025, while the unique-borrower share rose from 28.9% to 36.4%.
Conclusion
Spandana’s September 2026 disclosure shows that its standalone MFI portfolio is now principally made up of post-April 2025 lending. The Rs 4,726 crore new book accounted for 96% of MFI AUM and was 98.7% current, while PAR 30+ reduced by 6.4 percentage points from September 2025. The reduction in the old book coincided with lower reported multi-lender overlap and collection efficiency above 99.5% on a standalone pan-India basis.
The next point to watch is the repayment trend as the new loans season further, since their delinquent share rose from 0.5% in April 2026 to 1.3% in September 2026. Management said it is strengthening field collections, using manual and bot calling, and deploying data analytics to improve 90+ recoveries. Recoveries of loans overdue by more than 90 days were Rs 46 crore in Q2FY27, down from Rs 51 crore in Q1FY27.