










Stanley Lifestyles H1 FY27 profit fell 74% as EBITDA margin hit 18%
Key highlights
- Stanley's implied reported H1 FY27 PAT was Rs 3.58 crore, down 74.1% from Rs 13.82 crore in H1 FY26.
- H1 FY27 EBITDA declined 21.5% to Rs 37.11 crore and EBITDA margin fell to 18.0% from 22.1%.
- Q2 FY27 revenue rose 1.6% year on year to Rs 107.06 crore, while EBITDA margin was 18.6%.
- Stanley reported a Rs 60.20 crore order book as of 30 September 2026.
powered by IRIS
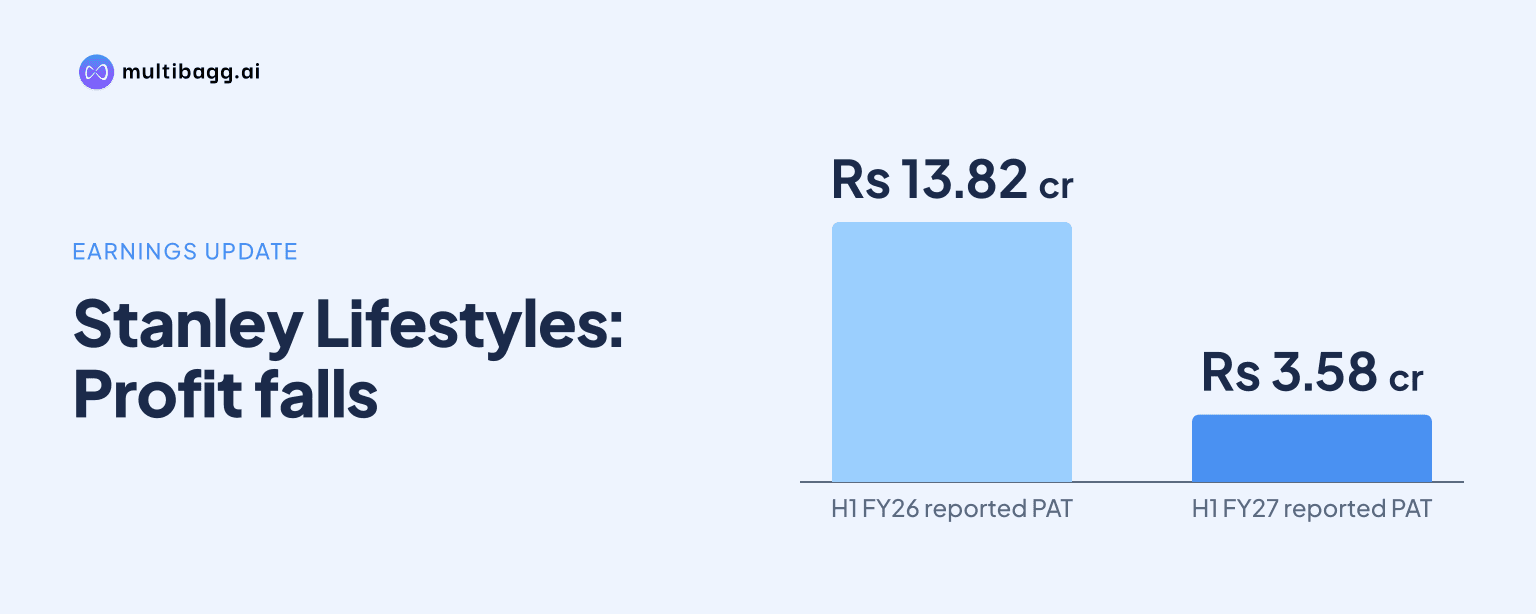
Stanley recorded an implied reported profit after tax of Rs 3.58 crore in H1 FY27, down 74.1% from Rs 13.82 crore in H1 FY26 after an 86 lakh net-of-tax exceptional item, while EBITDA margin declined to 18.0% from 22.1%.
Know Stanley Lifestyles inside out
Results, valuation, peers and who's buying, in one view.
Why did Stanley's H1 FY27 profit decline?
Stanley's H1 FY27 profit decline reflected lower operating earnings and an 86 lakh exceptional item net of tax. Revenue from operations declined 3.6% year on year to Rs 206.41 crore from Rs 214.09 crore, while earnings before interest, tax, depreciation and amortisation (EBITDA) fell 21.5% to Rs 37.11 crore from Rs 47.28 crore.
Profit after tax (PAT), excluding the exceptional item, was Rs 4.44 crore in H1 FY27, compared with Rs 13.82 crore in H1 FY26. That is a 67.9% decline in the presentation's adjusted comparison. Subtracting the disclosed 86 lakh net-of-tax exceptional item gives implied reported PAT of Rs 3.58 crore, which produces the 74.1% year-on-year decline.
The presentation does not identify the specific operating cost, pricing or volume factors behind the EBITDA reduction. Its figures show that the fall in operating profit was materially steeper than the Rs 7.68 crore reduction in revenue: EBITDA declined by Rs 10.17 crore, while gross profit decreased by Rs 5.53 crore to Rs 118.28 crore.
How did Stanley's second quarter compare with the first quarter?
Stanley's Q2 FY27 revenue and EBITDA recovered from Q1 FY27, but profitability remained below Q2 FY26 levels. Revenue rose 7.8% sequentially to Rs 107.06 crore in Q2 FY27 from Rs 99.35 crore in Q1 FY27, exceeding Q2 FY26 revenue of Rs 105.42 crore by 1.6%.
Q2 FY27 EBITDA was Rs 19.89 crore, up 15.5% from Rs 17.22 crore in Q1 FY27. The quarterly EBITDA figure was nevertheless 19.9% below Rs 24.82 crore in Q2 FY26, and its 18.6% margin was 4.9 percentage points below the prior-year quarter's 23.5% margin.
PAT excluding exceptional items increased to Rs 3.29 crore in Q2 FY27 from Rs 1.15 crore in Q1 FY27. The Q2 figure excludes a 36 lakh exceptional item net of tax, while Q1 excludes 50 lakh. Against Q2 FY26 PAT of Rs 6.04 crore, Q2 FY27 adjusted PAT was lower by 45.5%.
The quarterly sequence produced first-half revenue of Rs 206.41 crore, with Q2 accounting for Rs 107.06 crore. The Q2 EBITDA margin rose from 17.3% in Q1 FY27 to 18.6%, but remained below the Q2 FY26 margin.
How far did Stanley's margins fall in H1 FY27?
Stanley's EBITDA margin fell 4.1 percentage points to 18.0% in H1 FY27 from 22.1% in H1 FY26. Gross margin declined by a smaller 0.5 percentage points, to 57.3% from 57.8%, indicating that the difference between the gross-profit movement and EBITDA movement occurred below gross profit, although the presentation does not provide a cost breakdown.
PAT margin declined to 2.2% in H1 FY27 from 6.5% in H1 FY26, based on the presentation's PAT figure excluding the exceptional item. That 4.3-percentage-point decline accompanied adjusted PAT of Rs 4.44 crore on Rs 206.41 crore of revenue, compared with Rs 13.82 crore on Rs 214.09 crore a year earlier.
The Q2 figures show a similar distinction between gross and operating margins. Q2 FY27 gross margin was 57.1%, down 1.2 percentage points from 58.3% in Q2 FY26, while EBITDA margin fell 4.9 percentage points to 18.6%. Q2 PAT margin excluding the 36 lakh exceptional item was 3.1%, against 5.7% in Q2 FY26.
Got a follow-up? Ask IRIS
What does Stanley's sales mix show in Q2 FY27?
Stanley's largest Q2 FY27 product category remained sofa and seating, contributing 59.8% of Rs 107.06 crore in revenue, down from 61.9% of Q2 FY26 revenue. Leather automotive interior increased its share to 15.7% from 11.6%, while kitchen and cabinetry rose to 5.5% from 3.9%.
Case goods represented 12.7% of Q2 FY27 revenue, compared with 14.9% a year earlier, and automotive and others fell to 1.7% from 3.0%. Bed and mattress was broadly stable at 4.6%, versus 4.7% in Q2 FY26. The source provides contribution percentages but does not link product-mix changes to the movement in margin.
Company-owned company-operated stores, or COCO, generated 58.6% of Q2 FY27 revenue, down from 60.3% in Q2 FY26. Business-to-business revenue held at 31.3%, while franchise-owned franchise-operated, or FOFO, stores increased their contribution to 10.1% from 8.4% as total quarterly revenue rose to Rs 107.06 crore.
What operating indicators should readers watch after H1 FY27?
Stanley reported an order book of Rs 60.20 crore as of 30 September 2026, compared with Rs 45.70 crore in March 2025. Management presents this order book as providing near-term revenue visibility, but the presentation does not specify when individual orders will be delivered or recognised as revenue.
The retail network comprised 70 stores, including 46 COCO and 24 FOFO locations. A first international store opened in Colombo, Sri Lanka, in July 2026 through a strategic joint venture with Singer (Sri Lanka) PLC, and a 6,500-square-foot Sofas & More store opened on Ajmer Road in Jaipur in August 2026.
Stanley also reported cash and liquid funds of Rs 174.82 crore and said these funds support store expansion and future growth initiatives. The source's capital-structure page separately lists cash and cash equivalents of Rs 178.50 crore at H1 FY27, alongside total debt of Rs 5.36 crore; the presentation does not reconcile the difference between the two cash measures.
Conclusion
Stanley's first-half figures show that a 3.6% reduction in revenue coincided with a much larger 21.5% fall in EBITDA and a 4.1-percentage-point EBITDA-margin decline. The 86 lakh net-of-tax exceptional item further reduced implied reported H1 FY27 profit to Rs 3.58 crore, while the recovery in Q2 revenue did not bring operating profitability back to the prior-year level.
Readers should watch whether the Rs 60.20 crore order book as of 30 September 2026 converts into revenue, and whether the Q2 EBITDA margin of 18.6% can improve from the H1 level of 18.0%. Management's disclosed expansion initiatives include the Colombo store opened in July 2026 and the Jaipur launch in August 2026, while the presentation gives no quantified revenue or margin target for those initiatives.