










Swastik Pipe auditor cannot quantify omitted borrowing costs
Key highlights
- Swastik Pipe recognised Rs 7.64 crore of bank interest in the half year ended 30 September 2026.
- The auditor could not quantify unbooked NPA-rate interest, penal charges, other bank charges and NBFC interest.
- Swastik Pipe reported a cash loss of Rs 46.35 crore for the half year ended 30 September 2026.
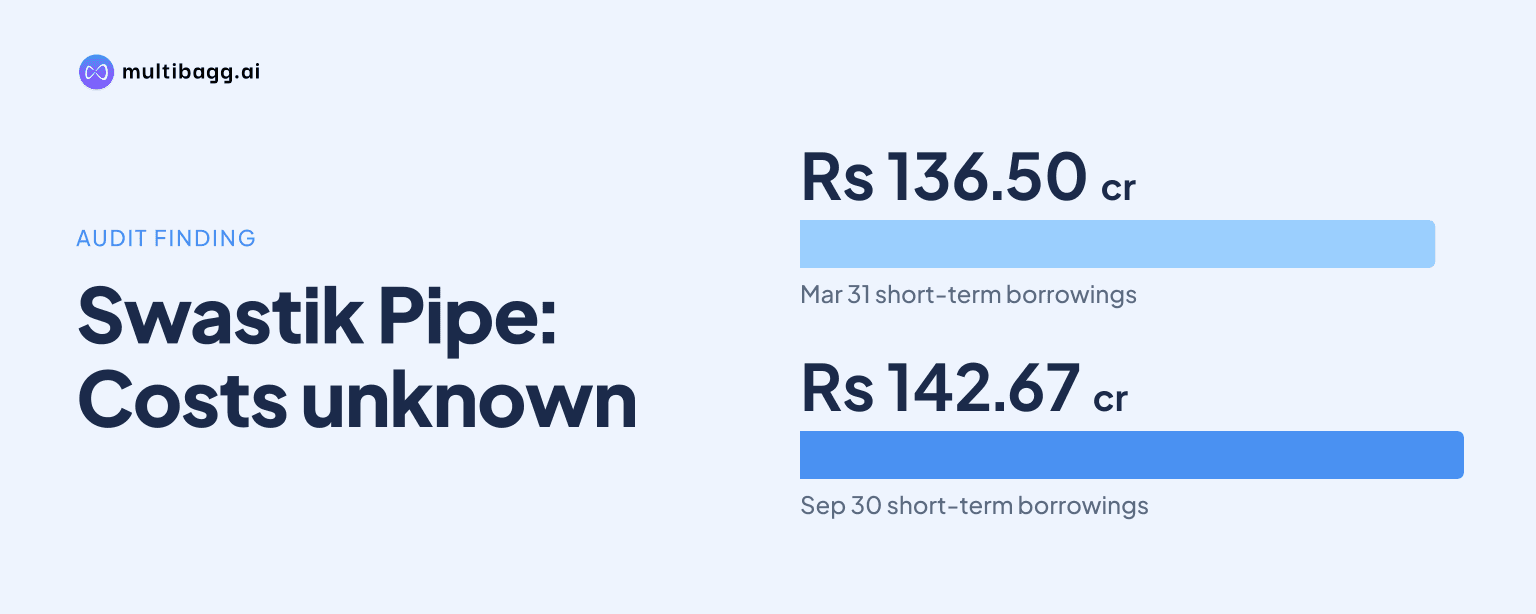
- Short-term borrowings were Rs 136.50 crore at 30 September 2026, versus Rs 142.67 crore at 31 March 2026.
powered by IRIS
Swastik Pipe Limited’s auditor said the September 2026 half-year loss and liabilities cannot be fully measured because Swastik Pipe recognised Rs 7.64 crore of interest on bank borrowings but did not recognise higher NPA rates, penal charges and NBFC borrowing interest. The auditor issued a qualified conclusion on 14 November 2026.
Know Swastik Pipe inside out
Results, valuation, peers and who's buying, in one view.
What did Swastik Pipe’s auditor find?
Swastik Pipe’s statutory auditor identified non-recognition of some borrowing costs as the first basis for its qualified conclusion on the unaudited standalone results for the half year ended 30 September 2026. The company booked bank interest using rates set out in the relevant sanction letters, while the auditor said banks had charged higher card rates applicable after loan accounts were classified as non-performing assets, or NPAs.
The unrecorded amount includes the difference between sanction-letter rates and NPA card rates, penal interest and other bank charges. It also includes interest on outstanding borrowings from non-banking financial companies, or NBFCs, that Swastik Pipe had not recognised during the period under review. The filing does not state a rupee value for the additional bank and NBFC interest.
O. Aggarwal & Co. conducted the limited review under Standard on Review Engagements 2410, which the report says is substantially narrower than an audit. The auditor therefore did not express an audit opinion, but concluded that, except for possible effects of the identified matters, nothing had come to its attention to indicate the 30 September 2026 statement was materially misstated.
How much interest did Swastik Pipe recognise for September 2026?
Swastik Pipe recognised Rs 7.64 crore of interest expense on its outstanding bank borrowings for the six months ended 30 September 2026, calculated using the interest rates specified in sanction letters. That reported amount is the disclosed base figure, not the total interest that could ultimately be payable after lender statements and reconciliations are completed.
The distinction is significant because the auditor did not challenge the Rs 7.64 crore calculation at sanction-letter rates alone. Rather, it said banks had charged higher NPA card rates and other charges that were absent from the statement. The difference cannot be computed from the filing because updated interest statements and reconciliations from the respective lenders were unavailable.
The 14 November 2026 report uses the same limitation for NBFC borrowings. It says Swastik Pipe did not recognise interest expenses on those outstanding borrowings during the period, but it provides neither the NBFC principal outstanding nor the applicable rate. As a result, the disclosed Rs 7.64 crore cannot be compared with a complete borrowing-cost figure for the half year.
Got a follow-up? Ask IRIS
Why are Swastik Pipe’s loss and liabilities unquantified?
Swastik Pipe’s finance costs and corresponding liabilities are understated to the extent of additional interest, penal interest and other charges not recognised, according to the auditor. The same unbooked costs mean the loss for the half year ended 30 September 2026 is understated and net worth is overstated by an amount the auditor could not determine.
The qualification does not establish a final adjusted loss or liability. The auditor expressly said it could not quantify the omitted interest and charges, or determine their consequential impact, without updated lender statements and reconciliations. Any estimate beyond the reported Rs 7.64 crore would therefore go beyond the company’s filing.
The interest issue appears alongside a separate qualification over unconfirmed balances, including receivables, payables, loans and advances, assets, liabilities, NBFC borrowings and bank balances. Swastik Pipe made provisions equal to 50% of disputed debtors and 40% of undisputed debtors outstanding for more than six months, but the auditor said it lacked sufficient evidence to assess recoverability or whether extra provision was needed.
The auditor also noted that no provision had been made for impairment of non-current assets and doubtful or non-recoverable loans and advances. It could not obtain sufficient review evidence on the accuracy, completeness, recoverability and settlement of the affected balances. Consequently, the report says the combined financial effect of the interest matter and balance-confirmation matter remains unascertained.
What do Swastik Pipe’s reported balances and cash losses show?
Swastik Pipe reported total assets and total equity and liabilities of Rs 295.17 crore at 30 September 2026, down from Rs 345.71 crore at 31 March 2026. The decline occurred alongside a reduction in trade receivables and short-term borrowings, while other current liabilities increased, based on the unaudited standalone balance sheet.
Short-term borrowings fell by Rs 6.17 crore between 31 March 2026 and 30 September 2026, whereas other current liabilities rose by Rs 10.25 crore. These are reported balance-sheet movements, but the auditor’s qualification means the borrowing balance and related finance-cost position remain subject to lender confirmations, reconciliation and any consequential adjustment or reclassification.
Swastik Pipe also incurred a cash loss of Rs 46.35 crore in the half year ended 30 September 2026, after a cash loss of Rs 72.35 crore in the financial year ended 31 March 2026. The auditor said bank and financial-institution borrowings had been classified as NPAs due to repayment defaults, creating a material uncertainty that may cast significant doubt on the company’s ability to continue as a going concern.
Conclusion
Swastik Pipe’s reported September 2026 half-year figures include Rs 7.64 crore of bank interest based on sanction-letter rates, but exclude an unquantified amount of higher NPA-rate interest, penal charges, other bank charges and NBFC interest. The auditor’s qualified conclusion means that finance costs, liabilities, the period loss and net worth could change once lenders’ interest statements and reconciliations establish the omitted amounts.
Next, readers should watch whether Swastik Pipe obtains lender reconciliations and records the resulting adjustments, and whether its going-concern plan becomes substantiated. Management relied on ongoing one-time settlement negotiations, anticipated promoter support and core operations backed by the existing order book, but the auditor noted that only two settlements had been concluded, no binding promoter-funding commitment was available, and no cash-flow projections had been provided.