










Tieramet expands copper capacity toward 45,000 MTPA
Key highlights
- Tieramet operates 35,000 MTPA of copper capacity and is expanding toward 45,000 MTPA.
- Tieramet has disclosed Rs 40 crore of capital expenditure across FY27 and FY28.
- Value-added products represented 60% of Tieramet's Q2FY27 sales mix.
- Tieramet reported Q2FY27 revenue of Rs 1,034.6 crore and sales volume of 7,313 metric tonnes.
powered by IRIS
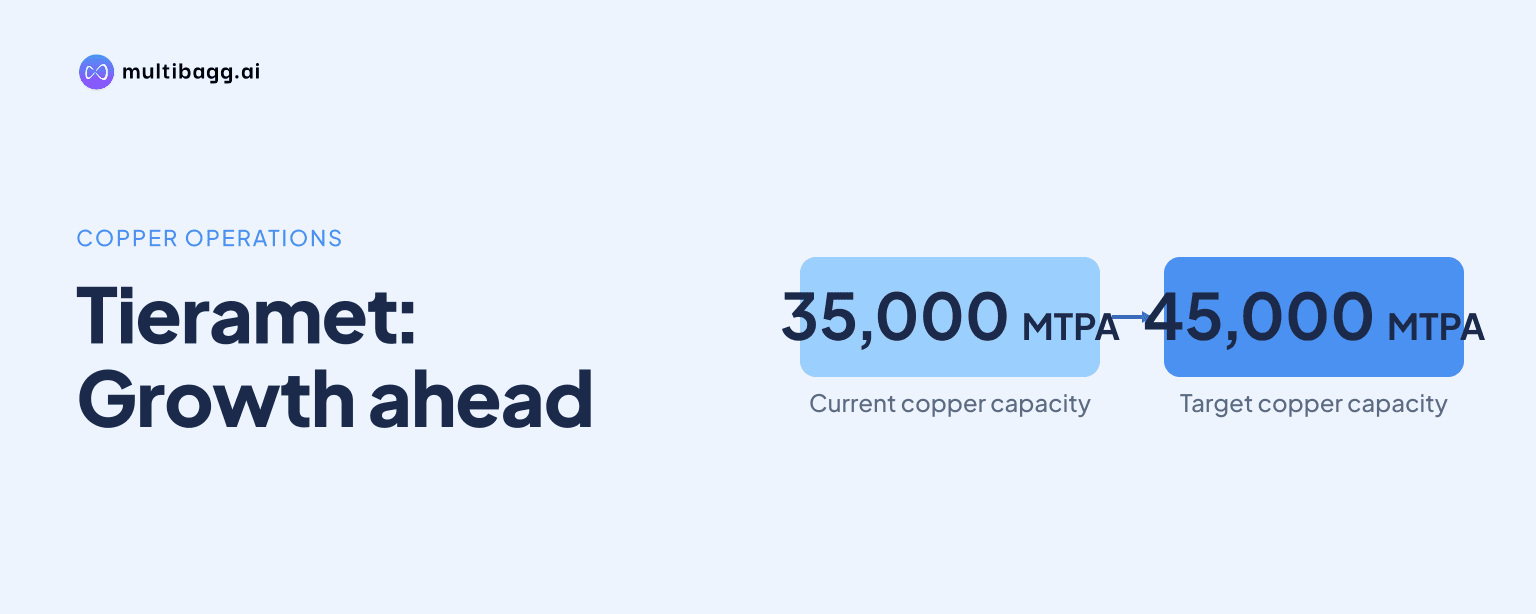
Tieramet Limited is expanding its copper capacity from 35,000 metric tonnes per annum (MTPA) in 2026 toward 45,000 MTPA, supported by Rs 40 crore of capital expenditure in FY27 and FY28. The plan is being pursued from its 60-acre Hyderabad facility, where value-added products accounted for 60% of Q2FY27 sales.
Know Bhagyanagar India inside out
Results, valuation, peers and who's buying, in one view.
How much copper capacity does Tieramet operate?
Tieramet operates 35,000 MTPA of capacity through two ISO-certified manufacturing plants. Its growth timeline states that capacity reached 35,000 MTPA in 2026, when the company introduced silver-plated copper bus bars for data-centre products.
The current scale follows stated capacity milestones of 10,000 MTPA in 1988, 25,000 MTPA in 2017 and 30,000 MTPA in 2025. The 2017 expansion included backward integration into scrap and a 60-acre facility, while the 2026 increase coincided with the addition of silver-plated bus bars.
Tieramet reports annualised capacity utilisation of 72% at its manufacturing infrastructure. The presentation does not disclose a commissioning date, product-wise allocation or output schedule for the additional 10,000 MTPA planned capacity.
What investment supports Tieramet's capacity expansion?
Tieramet has disclosed Rs 40 crore of capital expenditure for FY27 and FY28, alongside the expansion underway toward 45,000 MTPA. The presentation places the programme at its 60-acre integrated manufacturing facility in Hyderabad, which includes two ISO-certified units.
The company describes capacity spending as part of phased investments over three to five years for value-added products. Its listed production capabilities include Outokumpu Upcast technology from Finland, Conform continuous extrusion for high-precision profiles, semi-automatic production systems and a heat-recovery system intended to reduce energy cost.
The planned increase from 35,000 MTPA to 45,000 MTPA is 10,000 MTPA, equivalent to about 29% of current operating capacity. Tieramet has not provided a project-level split of the Rs 40 crore, a capacity commissioning milestone or expected revenue contribution from the added capacity.
How is Tieramet changing its product mix?
Tieramet reported that value-added products represented 60% of sales in Q2FY27, and management's plan calls for a higher share of these offerings. The stated portfolio includes copper bus bars and flats, tapes, paper-insulated copper conductors, foils and sheets, tinned copper bus bars, enamelled copper wires and strips, tubes, and continuously transposed conductors.
Silver-plated copper bus bars, introduced in 2026, are the presentation's identified product for artificial-intelligence data centres. Tieramet states that plating adhesion, uniformity and silver thickness matter because inconsistent plating can create contact-resistance spikes in these applications; it had earlier introduced tin-coated bus bars for switchgear products in 2023.
In Q2FY27, Tieramet reported revenue of Rs 1,034.6 crore, sales volume of 7,313 metric tonnes, and earnings before interest, tax, depreciation and amortisation (EBITDA) per kilogram of Rs 72. It also reported an EBITDA margin of 5.08% and profit after tax margin of 2.95%, although the presentation does not disclose margins by product category or the historical movement in the 60% value-added mix.
Got a follow-up? Ask IRIS
Where does Tieramet source materials and sell products?
Tieramet sources products across more than 30 countries through more than 50 supplier partners and serves more than 500 customers. Its listed sourcing markets include Canada, the United States, Brazil, Argentina, the United Kingdom, Saudi Arabia, China, Singapore and Australia.
Tieramet supplies applications across power transmission, automotive, electrical, engineering, refrigeration, infrastructure and solar. The presentation lists customers including Larsen & Toubro, Amara Raja, Lucas TVS, Blue Star, CG, Sterling & Wilson and Micron, but does not disclose customer-level revenue, contract duration or sales concentration.
The company describes its domestic footprint as being complemented by a growing presence in North America, the Middle East and Asia. Management is targeting East Asia, the Middle East and North America, while identifying electric-vehicle infrastructure, solar photovoltaic systems and high-efficiency motors as emerging sectors; these are stated plans rather than reported revenue outcomes.
What is Tieramet targeting by FY30?
Tieramet is targeting Rs 5,000 crore of revenue by FY30, supported by capacity expansion to 45,000 MTPA and a rising value-added-product mix. Management links the target to digitisation, recycled-feedstock usage, technology and efficiency initiatives, research and development, geographic expansion and original equipment manufacturer partnerships.
The FY30 target and Q2FY27 revenue of Rs 1,034.6 crore cover different periods and are not directly comparable as annual results. Tieramet does not provide a year-by-year revenue bridge, copper-price assumptions, volume-growth path, project commissioning schedule or profitability target for the FY30 objective.
Tieramet reported return on equity of 29.68% and return on capital employed of 20.95% in Q2FY27. Its operational plan includes end-to-end digitisation of production, quality control and supply chain, as well as scaling extended producer responsibility initiatives and recycled feedstock, without quantified effects on yield, cost or working capital.
Conclusion
Tieramet's disclosed expansion would add 10,000 MTPA to its 35,000-MTPA operating capacity, with Rs 40 crore of FY27 and FY28 capital expenditure. The plan combines its Hyderabad manufacturing base, a 60% Q2FY27 value-added sales mix, newer silver-plated bus bars and sourcing across more than 30 countries.
The next disclosed markers are progress under the three-to-five-year value-added-product investment plan and movement toward the Rs 5,000-crore FY30 revenue target. Investors can also watch for details on the commissioning and product allocation of 45,000 MTPA capacity, alongside management's plans for East Asia, the Middle East, North America and recycled-feedstock usage.