










Uniparts targets 24% FY27 revenue growth as fabrication scales
Key highlights
- Uniparts targets FY27 revenue growth of 24% after 32% year-on-year growth in the first half.
- Uniparts said construction revenue grew 49% year-on-year while the industry grew in the mid-teens.
- Fabrication represented about 12% to 15% of new business wins and could reach a high-single-digit revenue share in 18 to 24 months.
- Working-capital days were 137 at the end of the September quarter versus 136 at the end of March.
powered by IRIS
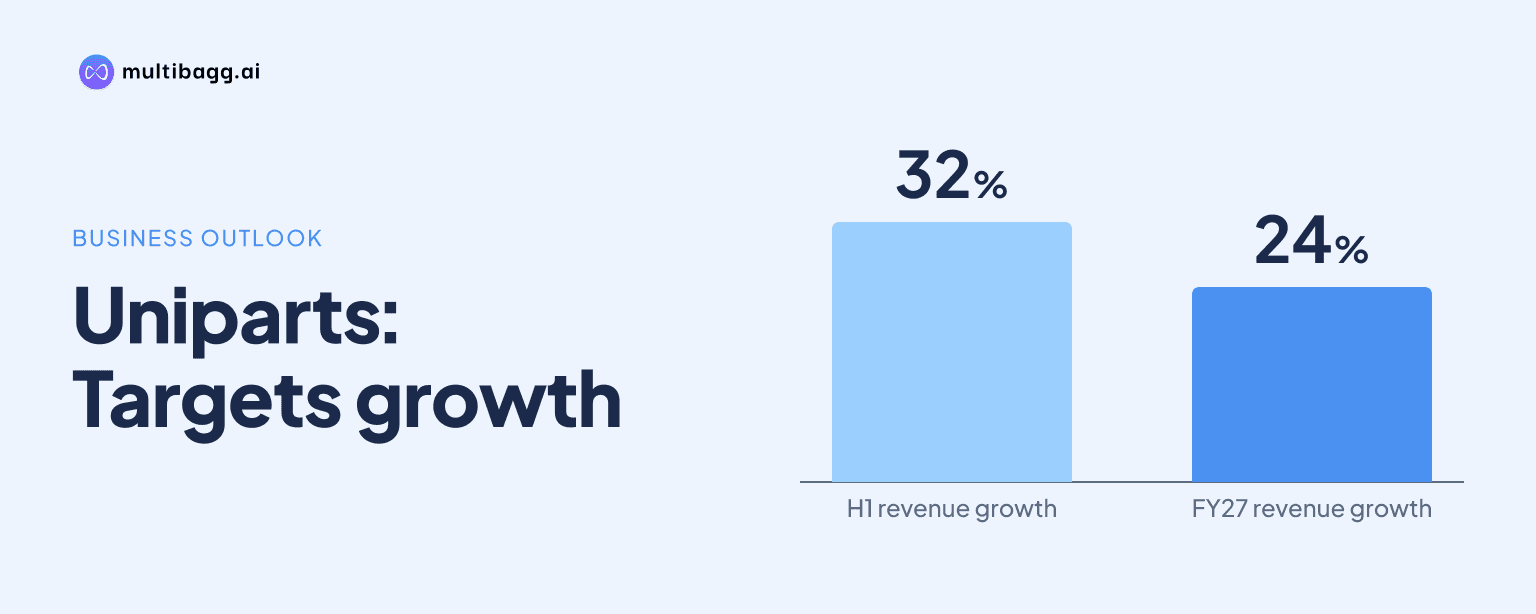
Uniparts India Limited expects FY27 revenue to rise 24% from FY26 after 32% year-on-year growth in the first half of FY27, while management expects fabrication to reach a high-single-digit share of sales, potentially 10%, within 18 to 24 months.
Know Uniparts India inside out
Results, valuation, peers and who's buying, in one view.
What is Uniparts’ FY27 revenue growth target?
Uniparts expects FY27 revenue to be 24% above FY26. Management said first-half FY27 revenue grew 32% year-on-year, but second-half percentage growth should be lower because revenue had already increased 32% year-on-year in the second half of FY26 as construction demand started recovering.
Management said absolute revenue should continue to rise in the second half despite the lower growth rate against a higher base. It expects Q3 FY27, which it described as seasonally its lowest quarter, to be broadly in line with Q1 FY27 because of the Indian agricultural cycle, overseas snow conditions and the Western holiday season.
Uniparts does not provide earnings before interest, tax, depreciation and amortisation, or EBITDA, guidance. Management said Q2 FY27 EBITDA margin was 23.4% despite raw-material and West Asia inflation, while warehousing sales represented 53% of sales against 56% in Q1; it reiterated its expectation of delivering a 20% margin over a cycle.
Which segments are expected to drive Uniparts’ growth?
Uniparts identifies construction equipment, small agriculture, large agriculture and fabrication as its growth drivers. Management said construction revenue rose 49% year-on-year while the industry expanded in the mid-teens, supported by market recovery and new business awards; 70% of its new business awards are in construction or large agriculture.
In the United States, management cited data centres, artificial-intelligence infrastructure and smart manufacturing as construction-demand drivers under multiyear customer contracts. In Europe, it pointed to infrastructure spending, energy transition and recovering non-commercial construction, while supplies from Mexico are also expected to support the construction segment.
Small agriculture is showing early recovery signs as order books improve, according to management. India performed well in the first half of FY27, although management expects second-half Indian growth to be lower; large agriculture remains in a trough after a 17% industry decline, but Uniparts has continued to win business in Europe and the United States.
Management said about 35% of current new-business awards are in large agriculture, following work begun 2 to 3 years ago. It also said its United States patent for a lower-link hook came through in August, while validation and field testing in large agriculture can take 18 to 36 months because the three-point linkage system supports heavier equipment.
How large could fabrication become for Uniparts?
Uniparts expects fabrication to become a meaningful third platform within 18 to 24 months, with a high-single-digit revenue share and potentially 10%. Management described the target as an organic expansion based on its Ludhiana facility, established 2 to 3 years ago for small and medium-sized fabricated products.
Fabrication currently accounts for only a small percentage of revenue, but it represents about 12% to 15% of new business wins. Management said it is working with original equipment manufacturers, or OEMs, to raise fabricated-product supplies and is expanding capabilities at the Ludhiana facility to meet those requirements.
The company did not disclose current fabrication revenue, plant capacity or a specific FY28 revenue target. Its stated plan depends on converting new business wins and customer discussions into supply programmes over the next 18 to 24 months, rather than on an acquisition being completed.
Got a follow-up? Ask IRIS
Will acquisitions change Uniparts’ fabrication and growth plans?
Uniparts says acquisitions are its first priority for cash deployment, but they are not required for its current fabrication plan. Management said it is evaluating more than half a dozen opportunities after walking away from 2 recent opportunities, and it will not make an acquisition solely for the sake of completing a deal.
Management identified hydraulics, power takeoff, or PTO, and large fabrication as its three acquisition platforms. It said hydraulic and PTO opportunities can be global because the technology is more prevalent outside India, whereas a large-fabrication acquisition would be predominantly India-focused on economic grounds.
A large-fabrication acquisition could cover products such as cement mixers or large buckets, management said, and would be a top-up to the organic Ludhiana platform. The company said an acquisition must be strategic, add value for customers and stakeholders, and must not be a deep-turnaround situation.
Capital expenditure is currently about 4% of revenue, reflecting organic growth requirements. If Uniparts does not complete an acquisition, management said the board will decide the appropriate use of cash after considering both organic and inorganic needs.
What could affect Uniparts’ delivery of the FY27 plan?
Uniparts said industry cycles, new business wins and customer relationships are the main factors affecting operations. Management described the usual construction-equipment cycle as 4 to 6 years and said it sees visibility for the current recovery to continue for the next 2 to 3 years.
Management said it is not seeing slower order books or changes in delivery schedules linked to questions about United States artificial-intelligence infrastructure spending. Its view is that data-centre and manufacturing projects involve multiyear contracts with capital committed upfront, meaning delays may occur but cancellations are not typical.
Working-capital days were 137 at the end of the September quarter, compared with 136 at the end of March. Management expects 136 to 140 days in FY27, reflecting an export-led delivery model with about 2 months of inventory at sea and 2 months in warehouses.
Receivables rose because revenue increased and because 2 United States OEM customers had payment delays, management said. One issue had been streamlined and the other was expected to be resolved by November; management said these were technical customer-side issues rather than payment disputes.
Conclusion
Uniparts’ 24% FY27 revenue-growth outlook rests on a construction recovery, early improvement in small agriculture, continued new-business wins in large agriculture and an organic fabrication expansion. Construction grew 49% year-on-year while the industry grew in the mid-teens, and fabrication represented 12% to 15% of new business wins despite remaining a small share of current revenue.
The next milestones are Q3 FY27 revenue, expected to be broadly in line with Q1, and second-half revenue, which management expects to exceed the first half in absolute terms. Investors can also watch whether fabrication advances toward a high-single-digit revenue share within 18 to 24 months, whether the remaining customer payment issue is resolved by November, and whether any of the more than half a dozen acquisition opportunities becomes a signed transaction.