










Viaz Tyres H1 FY27 PAT rises 207.16% to Rs 6.1985 crore
Key highlights
- Viaz Tyres reported H1 FY27 consolidated revenue of Rs 70.7186 crore, up 65.99% year on year.
- Viaz Tyres’ H1 FY27 Group PAT reached Rs 6.1985 crore, up 207.16% from Rs 2.0180 crore.
- Viaz Tyres’ EBITDA margin expanded 252 basis points to 12.43% in H1 FY27.
- Viaz Tyres’ CWIP rose 98.81% to Rs 23.1273 crore at September 30, 2026.
powered by IRIS
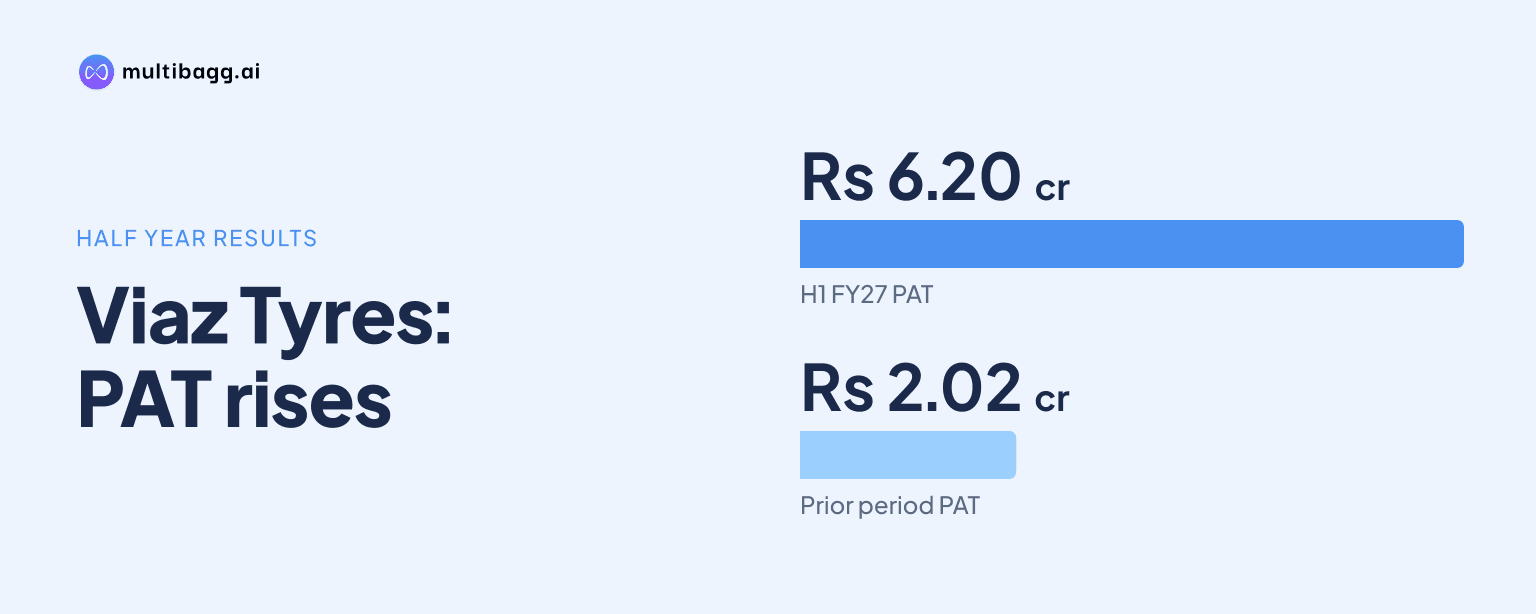
Viaz Tyres Limited reported H1 FY27 consolidated profit attributable to the Group of Rs 6.1985 crore, up 207.16% year on year and above FY26’s full-year Rs 5.2734 crore, as revenue rose 65.99% to Rs 70.7186 crore and operating margins expanded. The half year ended September 30, 2026.
Know Viaz Tyres inside out
Results, valuation, peers and who's buying, in one view.
How did Viaz Tyres perform in H1 FY27?
Viaz Tyres delivered Rs 70.7186 crore of consolidated revenue from operations in H1 FY27, compared with Rs 42.6032 crore in H1 FY26, while earnings before interest, tax, depreciation and amortisation, or EBITDA, rose to Rs 8.7896 crore from Rs 4.2220 crore. Revenue grew 65.99%, but EBITDA increased 108.19%, meaning operating earnings rose faster than sales over the corresponding six-month period.
Profit before tax increased 183.63% to Rs 7.7227 crore from Rs 2.7228 crore, and profit after tax, or PAT, rose 207.16% to Rs 6.1985 crore from Rs 2.0180 crore. Basic earnings per share increased to Rs 4.14 in H1 FY27 from Rs 1.65 in H1 FY26, a 150.91% increase. Viaz Tyres described the figures as audited consolidated results for the half year ended September 30, 2026.
Why did Viaz Tyres’ profit outpace revenue growth?
Viaz Tyres’ disclosed operating profitability improved alongside the revenue increase: EBITDA margin reached 12.43% in H1 FY27, compared with 9.91% in H1 FY26. That was an expansion of 252 basis points, where one basis point equals one-hundredth of a percentage point. PAT margin rose by 403 basis points to 8.77% from 4.74% during the same comparison.
The disclosed figures show that Rs 70.7186 crore of revenue generated Rs 8.7896 crore of EBITDA and Rs 6.1985 crore of PAT in H1 FY27, versus Rs 42.6032 crore, Rs 4.2220 crore and Rs 2.0180 crore respectively a year earlier. Management attributed the outcome to scaling the business and improved operating profitability. Managing Director Janak Patel also said the company was moving forward after operational challenges experienced in the previous financial year, without specifying those challenges in the release.
The margin change accounts for the difference between sales and profit growth. Revenue added Rs 28.1154 crore year on year, while EBITDA added Rs 4.5676 crore and PAT added Rs 4.1805 crore. The release does not provide product-level volumes, selling prices, raw-material costs, financing costs or a segment-wise profit bridge, so it does not identify individual cost or product-mix factors behind the EBITDA-margin expansion.
Got a follow-up? Ask IRIS
How does H1 FY27 compare with FY26 and H1 FY26?
Viaz Tyres’ H1 FY27 PAT of Rs 6.1985 crore exceeded its entire FY26 consolidated PAT of Rs 5.2734 crore by Rs 0.9251 crore. This comparison differs from the year-on-year H1 measure because it places six months of FY27 against the prior 12 months of FY26. It nevertheless shows that first-half FY27 profit was higher than the prior full-year amount disclosed by the company.
Against H1 FY26, PAT rose from Rs 2.0180 crore to Rs 6.1985 crore, equal to 3.0716 times the earlier result and the reported 207.16% increase. EBITDA rose from Rs 4.2220 crore to Rs 8.7896 crore, or 2.0819 times, while revenue rose from Rs 42.6032 crore to Rs 70.7186 crore, or 1.6599 times. The relative growth rates are consistent with the movement in EBITDA margin from 9.91% to 12.43% and PAT margin from 4.74% to 8.77%.
The comparison has limits because the release supplies FY26 consolidated PAT of Rs 5.2734 crore, but not FY26 revenue, EBITDA, capital expenditure, cash flow or full-year balance-sheet figures. It also provides H1 FY27 audited consolidated results rather than a FY27 forecast. The Rs 6.1985 crore first-half PAT therefore does not establish a full-year outcome.
What is Viaz Tyres investing in and planning next?
Viaz Tyres had capital work in progress, or CWIP, of Rs 23.1273 crore at September 30, 2026, up 98.81% from Rs 11.6326 crore at March 31, 2026. CWIP increased by Rs 11.4947 crore in six months, reflecting investment in projects still under development rather than assets stated as completed and operating. The company manufactures inner tubes and tyres and said the investment was directed towards manufacturing infrastructure.
Total consolidated assets were Rs 114.8136 crore at September 30, 2026, a 30.47% increase, while shareholders’ funds including minority interest stood at Rs 78.5229 crore. During H1 FY27, Viaz Tyres converted 20,00,000 convertible warrants into equity shares for promoter and promoter-group allottees after receiving balance consideration of Rs 10.50 crore. The release does not state the resulting share capital, total post-conversion share count or issue price per converted warrant.
Director Rajesh Patel said FY27 priorities were advancing ongoing projects, improving operational efficiencies, strengthening working-capital management and building a scalable manufacturing platform. Viaz Tyres also initiated the shareholder approval process for a proposed migration from NSE EMERGE to the NSE Main Board. The proposed move remains subject to shareholder and exchange approvals and was not presented as completed.
Conclusion
Viaz Tyres combined a 12.43% EBITDA margin and an 8.77% PAT margin in H1 FY27 with a substantial rise in manufacturing investment. The financial outcome showed that EBITDA and PAT increased faster than revenue during the half year, while the Rs 6.1985 crore PAT also surpassed the Rs 5.2734 crore consolidated PAT disclosed for all of FY26.
The next disclosed matters to watch are progress in converting Rs 23.1273 crore of CWIP into manufacturing capacity, management’s work on operating efficiency and working capital, and the outcome of NSE Main Board migration approvals. The release provides no production timetable, capacity target or FY27 earnings target, leaving the timing and financial return from ongoing projects unresolved.