










Viaz targets Rs 350 crore FY29 revenue through tyre expansion
Key highlights
- Viaz targets Rs 350 crore of FY29 revenue, compared with a stated Rs 108 crore base.
- Viaz plans Rs 50-55 crore of capital expenditure and targets PAT margins of 8-10%, from 6%.
- The new Mehsana tyre facility is expected to start in H1FY27 with 1.60 million units of annual capacity.
- Viaz reported half-year consolidated revenue of Rs 70.72 crore and PAT of more than Rs 6.19 crore.
powered by IRIS
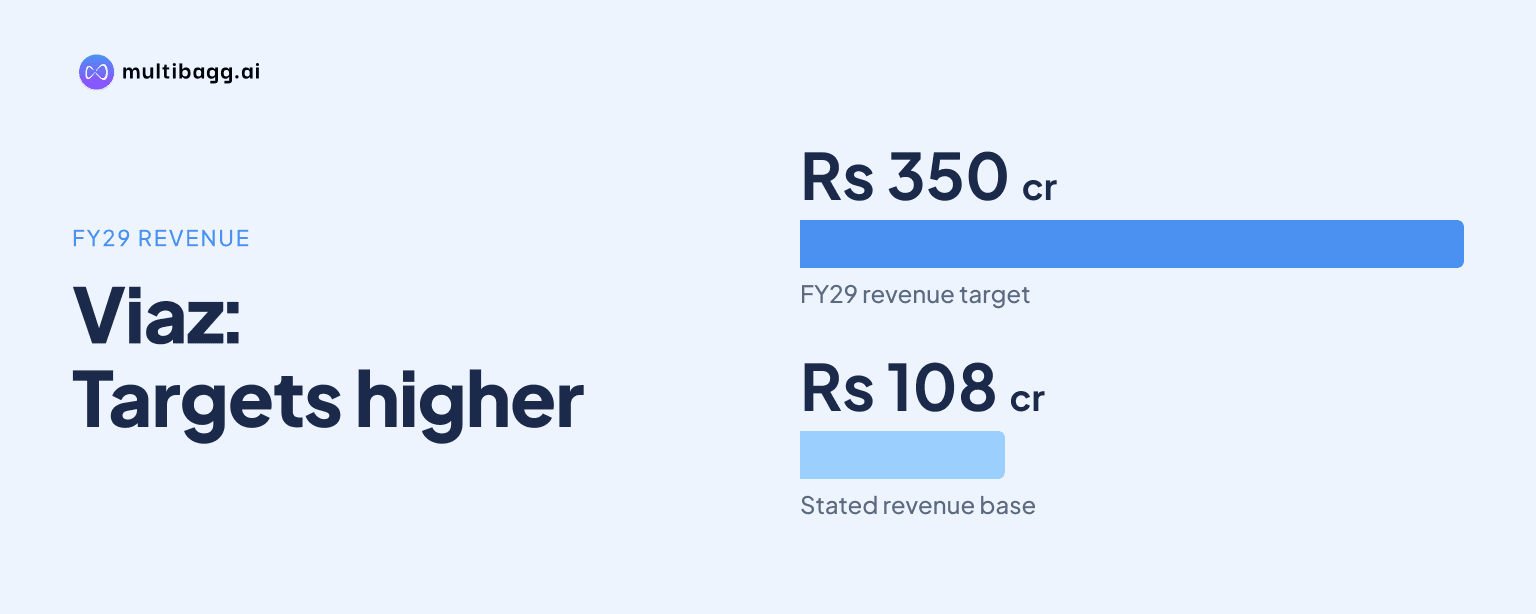
Viaz Tyres targets Rs 350 crore of revenue in FY29, compared with the Rs 108 crore base stated in its presentation, through Rs 50-55 crore of planned tyre-manufacturing capital expenditure. Management links the plan to a new facility covering four tyre categories and targets profit after tax margins of 8-10%, versus 6%.
Know Viaz Tyres inside out
Results, valuation, peers and who's buying, in one view.
What revenue target has Viaz set for FY29?
Viaz has set a Rs 350 crore revenue target for FY29, against the Rs 108 crore current revenue base cited in its presentation. Management describes the intended increase as more than three times and links it to moving beyond butyl inner tubes into tyre manufacturing, where it says realisation per unit is higher.
The presentation places planned capital expenditure at Rs 50-55 crore and identifies tyre manufacturing as the main expansion mechanism. Management also targets profit after tax, or PAT, margins of 8-10%, compared with 6% in the stated base, but does not provide annual revenue, spending or margin milestones between the current base and FY29.
When will Viaz's new tyre facility begin operations?
Viaz says its new Mehsana tyre plant is expected to be operational in H1FY27 and will cover 1.50 lakh square feet. The facility is intended to produce tyres for two-wheelers, three-wheelers, light commercial vehicles, and agricultural and farm equipment, creating four new product categories for the company.
The new facility has stated annual capacity of 1.60 million units, expected utilisation marked as 50%E, and planned asset turnover of 7 times. In comparison, Viaz's existing facility has 7.60 million units of annual capacity, utilisation of 90-95%, and asset turnover of 5.8 times; the two capacities cover different products and are therefore not directly comparable.
The existing operation has 6.00 million more units of stated annual capacity than the new plant, but it is focused on tubes and ancillary products rather than tyres. The presentation does not define the “E” attached to the new facility's 50% utilisation figure or disclose the asset values underlying either asset-turnover measure.
What tyre products and demand segments will Viaz target?
Viaz will target two-wheeler, three-wheeler, light commercial vehicle, agricultural and farm-equipment tyres at the new facility. Its way-forward presentation also refers to diversification into four-wheelers, all-terrain vehicles and commercial vehicles, indicating a stated broader end-market focus than the four categories in the capacity table.
The expansion case relies partly on replacement demand. Viaz says more than 70% of Indian tyre demand comes from the replacement market, while butyl tubes in two- and three-wheelers are replaced two to three times more frequently than tyres because of punctures and wear. These are market characteristics cited in the presentation rather than company sales forecasts.
Viaz says tyres offer multiple times higher realisation per unit than tubes and therefore could raise revenue scale. The presentation also says the new plant opens four tyre categories at once, while the company's existing tube business continues to serve replacement-led demand through its distributor network.
Got a follow-up? Ask IRIS
How does the tyre expansion fit Viaz's existing business?
Viaz operates a dual-vertical model that combines in-house manufacturing with asset-light tyre distribution. Its existing manufacturing business produces butyl rubber inner tubes, while its sales model uses a pan-regional distributor network; management says its dealer and original equipment manufacturer, or OEM, relationships can reduce tyre go-to-market risk.
The existing Mehsana District, Gujarat facility covers 95,000 square feet and includes a 0.85 megawatt captive solar plant. A company-history slide says Viaz acquired 1.40 lakh square feet of land for a new manufacturing plant in 2024, whereas the growth slide describes the new plant as 1.50 lakh square feet; the presentation does not reconcile the 10,000-square-foot difference.
Viaz presents its expanded offering as a single brand spanning tyres, butyl tubes, lubricants, repair kits and air pumps. Exports account for 15-20% of total product sales, according to the presentation, with Libya, Oman, the USA, Dubai, Turkey, Romania, Sudan, Egypt, Brazil and Colombia listed as export markets.
Which financial metrics frame Viaz's expansion plan?
Viaz reported consolidated half-year revenue of Rs 70.72 crore and PAT attributable to the group of more than Rs 6.19 crore in management commentary. Chairman and Managing Director Janakkumar Patel called this the company's strongest reported half-year performance and said PAT rose more than threefold from the corresponding prior-year half, without providing the prior-period PAT amount.
Management also said earnings before interest, tax, depreciation and amortisation, or EBITDA, more than doubled year on year during that half-year period. Those reported results are separate from the Rs 108 crore revenue base used for the FY29 target because the presentation does not identify whether that target base is consolidated, annualised, or associated with a specified financial year.
The plan depends on converting Rs 50-55 crore of planned expenditure into tyre output and sales while the existing tube facility operates at its stated 90-95% utilisation range. Management cites domestic manufacturing, import substitution, replacement demand, Gujarat capacity additions and technology upgrades as drivers, but the presentation does not disclose tyre pricing, funding, customer contracts, commissioning cost or a break-even date.
Conclusion
Viaz's expansion plan combines a Rs 350 crore FY29 revenue target with entry into four tyre categories alongside its butyl inner tube business. The new facility is listed with 1.60 million units of annual tyre capacity, while the existing operation retains 7.60 million units of annual capacity for butyl tubes and ancillary products; management also targets PAT margins of 8-10%, compared with 6%.
The next disclosed milestone is the planned H1FY27 start of the Mehsana tyre plant. Progress will depend on movement toward the facility's stated 50%E utilisation and 7-times asset-turnover measures, as well as management's updates on the route from the Rs 108 crore revenue base to the FY29 target.