










Aarti Pharmalabs expects full Atali asset use in H2 FY27
Key highlights
- Aarti Pharmalabs expects full utilisation of the Atali asset in H2 FY27.
- Atali Phase 1B is expected to be capitalised in Q3 FY27 after trial-batch production.
- CDMO/CMO contributed 13% of Q2 FY27 turnover and had 59 active projects across 23 customers.
- Aarti Pharmalabs is targeting 40% to 50% CDMO/CMO revenue growth in FY27.
powered by IRIS
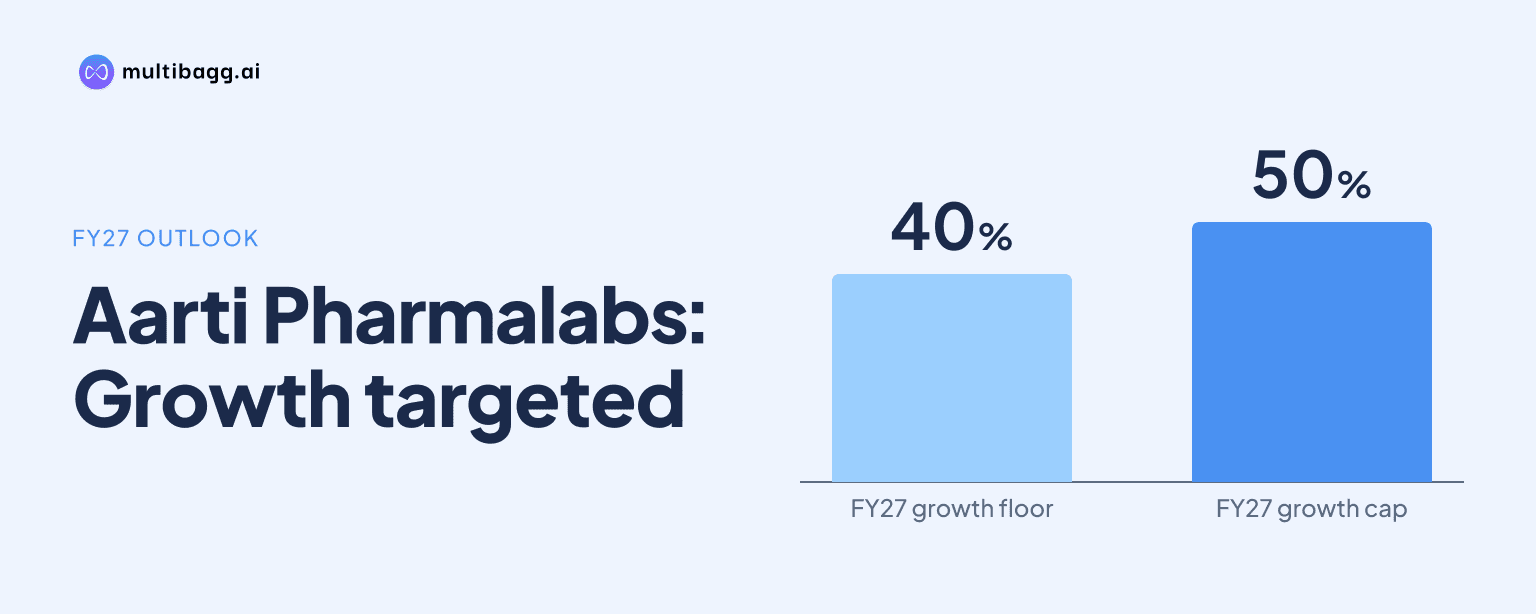
Aarti Pharmalabs Limited expects to fully utilise its Atali asset in H2 FY27 after capitalising Phase 1B in Q3 FY27, management said on October 29, 2026. The ramp supports its stated FY27 target of 40% to 50% growth in contract development and manufacturing organisation and contract manufacturing organisation (CDMO/CMO) revenue.
Know Aarti Pharmalabs inside out
Results, valuation, peers and who's buying, in one view.
When will Aarti Pharmalabs fully utilise the Atali asset?
Aarti Pharmalabs expects complete utilisation of the Atali asset during H2 FY27, while Phase 1B is scheduled for capitalisation in Q3 FY27. Managing Director Rashesh Gogri said the company sees sufficient CDMO/CMO demand to use the overall Atali asset fully in the second half, rather than describing Phase 1B as a major standalone addition to commercial capacity.
Atali Phase 1B had produced trial batches, and trials were under way in the week of the October 29, 2026 earnings call. Management said it would complete capitalisation of that block in Q3 FY27. Capitalisation moves the facility from construction-stage accounting into the operating asset base, after which its recurring costs begin to enter the profit and loss account.
Management distinguished between the two Phase 1 lines. Atali Phase 1B is a smaller line intended for early work on newer projects, while Phase 1A is a commercial or scale-up line that had already been commercialised and was in commissioning. The company said the smaller Phase 1B line would not have much bearing on Atali's overall capacity addition, despite expanding its capability for early-stage customer work.
How does Atali support Aarti Pharmalabs' CDMO growth plan?
Atali is intended to support Aarti Pharmalabs' FY27 target of 40% to 50% CDMO/CMO revenue growth. CDMO/CMO contributed 13% of Q2 FY27 turnover, and the company was working with 23 customers across 59 active projects. Of those projects, 39 were at commercial stages and 20 were at different development stages at customers.
Management said CDMO sales in Q2 FY27 were almost double the Q1 FY27 level. It also said CDMO revenue is normally weighted towards H2, which explains why inventory builds during H1 before deliveries increase in the second half. That sales pattern places the expected Atali utilisation ramp in the same period as the business's larger annual revenue contribution.
The pipeline gives management a stated basis for its growth goal, but customer progress remains relevant. Aarti Pharmalabs said the 59-project portfolio includes commercial and development work, while future volumes depend on how customer programmes proceed. The company also disclosed that its dedicated Atali Block 2 had completed groundbreaking and is targeted for commercialisation in H2 FY28, separate from the Phase 1A and 1B ramp in FY27.
Got a follow-up? Ask IRIS
What costs will follow Atali Phase 1B capitalisation?
Aarti Pharmalabs expects depreciation and recurring operating expenses to increase in H2 FY27 as Atali Phase 1B and other facilities are capitalised. Chief Financial Officer Piyush Lakhani said finance costs should remain at almost similar levels because most capital-expenditure financing had already been arranged, whereas depreciation will rise as assets are brought into use.
Management said Atali Block 1B, full caffeine capacity and early intermediate facilities will begin carrying expenses through the profit and loss account once capitalised. It did not provide a rupee estimate for incremental depreciation, employee costs or other operating expenses. The accounting change coincides with the expected H2 FY27 production ramp rather than with a disclosed change in financing needs.
Management said the earnings before interest, tax, depreciation and amortisation (EBITDA) margin could move by around 1 percentage point either way as operating leverage, CDMO/CMO mix and raw-material prices interact. EBITDA margin was 22.2% in Q2 FY27, compared with 17.7% a year earlier. The company said raw-material increases had been passed through in xanthine and allied chemistry and through some active pharmaceutical ingredient (API) price increases, while higher CDMO/CMO sales could support the margin percentage in Q3 and Q4.
What other H2 FY27 changes could affect the ramp?
Aarti Pharmalabs expects its xanthine expansion, including finished-product and intermediate production, to be fully operational by the end of FY27. Management said the two-phase xanthine project would also be fully capitalised by then. Xanthine and allied products accounted for 50% of Q2 FY27 turnover, compared with 30% for API and intermediates and 13% for CDMO/CMO.
Xanthine sales were lower in Q2 FY27 because shipments were held up by dispatch constraints, although allied-product sales increased. Management said it hoped the shipment issue would be resolved in the current quarter, which would allow overall sales to increase. It also said raw-material prices remained elevated because of geopolitical turmoil and that these costs were being passed on to customers.
The steroid-block expansion in the API plant was completed and began contributing to production and revenue in Q2 FY27. Management said debottlenecking in that block restored regular steroid sales that had been constrained in Q1 FY27. Separately, the company said its working-capital cycle was around 165 to 167 days, with inventory rising in H1 as it prepared for a more sales-weighted H2 in CDMO/CMO.
Conclusion
Aarti Pharmalabs is linking full Atali utilisation in H2 FY27 to CDMO/CMO growth rather than to Phase 1B alone. The smaller Phase 1B line will handle early work for newer projects, while Phase 1A provides the commercial or scale-up capability. The company has 59 active CDMO/CMO projects and is targeting 40% to 50% revenue growth in that business during FY27.
The next disclosed milestones are Q3 FY27 capitalisation of Atali Phase 1B and the resulting recurring depreciation and operating costs. Management also plans to make the xanthine expansion fully operational by the end of FY27, while the separate Atali Block 2 remains targeted for commercialisation in H2 FY28.