










ABD says H1 disruption cost ₹53 crore to reported earnings
Key highlights
- ABD estimated a ₹53 crore global supply-chain disruption impact in H1 FY27, including ₹29 crore in Q2 FY27.
- Reported H1 FY27 EBITDA was ₹263 crore, while like-for-like EBITDA excluding disruption would have been ₹316 crore.
- Q2 FY27 gross margin was 45.3%; management said it would have been 47.9% excluding the disruption.
- Management expects integration projects to add about 300 basis points to EBITDA margin by FY28 and another 150 basis points in FY29.
powered by IRIS
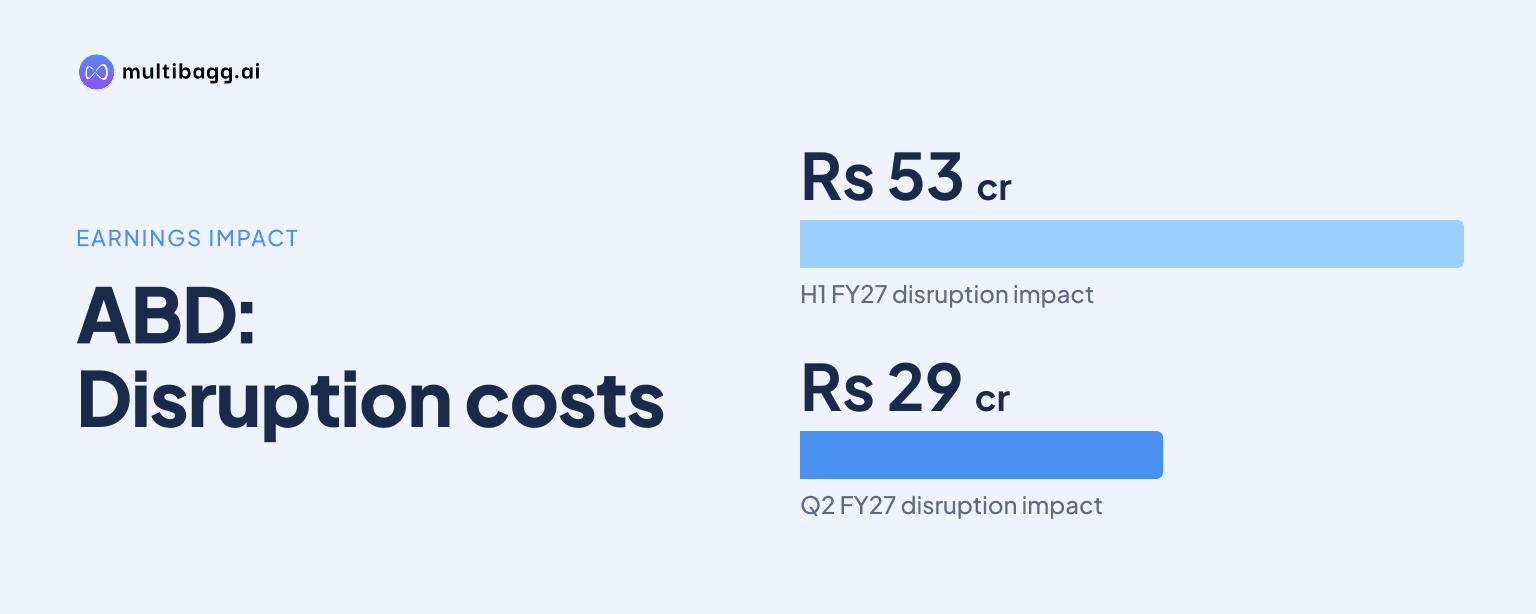
Allied Blenders and Distillers Limited said global supply-chain disruptions had an estimated ₹53 crore impact in H1 FY27, when reported EBITDA was ₹263 crore, up 5.8% year on year. Excluding that impact, management said like-for-like EBITDA would have reached ₹316 crore, representing 27.1% year-on-year growth.
Know Allied Blenders & Distillers inside out
Results, valuation, peers and who's buying, in one view.
How much did supply-chain disruption cost ABD in H1 FY27?
ABD estimated that global supply-chain disruptions affected H1 FY27 profitability by ₹53 crore, including ₹29 crore in Q2 FY27. The transcript identifies the issue as a global supply-chain disruption but does not specify the affected geography, input materials or cost mechanism behind the estimated ₹53 crore impact.
The Q2 FY27 effect was significant relative to reported earnings. ABD reported quarterly EBITDA of ₹143 crore and profit after tax, or PAT, of ₹69 crore. Excluding the ₹29 crore disruption impact, management said EBITDA would have been ₹172 crore and PAT would have been ₹91 crore, with like-for-like EBITDA growth of 32.3% year on year.
The disruption also affected the quarterly margin comparison. Q2 FY27 gross margin was 45.3%, up 90 basis points year on year, while the like-for-like gross margin would have been 47.9%, up 342 basis points, according to management. A basis point is one-hundredth of a percentage point.
Reported Q2 FY27 EBITDA margin was 12.4%, down 66 basis points year on year. Management said the lower reported margin also reflected continuing investment in core brands and the newly established super-premium-to-luxury portfolio; without the disruption, it said EBITDA margin would have been 14.9%, up 186 basis points.
What did ABD report for H1 FY27 earnings?
ABD reported H1 FY27 income from operations of ₹2,135 crore, up 10.9% year on year, EBITDA of ₹263 crore, up 5.8%, and PAT of ₹114 crore, compared with ₹119 crore in H1 FY26. The difference between sales growth and the PAT decline coincided with the stated ₹53 crore disruption impact.
Management's like-for-like comparison places EBITDA ₹53 crore above the reported result and PAT ₹40 crore above reported PAT. The different EBITDA and PAT adjustments should not be interpreted as a tax calculation, because the transcript does not disclose a tax rate or reconcile the difference.
Operating cash flow increased to ₹269 crore in H1 FY27 from ₹147 crore in H1 FY26. At the same time, net debt rose by ₹292 crore from March 2026 to ₹1,273 crore at September 2026, predominantly because ABD spent ₹351 crore on capital expenditure during the half-year.
Got a follow-up? Ask IRIS
Which businesses drove ABD's Q2 FY27 growth?
ABD's Mass Premium and Others segment generated faster Q2 FY27 volume growth, while Prestige & Above produced the larger sales value. Mass Premium and Others net sales value rose 15.9% year on year to ₹468 crore, with volumes increasing 15.5% to 5.5 million cases; Prestige & Above sales rose 13.4% to ₹605 crore and volumes increased 6.1% to 4.5 million cases.
Prestige & Above had a higher realisation per case of ₹1,339, up 6.9% year on year, compared with ₹848 in Mass Premium and Others, up 0.4%. Despite that pricing gap, Prestige & Above's share of Q2 sales edged down to 56.4% from 56.9% in Q2 FY26 because Mass Premium and Others grew faster.
Management attributed Mass Premium and Others growth partly to brandy sales in Andhra Pradesh after a rollout following Q4 FY26 approvals. It said ABD had achieved near-double-digit market share in the state's Mass Premium category, while Officer's Choice Whisky rebounded in the southern region, with support from eastern markets and exports.
Within Prestige & Above, ICONiQ White sold 3.2 million cases in Q2 FY27, up 20.6% from 2.6 million cases a year earlier. H1 FY27 volume reached 6.2 million cases, up 26.8%, as Q2 total company volume crossed 10 million cases for the first time.
What margin outlook did ABD disclose?
ABD disclosed expected integration-led EBITDA-margin benefits of about 300 basis points by FY28 and a further 150 basis points in FY29, rather than a specific FY27 margin target in the supplied transcript. Management linked the outlook to projects in Telangana, Maharashtra, Uttar Pradesh and Andhra Pradesh intended to improve supply security and reduce structural costs.
In Telangana, ABD commissioned a captive malt distillery at Rangapur in October 2026 with investment of about ₹75 crore and annual capacity of about 4 million bulk litres. Management said the plant would reduce external malt sourcing for the Prestige & Above portfolio and be margin accretive through in-house manufacturing; the existing PET-bottle facility at Rangapur, commissioned in FY26, was already EBITDA accretive.
In Uttar Pradesh, ABD commenced commercial operations at its Moradabad bottling facility in October 2026, starting with capacity of 6 million cases annually. Management said higher in-house bottling could save around ₹27 per case in franchise fees, while the company has announced a ₹293.5 crore dual-mode distillery and about ₹202 crore for bottling expansion, distillery refurbishment and additional land.
The Maharashtra bottling project at subsidiary Minakshi Agro Industries was expected to become operational in the next couple of months from the October 28, 2026 call. Management also said construction on the Maharashtra extra neutral alcohol, or ENA, distillery expansion was under way after environmental clearance, with operations targeted in H1 FY28.
Conclusion
ABD's H1 FY27 earnings combined 10.9% growth in income from operations to ₹2,135 crore with a ₹53 crore estimated supply-chain disruption impact. Q2 segment results showed faster volume growth in Mass Premium and Others at 15.5%, while Prestige & Above retained higher per-case realisation of ₹1,339 versus ₹848.
The next disclosed operational markers are the Maharashtra bottling project's expected start in the next couple of months and the Maharashtra ENA expansion targeted for H1 FY28. Management's stated margin plan depends on projects including the October 2026 Telangana malt-distillery commissioning and Uttar Pradesh bottling start delivering the projected 300-basis-point benefit by FY28 and another 150 basis points in FY29.