










Ajax Engineering H1 FY27 PAT rises 15.9%, outpacing sales
Key highlights
- Ajax H1 FY27 PAT rose 15.9% year on year to Rs 106.5 crore, while revenue rose 5.5% to Rs 961.6 crore.
- Ajax Non-SLCM revenue increased 31.5% to Rs 103.5 crore, versus 3.3% growth in SLCM revenue.
- Ajax's H1 FY27 SLCM retail market share reached 75.5%, compared with 70.7% in H1 FY26.
- Ajax's H1 FY27 net operating cash flow fell to Rs 5.5 crore from Rs 17.3 crore.
powered by IRIS
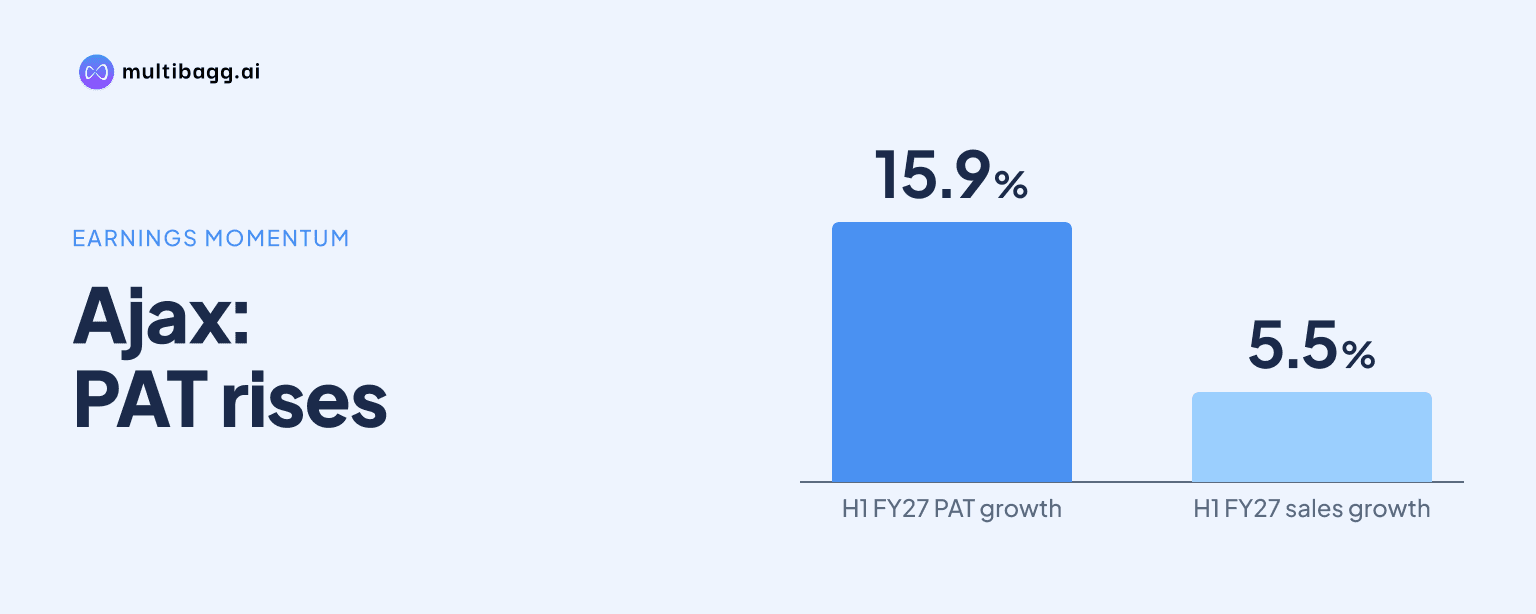
Ajax Engineering reported H1 FY27 profit after tax of Rs 106.5 crore, up 15.9% year on year, while revenue from operations rose 5.5% to Rs 961.6 crore. The profit increase exceeded sales growth as other income rose Rs 15.3 crore to Rs 38 crore and PAT margin expanded by 100 basis points to 11.1%.
Know Ajax Engineering inside out
Results, valuation, peers and who's buying, in one view.
Why did Ajax's PAT grow faster than revenue in H1 FY27?
Ajax's PAT grew faster than revenue because profit before tax rose 15.4% to Rs 142.5 crore, supported by higher other income, even as EBITDA growth was 3.7%. EBITDA means earnings before interest, tax, depreciation and amortisation. Revenue increased by Rs 50.3 crore from H1 FY26, while PAT increased by Rs 14.6 crore.
Other income rose to Rs 38 crore in H1 FY27 from Rs 22.7 crore in H1 FY26, a Rs 15.3 crore increase. This was larger than the Rs 4 crore increase in EBITDA, which reached Rs 110.6 crore. PAT margin increased to 11.1% from 10.1%, while profit before tax rose Rs 18.9 crore from Rs 123.6 crore.
Ajax's gross profit increased 6.6% to Rs 242.2 crore in H1 FY27, faster than revenue growth, while gross margin increased 20 basis points to 25.2%. However, other expenses increased to Rs 74.8 crore from Rs 63.5 crore, and EBITDA margin declined 20 basis points to 11.5% from 11.7%. Management said the first-half margin was broadly stable despite a one-time SAP implementation cost, for which it did not disclose an amount.
How did Ajax's segments perform in H1 FY27?
Ajax's self-loading concrete mixer, or SLCM, revenue rose 3.3% to Rs 783.5 crore in H1 FY27, making it the largest reported business, while Non-SLCM revenue increased 31.5% to Rs 103.5 crore. Spares and services revenue grew 0.7% to Rs 74.6 crore, compared with 31.5% growth in Non-SLCM products.
SLCM volume rose 2.5% year on year to 2,370 units in H1 FY27. Non-SLCM volume increased 12.6% to 303 units. The second-quarter trend was faster: Q2 FY27 SLCM volume increased 6.3% and Non-SLCM volume increased 50.0%, with Q2 Non-SLCM revenue up 64.7% to Rs 55.8 crore.
Ajax reported SLCM retail market share of 75.5% in H1 FY27, compared with 70.7% in H1 FY26, an increase of approximately 480 basis points. Export revenue grew 48% year on year during the half, although management said exports remained a small share of overall revenue. Management identified batching plants and pumps as areas of focus for its Non-SLCM business.
What happened to Ajax's margins and costs in H1 FY27?
Ajax maintained a 25.2% gross margin in H1 FY27, 20 basis points above H1 FY26, as price hikes offset higher raw-material costs. Management said steel and other crude-linked commodities contributed to an approximately 6% to 7% year-on-year increase in construction-equipment manufacturing costs during the half.
The margin picture differed between Q2 FY27 and H1 FY27. Q2 gross margin was 24.2%, while Q2 EBITDA margin was 10.6%, up 40 basis points year on year. H1 EBITDA margin was 11.5%, down 20 basis points year on year, whereas H1 PAT margin increased by 100 basis points to 11.1%.
Ajax took a price increase of approximately 1% in September 2026. Management said it would consider further calibrated price increases during H2 FY27 while pursuing supplier diversification, competitive sourcing and cost optimisation. These measures were disclosed as management actions in response to input-cost pressure rather than as a forecast of future margins.
Got a follow-up? Ask IRIS
Why did Ajax's operating cash flow fall in H1 FY27?
Ajax's net cash flow from operating activities fell to Rs 5.5 crore in H1 FY27 from Rs 17.3 crore in H1 FY26 because working-capital changes used Rs 88.9 crore. Operating profit before working-capital changes still increased to Rs 129.3 crore from Rs 121.8 crore, but cash generated from operations declined to Rs 40.4 crore from Rs 55.7 crore.
Income tax paid or refunded was Rs 34.9 crore in H1 FY27, compared with Rs 38.5 crore in H1 FY26. The smaller tax outflow did not offset the higher working-capital use, which was Rs 22.8 crore more than the Rs 66.1 crore used a year earlier. Ajax reported net working capital of 22 days in its H1 FY27 highlights.
Investing activities used Rs 117.9 crore in H1 FY27, compared with Rs 29.8 crore in H1 FY26. Cash and cash equivalents ended September 2026 at Rs 53.4 crore, down from Rs 165.9 crore at March 2026, while current investments rose to Rs 1,050 crore from Rs 882 crore. Ajax separately reported a cash balance of Rs 1,151.1 crore, excluding cash earmarked for corporate social responsibility purposes.
What does Ajax expect in H2 FY27?
Ajax management expects customer sentiment and demand momentum to improve in H2 FY27 after a soft first half. It attributed near-term conditions to lower-than-budgeted state infrastructure spending and delayed contractor payments. State capital-expenditure utilisation was 77.2% of budget in FY26, below 80.2% in FY25, while April to August FY27 utilisation was 21% of the full-year budget.
Road activity was another disclosed constraint: highway construction declined 19% year on year in H1 FY27, while road capital expenditure increased only 2% in April to August 2026. Management said it expects road construction to average 21 kilometres per day in FY27, compared with 25 kilometres per day in FY26.
Ajax plans to expand SLCM applications through private-sector engagement and the UDAAN series, while preparing to launch the ARGO 4000 to address a stated gap in its product portfolio. Management also intends to grow Non-SLCM sales through batching plants and pumps, alongside disciplined working-capital management and capital allocation.
Conclusion
Ajax's H1 FY27 result combined modest 5.5% revenue growth with a 15.9% increase in PAT to Rs 106.5 crore. Higher other income and a 100-basis-point increase in PAT margin contributed to the difference between sales and profit growth, while Non-SLCM revenue rose 31.5%, SLCM revenue grew 3.3%, and net operating cash flow fell to Rs 5.5 crore.
The next disclosures to watch are whether the H2 FY27 demand recovery expected by management materialises, whether further calibrated price increases follow the September 2026 1% hike, and progress on the planned ARGO 4000 launch and UDAAN expansion. Working-capital conversion also remains relevant after Rs 88.9 crore of working-capital cash use and Rs 117.9 crore of investing outflow in H1 FY27.