










Alivus retains FY27 margin target after 39.5% adjusted Q2
Key highlights
- Alivus reported an approximately 39.5% adjusted EBITDA margin in Q2 FY27, versus a 41.8% reported margin.
- Alivus retained FY27 EBITDA margin guidance of 35%-36% and revenue-growth guidance of 10%-12%.
- Q2 FY27 revenue was Rs 682 crore, up 16% year-on-year, while EBITDA was Rs 285 crore, up 47% year-on-year.
- CDMO revenue was Rs 50 crore in Q2 FY27, up 32.3% quarter-on-quarter and nearly 80% year-on-year.
powered by IRIS
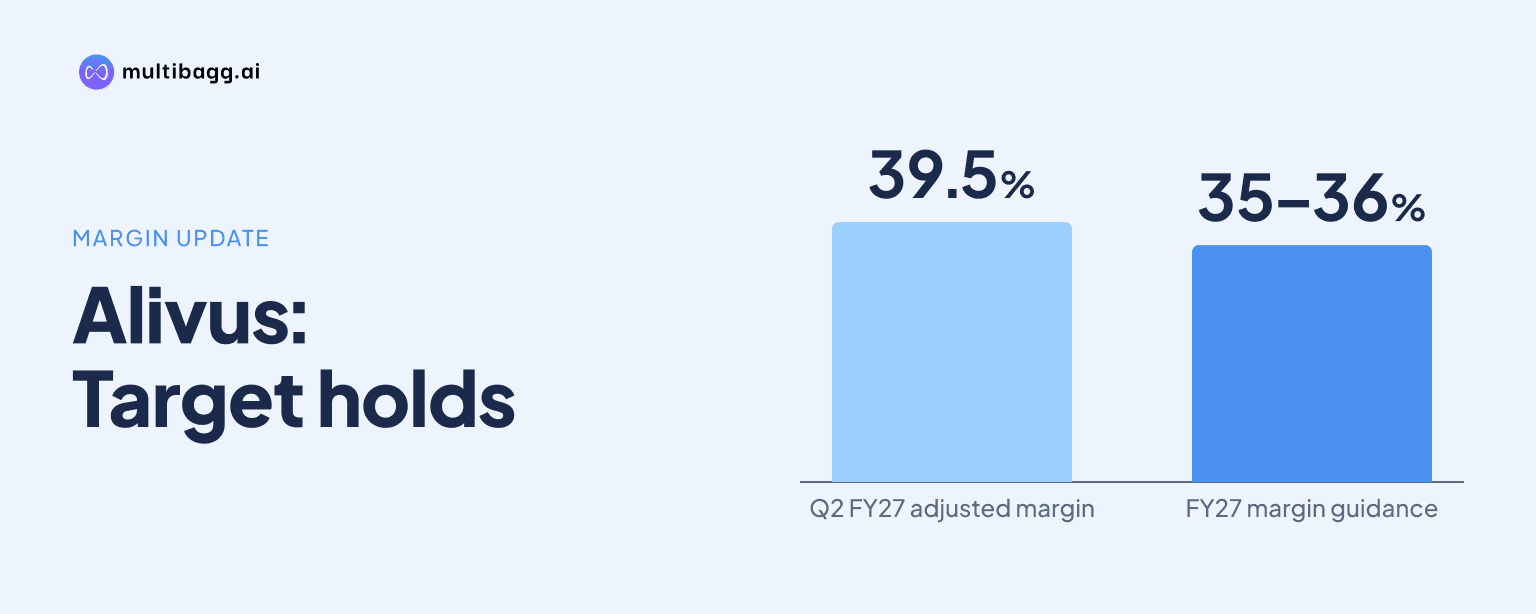
Alivus Life Sciences Limited retained its FY27 earnings before interest, tax, depreciation and amortisation (EBITDA) margin guidance of 35%-36% after reporting an approximately 39.5% adjusted EBITDA margin in Q2 FY27, versus a 41.8% reported margin. Management attributed the underlying improvement to launch-led product mix and operating efficiencies, while noting one-off contributors in the quarter.
Know Alivus Life Sciences inside out
Results, valuation, peers and who's buying, in one view.
What drove Alivus's Q2 FY27 EBITDA margin?
Alivus's reported Q2 FY27 EBITDA margin rose to 41.8%, up 520 basis points quarter-on-quarter and 880 basis points year-on-year, as revenue from operations grew 16% year-on-year to Rs 682 crore. EBITDA increased 47% year-on-year to Rs 285 crore, while gross profit increased 29.5% to Rs 439 crore. A basis point is one-hundredth of a percentage point.
Management said the quarter included a validation supply of a complex product with high margins and a one-off income accrual from a customer. Excluding one-time income, Alivus reported an adjusted EBITDA margin of approximately 39.5%. The reported 41.8% margin therefore included items that management identified as non-recurring alongside operating improvement.
Alivus's gross margin reached 64.4% in Q2 FY27, up 670 basis points year-on-year, which management attributed to favourable product mix and recent launches. In response to an analyst question, management said gross margin should be expected at around 60% going forward, below the Q2 level but consistent with the last two quarters cited by the analyst.
What is improving Alivus's underlying margins?
Alivus said new launches and launches from the previous year are improving margins because the portfolio is moving toward more complex and higher-end molecules. Non-GPL business grew 20.8% year-on-year in Q2 FY27 and accounted for 79% of revenue, while GPL revenue grew 1% year-on-year. Management did not provide product-level margin details.
Management said newly launched products typically retain their margin profile for about 18 to 24 months before normalising. Its stated approach to sustaining profitability is to add further launches as earlier products mature, although this is management's view and depends on the pace and mix of future introductions.
The business mix showed differing growth rates in Q2 FY27. Generic active pharmaceutical ingredient (API) revenue grew 11% year-on-year, while contract development and manufacturing organisation (CDMO) revenue reached Rs 50 crore, up 32.3% quarter-on-quarter and nearly 80% year-on-year. Management said CDMO growth came from higher demand across five existing projects and contributions from projects added during the prior year.
Chronic therapies contributed 67% of Q2 FY27 revenue, while cardiovascular system and central nervous system therapies together represented 50% of the top line. Research and development expenditure was Rs 27 crore, or 4% of quarterly sales, as Alivus continued to invest in products that management expects to influence portfolio quality.
Got a follow-up? Ask IRIS
Can Alivus meet its FY27 EBITDA margin guidance?
Alivus retained FY27 EBITDA margin guidance of 35%-36% and revenue-growth guidance of 10%-12%, despite expecting a higher GPL contribution in the second half. Management said non-GPL business has comparatively better margins, but described GPL as a stable-margin business rather than a very low-margin one.
For H1 FY27, revenue from operations was Rs 1,322 crore, up 11.1% year-on-year, and EBITDA was Rs 519 crore, up 38.4%. The H1 EBITDA margin was 39.3%, up 780 basis points year-on-year, while gross margin rose 590 basis points to 62.3%. These H1 margins were above the full-year range management reiterated.
Alivus expects GPL revenue to follow its historical pattern of stronger H2 contribution and forecast FY27 GPL revenue of Rs 700 crore to Rs 750 crore. Management said the larger GPL mix could bring margins down from the H1 level, but remains confident that the 35%-36% full-year EBITDA margin range can be achieved.
Profit after tax for H1 FY27 was Rs 357 crore, with a margin of 27%, up 590 basis points year-on-year. This compared with Q2 FY27 profit after tax of Rs 197 crore and a 28.9% margin, up 390 basis points quarter-on-quarter and 680 basis points year-on-year.
What could affect Alivus's margins in H2 FY27?
Alivus said it has largely passed raw-material inflation on to customers, and management described pricing erosion in H1 FY27 as lower than usual. It nevertheless said generic APIs face regular price erosion, which the business factors into its planning, while characterising the present pricing environment as stable.
Solvents were the principal external cost risk management identified. Alivus estimated solvents account for about 10%-12% of raw-material costs and about 7%-8% of cost of goods sold. Management said inventory actions had helped manage solvent inflation in the previous three quarters, but a sharp rise in crude prices could increase solvent costs.
Alivus said it had moved boiler fuel from gas to biobriquettes, helping keep operating costs stable as gas prices increased. Management also cited higher freight costs related to the Middle East conflict, but said freight is a small cost component. On that basis, it identified crude-linked solvent costs as the more material near-term risk.
How do Solapur and CDMO plans support Alivus's outlook?
Alivus expects Phase 1 of its Solapur facility to become operational in Q3 FY27 and described it as a potentially significant growth driver over two to three years. Management said Ankleshwar contributes almost 65% of revenue and sees Solapur as a facility that can support new products, larger-volume APIs and potentially high-value intermediates.
Capital expenditure was Rs 105 crore in Q2 FY27 and Rs 190 crore in H1 FY27. Free cash flow in H1 FY27 was Rs 270 crore, while cash and cash equivalents, including short-term investments, stood at Rs 1,012 crore as of September 30, 2026. Management said Alivus remained net debt-free.
Alivus said it is discussing several potential CDMO projects and hopes to close a couple in the first half of the next year, including one project in advanced stages. Those discussions are not booked revenue. The Rs 50 crore of Q2 FY27 CDMO revenue came from the existing five-project base, supported by higher demand rather than projects newly added in the quarter.
Conclusion
Alivus's Q2 FY27 result combined a 41.8% reported EBITDA margin with an approximately 39.5% adjusted margin and a retained FY27 target of 35%-36%. One-off items aided the reported quarter, but management also linked the improvement to launch-led portfolio mix, faster non-GPL growth, CDMO demand and operating efficiencies.
The next disclosures to watch are Phase 1 commissioning at Solapur in Q3 FY27, the expected H2 increase in GPL revenue and progress on CDMO project discussions in the first half of the next year. Management's expectation of gross margins around 60% and its stated 18- to 24-month launch-margin window will also frame how investors assess margin progression as products mature.