










All Time Plastics Q2 EBITDA margin falls to 7.9% on costs
Key highlights
- All Time Plastics' Q2FY27 standalone revenue rose 18% year on year to Rs 174 crore.
- All Time Plastics' Q2FY27 standalone EBITDA margin fell to 7.9% from 11.0% in Q2FY26.
- Management said key polymer prices increased 40–45% and September container shortages delayed export shipments.
- All Time Plastics reported a Rs 25.1 crore standalone H1FY27 net operating cash outflow, versus a Rs 53.4 crore inflow a year earlier.
powered by IRIS
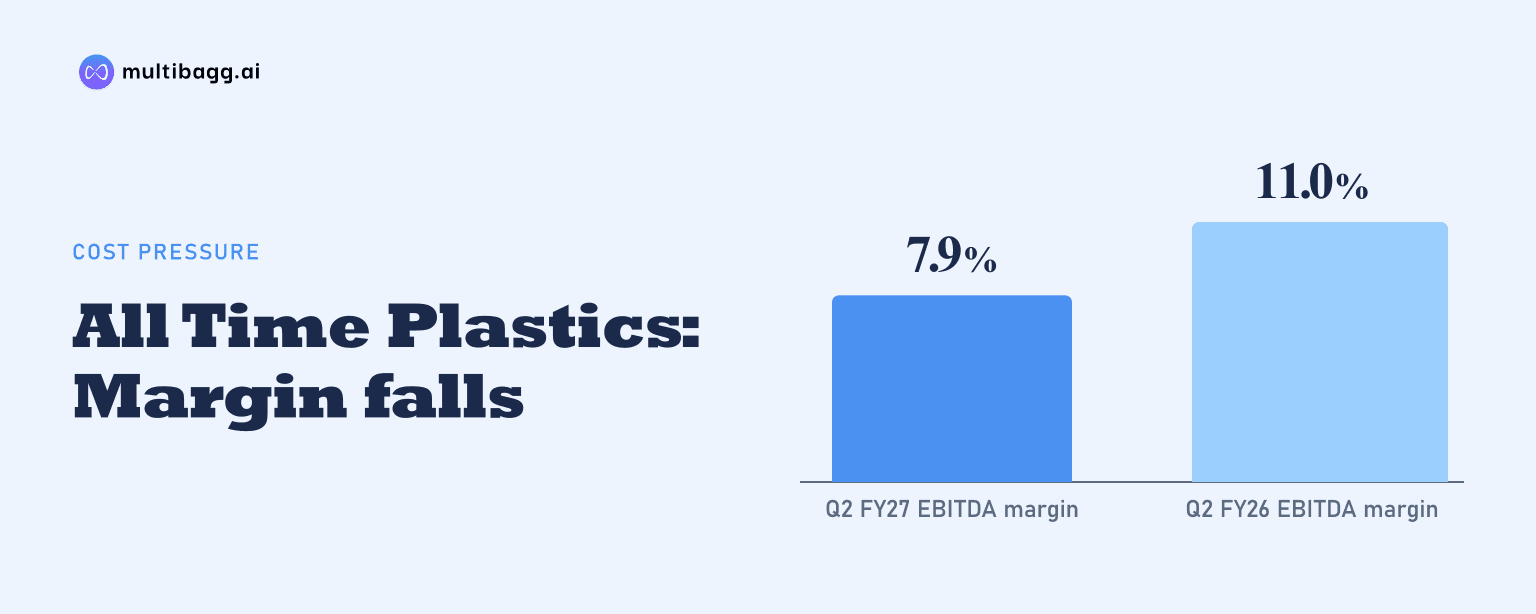
All Time Plastics Limited reported Q2FY27 revenue growth of 18% year on year to Rs 174 crore, but its standalone earnings before interest, tax, depreciation and amortisation (EBITDA) margin fell to 7.9% from 11.0% as key polymer prices increased 40–45% and September container shortages delayed export shipments.
Know All Time Plastics inside out
Results, valuation, peers and who's buying, in one view.
Why did All Time Plastics' Q2 EBITDA margin decline?
All Time Plastics' Q2FY27 EBITDA margin declined because input costs rose after export orders had been priced, while shipment disruption and higher fixed costs added pressure. Management said the escalation of the West Asia conflict increased average prices of key polymers by 40–45%, and that export prices are fixed for each order and can be revised only for new orders.
Management said lower-cost inventory that had cushioned Q1FY27 was fully consumed in Q2FY27. It said All Time Plastics absorbed part of the material-cost increase to protect long-standing customer relationships, rather than cede business to Asian competitors. Labour and staff costs at the new Khatalwada and bamboo facilities also rose against H1FY26, before those assets reach higher utilisation.
The standalone financial highlights show EBITDA fell to Rs 14 crore in Q2FY27 from Rs 16 crore in Q2FY26, although gross profit rose to Rs 60 crore from Rs 53 crore. Gross margin declined by 1.9 percentage points to 34.3%, while EBITDA margin declined by 3.1 percentage points to 7.9%, reflecting both the raw-material increase and higher operating costs.
How did revenue growth affect All Time Plastics' profitability?
All Time Plastics generated more revenue in Q2FY27 but less operating profit because sales increased faster than gross profit and employee and other expenses rose. Revenue increased by Rs 27 crore year on year to Rs 174 crore, while management said revenue was also 8% higher sequentially and polymer volume processed was more than 9% higher sequentially.
The detailed profit-and-loss statement reports EBITDA of Rs 13.7 crore in Q2FY27, down 15.8% from Rs 16.3 crore a year earlier. Earnings before interest and tax (EBIT) fell 25.4% to Rs 8.0 crore, and its margin declined to 4.6% from 7.3%; depreciation increased to Rs 8.3 crore from Rs 7.2 crore.
Profit after tax was Rs 4.2 crore in both Q2FY27 and Q2FY26 in the detailed statement, but the margin declined to 2.4% from 2.9%. Cash profit after tax increased to Rs 12.6 crore from Rs 11.4 crore in the standalone quarterly highlights, while reported profit remained flat despite the 18% revenue rise.
The first-half comparison shows that margin pressure extended beyond the quarter. H1FY27 revenue rose 9.7% to Rs 335.1 crore, but EBITDA declined 18.4% to Rs 36.7 crore and margin fell to 11.0% from 14.7%; polymer volume processed declined to 13,234 metric tonnes from 14,262 metric tonnes.
Got a follow-up? Ask IRIS
What did shipping disruption do to All Time Plastics' cash flow?
All Time Plastics said delayed outbound shipping temporarily increased finished-goods stock and contributed to a Rs 25.1 crore standalone H1FY27 net operating cash outflow. Management said September container shortages roughly doubled finished-goods stock, while the company also held higher raw-material buffers. It said shipments resumed in October and the export backlog was clearing quickly.
Standalone inventories were Rs 120.2 crore at H1FY27, compared with Rs 68.6 crore at FY26 end. Trade receivables rose to Rs 100.1 crore from Rs 74.9 crore; management attributed the increase largely to changed banking arrangements at two key customers and said collections were arriving.
Working-capital changes used Rs 60.8 crore of standalone cash in H1FY27, compared with a Rs 16.8 crore source of cash in H1FY26. Cash generated from operations consequently moved to negative Rs 21.9 crore from positive Rs 62.4 crore, while net cash from operating activities moved to negative Rs 25.1 crore from positive Rs 53.4 crore.
Standalone cash and cash equivalents ended H1FY27 at Rs 46.0 crore, down from Rs 86.5 crore at the beginning of the year. Current borrowings rose to Rs 49.3 crore from Rs 24.4 crore at FY26 end, while non-current borrowings declined to Rs 45.3 crore from Rs 55.9 crore; debt to equity was 0.15 versus 0.21 in H1FY26.
Can domestic growth and new capacity support All Time Plastics' plan?
Management's plan is to reset prices on new orders, accelerate domestic sales and increase contribution from new capacity. Management said domestic revenue rose about 36% sequentially and 27% year on year in Q2FY27, lifting its share to 19.5%. The quarterly financial highlights show a rounded domestic mix of 20%, compared with 18% in Q2FY26.
All Time Plastics added 36 domestic customers in H1FY27, launched a Hydration range of bottles and piloted a direct-to-consumer online channel in October 2026. Management also said business with one US customer had more than doubled after several stationery products entered that customer's core assortment, without providing a revenue figure for that relationship.
The company initiated Supervisory Control and Data Acquisition (SCADA) real-time machine monitoring at Khatalwada and added blow-moulding capability for bottles, jars and containers. Management expects 14 new machines adding about 1,500 tonnes to be installed in December 2026; plant utilisation was 67% in Q2FY27, compared with 83% a year earlier.
Management expects the Guwahati bamboo facility to begin commercial production in mid-November 2026, with sales commencing in Q4FY27. It expects Rs 25 crore to Rs 30 crore of revenue from the facility in calendar year 2027, while saying further capital expenditure will be calibrated to demand.
Conclusion
All Time Plastics combined an 18% Q2FY27 revenue increase with lower operating profitability as a 40–45% polymer-price increase hit fixed-price export orders, container shortages delayed shipments and new-facility costs rose. The effect was visible in the 3.1-percentage-point decline in quarterly EBITDA margin to 7.9% and the H1FY27 operating cash outflow of Rs 25.1 crore.
The next disclosed milestones are price resets across customers, clearance of the shipping backlog and installation of 14 machines adding about 1,500 tonnes in December 2026. Management also expects Guwahati bamboo-facility sales to start in Q4FY27 and forecasts Rs 25 crore to Rs 30 crore of facility revenue in calendar year 2027.