










Alufluoride Q2 profit rises 91% as operations recover
Key highlights
- Alufluoride reported Q2FY27 consolidated PAT of Rs 15.2 crore, up 91% year on year.
- Q2FY27 consolidated revenue reached Rs 63.9 crore, up 17% year on year and 140% quarter on quarter.
- Q2FY27 EBITDA margin expanded to 38.1% from 26.1% in Q2FY26.
- H1FY27 PAT rose 62% to Rs 17.9 crore despite an 8% decline in revenue to Rs 90.5 crore.
powered by IRIS
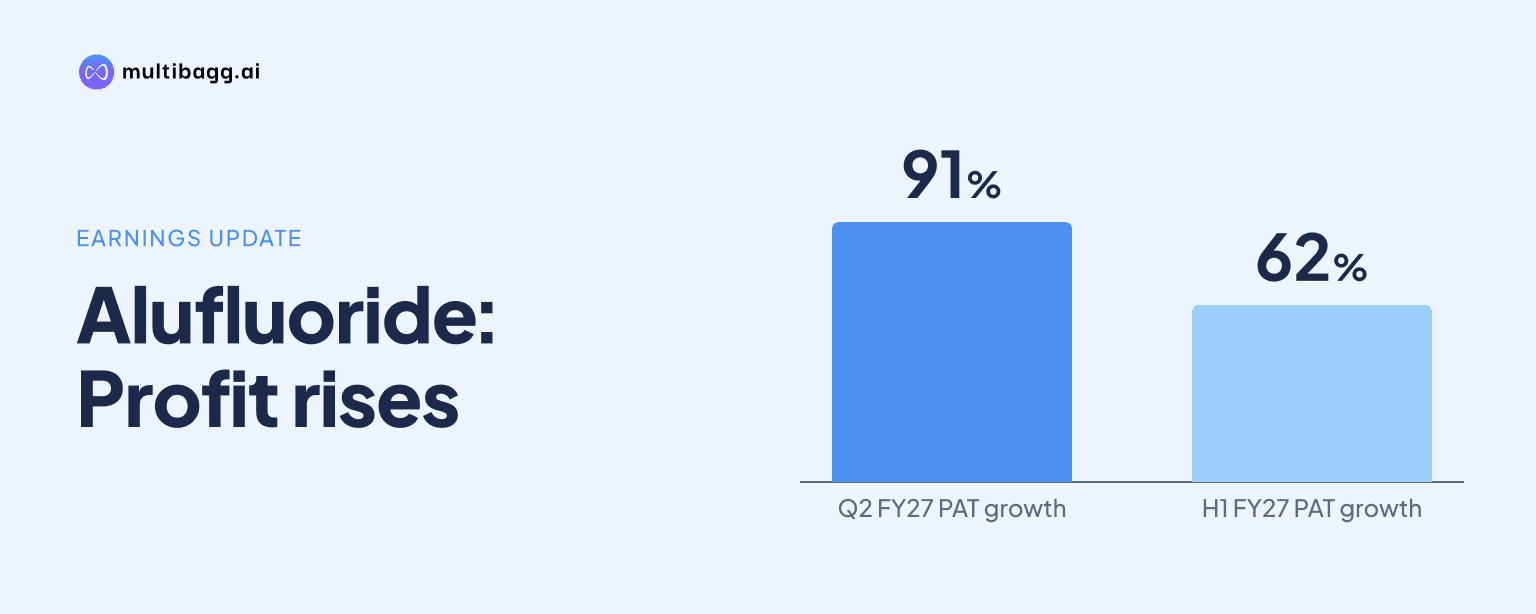
Alufluoride Limited reported consolidated Q2FY27 profit after tax of Rs 15.2 crore, up 91% year on year, after its Visakhapatnam plant recovered towards normal operations following a first-quarter hydrofluosilicic acid supply constraint. Revenue rose 17% to Rs 63.9 crore and EBITDA margin reached 38.1%.
Know Alufluoride inside out
Results, valuation, peers and who's buying, in one view.
How did Alufluoride perform in Q2FY27?
Alufluoride delivered a quarterly recovery, with consolidated revenue rising to Rs 63.9 crore in Q2FY27 from Rs 54.8 crore in Q2FY26 and Rs 26.6 crore in Q1FY27. The company said operations at its Visakhapatnam plant returned towards normal after its supplier reported on 15 July 2026 that the hydrofluosilicic acid, or FSA, supply issue had been resolved.
Consolidated EBITDA, the company’s measure of profit before exceptional items and tax with finance costs and depreciation added back, increased 70% year on year to Rs 24.4 crore from Rs 14.3 crore. Profit after tax, or PAT, rose faster to Rs 15.2 crore from Rs 7.9 crore, while basic and diluted earnings per share increased to Rs 19.38 from Rs 10.14. Sequentially, PAT was 452% above Rs 2.7 crore in Q1FY27, which was affected by the raw-material disruption.
The recovery was concentrated in aluminium fluoride operations, which generated Rs 63.9 crore of Q2FY27 revenue against Rs 54.8 crore a year earlier. Captive solar units contributed nil revenue in both quarters. Other income rose to Rs 1.3 crore from Rs 0.4 crore, taking total income to Rs 65.2 crore, up 18% from Rs 55.2 crore.
Why did Alufluoride’s profit grow faster than revenue?
Alufluoride’s profit grew faster than revenue mainly because material costs took a smaller share of sales, while other income increased and the effective tax rate declined. Materials, net of inventory change, were 36.4% of Q2FY27 revenue, compared with 48.8% in Q2FY26, helping EBITDA margin expand to 38.1% from 26.1%.
Excluding other income, EBITDA margin was 36.1%, compared with 25.4% a year earlier and 17.1% in Q1FY27. The company attributed the material-cost movement to alumina hydrate bought in advance at favourable prices and now being consumed at that cost, as well as annual selling prices agreed with smelters in May 2026 after input costs had risen. Alufluoride said the benefit from those lower-cost alumina hydrate stocks will fade as inventory is used.
Profit before tax rose by Rs 9.2 crore to Rs 20.5 crore. Alufluoride estimated that lower material cost as a share of revenue accounted for about Rs 7.9 crore of the increase, higher revenue at the previous year’s operating margin contributed about Rs 2.3 crore, and other income added Rs 0.9 crore. Employee and other operating costs reduced the gain by about Rs 1.1 crore, while depreciation and finance costs related to the expanded plant reduced it by about Rs 0.9 crore.
Tax expense was Rs 5.4 crore in Q2FY27, compared with Rs 3.4 crore in Q2FY26, but the effective tax rate declined to 26.1% from 29.9%. Power and fuel cost Rs 8.7 crore, or 13.6% of revenue, compared with 13.5% a year earlier. Employee benefit expense rose to Rs 3.8 crore, or 6.0% of revenue, from 4.6%, while finance costs and depreciation were Rs 1.0 crore and Rs 2.9 crore, respectively.
Got a follow-up? Ask IRIS
What does the first-half result show after the disruption?
Alufluoride’s H1FY27 revenue remained below the prior year because the Q1 supply shortfall outweighed the Q2 rebound, but PAT and EBITDA rose. Consolidated revenue for the half year ended 30 September 2026 was Rs 90.5 crore, down 8% from Rs 98.6 crore in H1FY26, whereas EBITDA increased 43% to Rs 31.3 crore from Rs 21.9 crore.
H1FY27 PAT was Rs 17.9 crore, up 62% from Rs 11.0 crore, and earnings per share increased to Rs 22.89 from Rs 14.11. The difference between an 8% revenue decline and a 62% PAT increase reflects the first-quarter operational interruption alongside the second-quarter improvement in conversion efficiency and cost mix described by the company.
The disruption arose from reduced availability of FSA, a fluorine byproduct used by Alufluoride to make high-purity aluminium fluoride. Alufluoride had disclosed the temporary reduction in Visakhapatnam operations to stock exchanges on 23 May 2026. Management said Q2 revenue was 2.4 times Q1 revenue after the supplier’s 15 July 2026 notification that the issue had been resolved.
Alufluoride completed the final phase of its expansion in June 2026, taking installed aluminium fluoride capacity to 24,000 tonnes per annum. Managing Director Venkata Akkineni said the second quarter showed what the expanded platform could do when raw-material flows were available, while identifying FSA cost and availability as the variable the company was managing most closely.
What changed in Alufluoride’s balance sheet and supply arrangements?
Alufluoride’s net block of property, plant and equipment increased to Rs 92.9 crore at 30 September 2026 from Rs 65.0 crore at 31 March 2026 as expansion spending was capitalised. Capital work in progress fell to Rs 1.8 crore from Rs 22.5 crore over the same period, while net worth rose to Rs 140.6 crore from Rs 125.7 crore.
Cash, bank balances and current investments stood at Rs 62.9 crore, compared with Rs 45.0 crore at 31 March 2026. Total borrowings increased to Rs 34.3 crore from Rs 28.5 crore. Inventories rose to Rs 29.1 crore from Rs 21.0 crore and trade receivables increased to Rs 18.9 crore from Rs 10.9 crore, which Alufluoride said was in line with the higher level of activity.
FSA sourcing remains an operating focus. Alufluoride obtains the acid from the adjacent fertiliser complex and more distant sources, principally under a long-term contract with Indian Farmers Fertiliser Cooperative Limited, or IFFCO, and from Coromandel International, which began supply in April 2026. The company said freight on more distant supplies is rising with fuel prices.
The board declared an interim FY27 dividend of Rs 2.50 per equity share. During H1FY27, Alufluoride paid Rs 3.1 crore as the FY26 final dividend of Rs 4.00 per share, which shareholders approved at the 32nd annual general meeting on 16 July 2026.
Conclusion
Alufluoride’s Q2FY27 result shows that easing of the FSA constraint restored production and lifted revenue to Rs 63.9 crore, while lower material costs helped PAT rise to Rs 15.2 crore. The quarter reversed much of the Q1 disruption, although H1 revenue of Rs 90.5 crore remained 8% below the prior-year period.
The next reported variables are FSA availability and delivered cost, particularly freight on distant supply routes, because management identified them as continuing issues. Alufluoride also said its favourable-cost alumina hydrate inventory will be consumed over time, reducing that specific material-cost benefit, while its expanded 24,000-tonne annual capacity is available for the second half.