










Amanta Healthcare Ltd. Q2 FY27 PAT rises 303% as revenue grows 17%
Key highlights
- Amanta reported Q2 FY27 revenue of Rs 83 crore, up 17% from Rs 71 crore in Q2 FY26.
- Q2 FY27 EBITDA was Rs 18 crore, up 22%, and the EBITDA margin was 22%.
- Q2 FY27 PAT was Rs 5 crore, up 303% from Rs 1 crore, after Q2 FY26 included a Rs 3 crore exceptional item.
- SteriPort capacity rose 75% to 11.6 crore bottles after Line 3 was commissioned in September 2026.
powered by IRIS
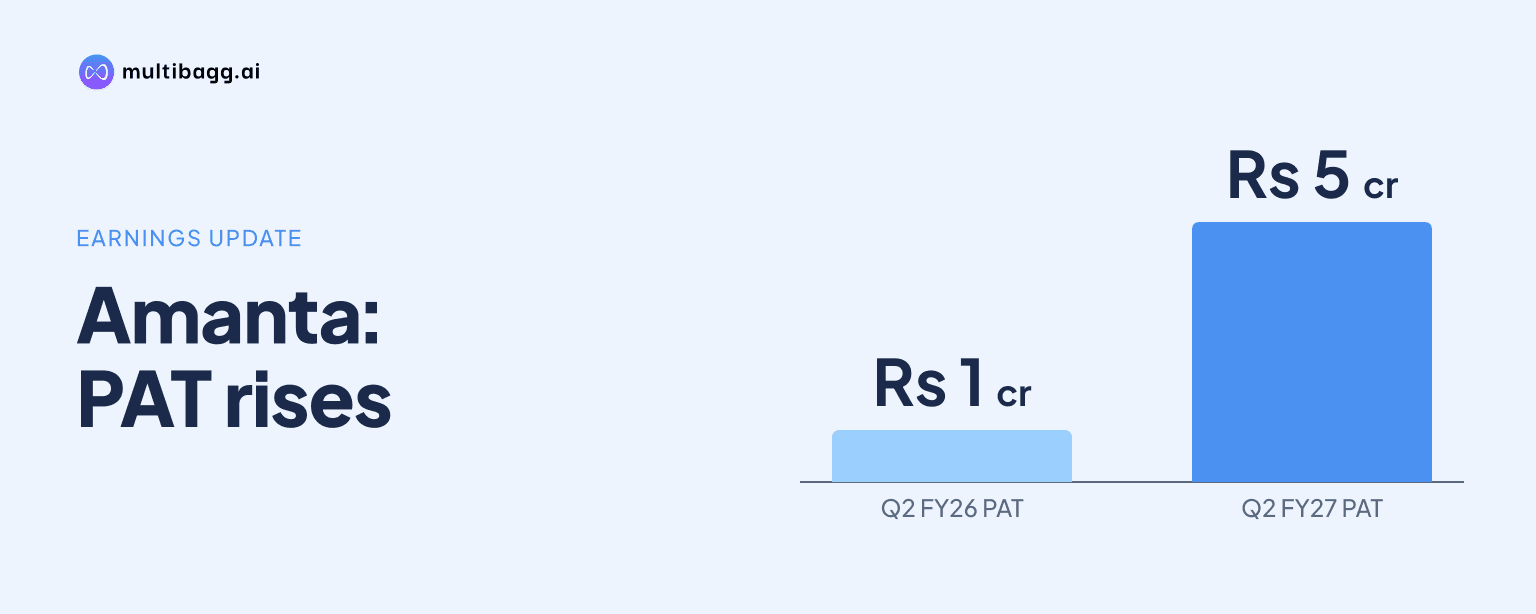
Amanta Healthcare Ltd. reported second-quarter fiscal year 2027 (Q2 FY27) profit after tax (PAT) of Rs 5 crore, up 303% year on year, as revenue rose 17% to Rs 83 crore and earnings before interest, tax, depreciation and amortisation (EBITDA) increased 22% to Rs 18 crore.
Know Amanta Healthcare inside out
Results, valuation, peers and who's buying, in one view.
How did Amanta perform in Q2 FY27?
Amanta delivered higher revenue, EBITDA and PAT in Q2 FY27 than in both Q2 FY26 and Q1 FY27. Revenue was Rs 83 crore in Q2 FY27, against Rs 71 crore a year earlier and Rs 69 crore in Q1 FY27. EBITDA was Rs 18 crore, compared with Rs 15 crore in each comparison quarter.
PAT reached Rs 5 crore in Q2 FY27, versus Rs 1 crore in Q2 FY26 and Rs 3 crore in Q1 FY27. The reported PAT margin was 6%, compared with 2% a year earlier and 5% in Q1 FY27. The financial-highlights page gives more precise figures of Rs 83.13 crore revenue, Rs 17.95 crore EBITDA and Rs 4.86 crore PAT, while the detailed statement rounds the same items to whole crores.
The year-on-year increase in revenue was 17%, while EBITDA grew 22%, according to the detailed statement. EBITDA margin moved to 22% from 21% in Q2 FY26 and was unchanged from Q1 FY27. Sequentially, revenue increased Rs 14 crore from Q1 FY27, while EBITDA increased Rs 3 crore and PAT rose Rs 2 crore.
What drove Amanta’s EBITDA increase?
Amanta’s Q2 FY27 EBITDA increased because total income grew 18% to Rs 84 crore while total expenditure rose 17% to Rs 66 crore. Revenue supplied Rs 83 crore of total income and other income contributed Rs 1 crore. The resulting EBITDA of Rs 18 crore compared with Rs 15 crore in Q2 FY26.
Cost of materials consumed increased 17% year on year to Rs 28 crore, matching revenue growth. Employee costs rose 11% to Rs 12 crore, while other expenses declined 5% to Rs 21 crore from Rs 22 crore. Purchases of stock-in-trade fell 38% to Rs 1 crore, although changes in inventories moved to an expense of Rs 4 crore from a Rs 2 crore credit in Q2 FY26.
Below EBITDA, finance costs increased 13% to Rs 6 crore and depreciation and amortisation expenses also increased 13% to Rs 5 crore. Even after those increases, profit before tax before exceptional items rose 39% to Rs 7 crore from Rs 5 crore. The quarterly result therefore reflects the change in operating income and expenses as well as charges after EBITDA.
Got a follow-up? Ask IRIS
Why was Amanta’s PAT comparison much larger than revenue growth?
Amanta’s 303% PAT growth comparison was amplified by a Rs 3 crore exceptional item recorded in Q2 FY26 that was absent in Q2 FY27. Profit before tax before exceptional items rose from Rs 5 crore to Rs 7 crore, a 39% increase. After the Q2 FY26 exceptional item, reported profit before tax was Rs 2 crore, compared with Rs 7 crore in Q2 FY27.
Tax rose to Rs 2 crore in Q2 FY27 from Rs 1 crore in Q2 FY26, and PAT consequently rose to Rs 5 crore from Rs 1 crore. The detailed profit and loss statement labels this as 303% year-on-year PAT growth. The strategic-highlights page separately describes Q2 FY27 PAT growth as 26% year on year, a figure that differs from the detailed statement and is not reconciled in the supplied material.
The same exceptional-item distinction appears in the first half (H1). H1 FY27 revenue increased 12% to Rs 152 crore from Rs 136 crore, while EBITDA increased 8% to Rs 33 crore from Rs 31 crore. H1 FY27 PAT was Rs 8 crore, up 73% from Rs 5 crore, while H1 FY26 included a Rs 3 crore exceptional item and H1 FY27 had none.
What capacity and cost plans does Amanta disclose after Q2 FY27?
Amanta says SteriPort Line 3 was commissioned in the first week of September 2026 at its existing Khed facility, increasing SteriPort capacity by 75% from 6.6 crore to 11.6 crore bottles. Management expects about Rs 60 crore of FY27 revenue from the line and Rs 110 crore to Rs 120 crore annually at optimal utilisation. The presentation identifies full ramp-up within 12 months as a milestone.
The next disclosed expansion is small-volume parenteral (SVP) capacity. Amanta plans to raise SVP capacity from 20.9 crore to 31.7 crore units during Q1 FY28, an addition of 10.8 crore units, or 52%. The company says the expansion adds inhalation, ophthalmics and diluents in its highest-margin segment, which it identifies as having EBITDA margins of 22% to 27%.
Amanta also states that its 10.8-megawatt captive solar facility has generated power since the end of Q1 FY27 and is expected to save about Rs 9 crore annually. Management says new lines will share existing infrastructure, workforce and utilities, and has set a two-year aim of revenue compound annual growth above 20% and EBITDA margin above 25%.
At H1 FY27, property, plant and equipment stood at Rs 312 crore, up from Rs 197 crore at FY26, while capital work-in-progress moved from Rs 82 crore to nil. Total assets were Rs 529 crore at H1 FY27, compared with Rs 558 crore at FY26. Non-current borrowings fell from Rs 162 crore to Rs 49 crore, while current borrowings rose from Rs 72 crore to Rs 147 crore.
Conclusion
Amanta’s Q2 FY27 results combined 17% revenue growth to Rs 83 crore with 22% EBITDA growth to Rs 18 crore and PAT of Rs 5 crore. The much larger 303% reported PAT increase was affected by the Rs 3 crore exceptional item in Q2 FY26, while profit before tax before exceptional items increased 39% from Rs 5 crore to Rs 7 crore.
The next disclosed milestones are the targeted approximately Rs 60 crore FY27 revenue contribution from SteriPort Line 3, its full ramp-up within 12 months, and the SVP expansion planned for Q1 FY28. Management’s two-year aims of revenue compound annual growth above 20% and EBITDA margin above 25%, alongside expected annual solar savings of about Rs 9 crore, are the disclosed measures to watch next.