










Amanta SteriPort capacity rises 75% after September Line 3
Key highlights
- Amanta commissioned SteriPort Line 3 in the first week of September 2026.
- SteriPort capacity increased 75%, from 6.6 crore to 11.6 crore bottles.
- Amanta expects about Rs 60 crore of FY27 revenue from SteriPort Line 3.
- SVP capacity is planned to rise 52% to 31.7 crore units in Q1 FY28.
powered by IRIS
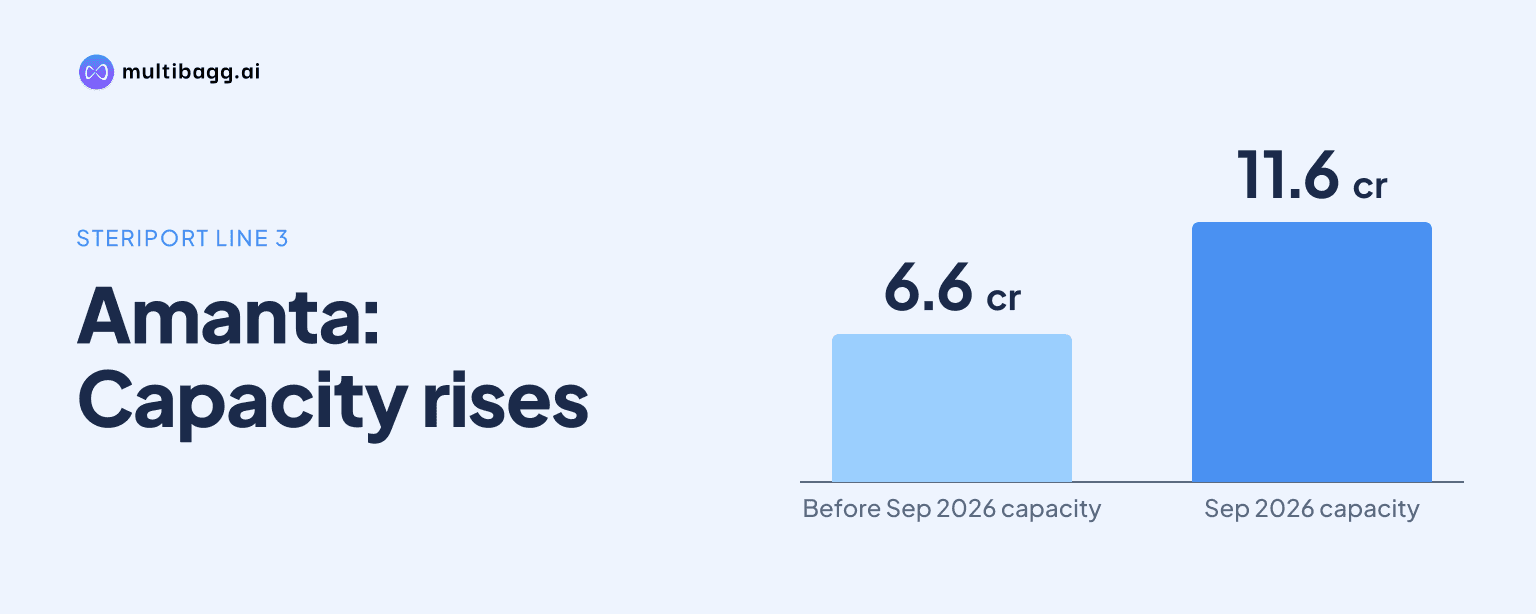
Amanta Healthcare Limited commissioned SteriPort Line 3 in the first week of September 2026, raising SteriPort capacity by 75% from 6.6 crore to 11.6 crore bottles and targeting about Rs 60 crore of FY27 revenue from the line. Amanta also plans a 52% small-volume parenteral capacity increase in Q1 FY28.
Know Amanta Healthcare inside out
Results, valuation, peers and who's buying, in one view.
What changed after Amanta commissioned SteriPort Line 3?
Amanta added 5.0 crore bottles of SteriPort capacity through Line 3 at its existing Khed facility, taking total capacity from 6.6 crore to 11.6 crore bottles in September 2026. The company identifies this as a 75% capacity increase and lists the project as a completed milestone in its FY27 growth plan.
SteriPort is Amanta’s established generic brand, and the additional line expands its sterile-liquid manufacturing base. Amanta operates a Gujarat facility spanning 66,852 square metres and reports four large-volume parenteral, or LVP, lines, including SteriPort lines using injection stretch blow moulding technology.
The Line 3 addition is one of two disclosed manufacturing projects. Amanta says the new lines will share existing infrastructure, workforce and utilities, which management presents as a fixed-cost leverage mechanism. The presentation does not disclose the project cost, Line 3 utilisation after commissioning, or actual sales generated during September 2026.
How much revenue does Amanta expect from SteriPort Line 3?
Amanta expects SteriPort Line 3 to contribute about Rs 60 crore of revenue in FY27 and Rs 110 crore to Rs 120 crore a year at optimal utilisation. The company also states that the line is expected to reach full ramp-up within 12 months of its September 2026 commissioning.
These figures are management estimates rather than reported revenue. Amanta has not disclosed Line 3 sales, customer orders, product mix or profitability, so the conversion of its additional 5.0 crore bottles of capacity into the FY27 revenue target cannot yet be measured from the presentation.
The capacity plan follows revenue growth in the reported business. Q2 FY27 revenue was Rs 83.13 crore, up 17.3% year on year, while H1 FY27 revenue was Rs 151.94 crore. The rounded profit-and-loss statement shows revenue rising by Rs 12 crore in Q2 and Rs 16 crore in H1.
Amanta has set a two-year aim of revenue compound annual growth rate, or CAGR, above 20% and earnings before interest, tax, depreciation and amortisation, or EBITDA, margin above 25%. The Line 3 revenue estimate and the planned small-volume parenteral project are disclosed alongside that aim, but the presentation does not state that either target is assured.
Got a follow-up? Ask IRIS
When will Amanta expand its SVP capacity?
Amanta plans to increase small-volume parenteral, or SVP, capacity from 20.9 crore to 31.7 crore units during Q1 FY28, an addition of 10.8 crore units and a 52% increase. This is the next scheduled capacity milestone after SteriPort Line 3 went live in September 2026.
Management says the SVP expansion will add capacity for inhalation products, ophthalmics and diluents. It describes SVP as its highest-margin segment, with EBITDA margin of 22% to 27%, although the presentation provides no SVP segment revenue, EBITDA amount or revenue target for the planned expansion.
Amanta currently lists three SVP lines with capacity of 20.91 crore units: two aseptic blow-fill-seal, or ABFS, lines and one conventional three-piece-container line. The planned Q1 FY28 project would raise output capacity in product categories that overlap with Amanta’s respiratory care, ophthalmic and diluent therapeutic segments.
The presentation gives no capital expenditure figure for the SVP project and does not identify regulatory approvals, customer commitments or intended utilisation levels. The Q1 FY28 timing is therefore a management-disclosed operational plan, while execution and financial contribution remain matters to be established.
How did Amanta's quarterly earnings and cost measures change?
Amanta reported Q2 FY27 EBITDA of Rs 17.95 crore and profit after tax, or PAT, of Rs 4.86 crore, with EBITDA margin of 21.6% and PAT margin of 6%. Its strategic highlights state that Q2 revenue rose 17.3% year on year to Rs 83.13 crore and PAT rose 26% on that basis.
The rounded financial statement shows Q2 EBITDA increasing from Rs 15 crore in Q2 FY26 to Rs 18 crore in Q2 FY27, while PAT increased from Rs 1 crore to Rs 5 crore. For H1 FY27, EBITDA was Rs 33 crore against Rs 31 crore a year earlier, and PAT rose from Rs 5 crore to Rs 8 crore; the H1 FY26 period included Rs 3 crore of exceptional items.
Quarter on quarter, rounded Q2 FY27 revenue of Rs 83 crore exceeded Q1 FY27 revenue of Rs 69 crore. EBITDA rose from Rs 15 crore to Rs 18 crore, while EBITDA margin remained 22% in both quarters; PAT increased from Rs 3 crore to Rs 5 crore and PAT margin moved from 5% to 6%.
Amanta also commissioned a 10.8-megawatt captive solar facility by the end of Q1 FY27 and expects annual power savings of about Rs 9 crore. Its debt-to-equity ratio declined from 3.50 times in FY23 to 1.07 times in FY26, according to the company overview, although the H1 FY27 balance sheet shows cash and cash equivalents of Rs 2 crore compared with Rs 81 crore at FY26.
Conclusion
Amanta’s September 2026 SteriPort Line 3 commissioning lifted bottle capacity by 5.0 crore to 11.6 crore bottles, creating the capacity base for management’s estimate of about Rs 60 crore of FY27 revenue. The project sits alongside Q2 FY27 revenue growth of 17.3%, a 10.8-megawatt solar project expected to save about Rs 9 crore annually, and the company’s stated two-year targets for revenue growth and EBITDA margin.
The next disclosed event is the planned Q1 FY28 SVP expansion, which is intended to add 10.8 crore units of capacity. Investors will need to watch Line 3’s progress toward full ramp-up within 12 months, the delivery against its Rs 110 crore to Rs 120 crore optimal-utilisation revenue estimate, and whether the SVP project becomes operational on the announced schedule.