










Amber says rail margins rebound only in FY28 after old projects
Key highlights
- Amber's Railway Sub-systems & Defence Division reported a 4.9% operating EBITDA margin in Q2 FY27, down from 16.2% in Q2 FY26.
- Q2 FY27 division revenue rose 15% year on year to Rs 152 crore, while operating EBITDA fell 65% to Rs 7 crore.
- Amber expects FY27 division revenue growth of around 15% to 20%, with project delays affecting the outlook.
- Amber reported more than Rs 2,750 crore of order-book visibility for Railway Sub-systems & Defence.
powered by IRIS
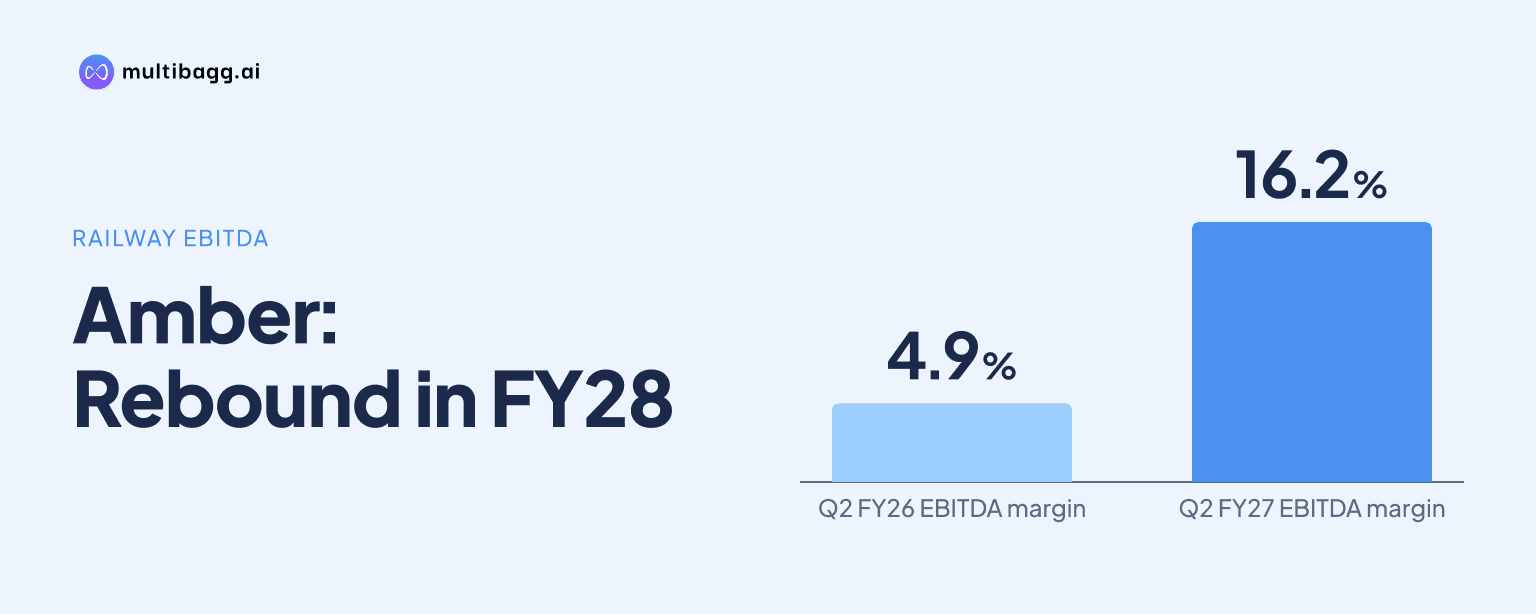
Amber expects its Railway Sub-systems & Defence Division operating earnings before interest, tax, depreciation and amortisation, or operating EBITDA, margin to return to normalized levels in FY28 after old projects are delivered, following a Q2 FY27 margin of 4.9% versus 16.2% a year earlier. Division revenue nevertheless rose 15% year on year to Rs 152 crore in the quarter.
Know Amber Enterprises India inside out
Results, valuation, peers and who's buying, in one view.
Why are Amber's rail margins expected to recover only in FY28?
Amber says margins are expected to rebound to normalized levels in FY28 because old projects must first be delivered. The division reported Q2 FY27 operating EBITDA of Rs 7 crore, down 65% from Rs 21 crore in Q2 FY26, while the operating EBITDA margin fell 11.3 percentage points to 4.9% from 16.2%.
Management attributed the Q2 FY27 margin pressure to fixed-price contracts, commodity inflation, foreign-currency fluctuation and a minimum-wage revision in Haryana. These are disclosed cost and contract effects rather than a fall in quarterly revenue: Railway Sub-systems & Defence Division revenue increased from Rs 132 crore in Q2 FY26 to Rs 152 crore in Q2 FY27. Amber's FY28 timing therefore depends on completing the old projects that management identifies as the source of the current margin burden.
The first-half trend shows that the pressure was not confined to one quarter. H1 FY27 operating EBITDA declined to Rs 24 crore from Rs 43 crore in H1 FY26, and the margin decreased to 8.0% from 17.0%, even as revenue increased 16% to Rs 297 crore from Rs 255 crore. Higher sales and lower operating EBITDA are the central features of the division's disclosed outlook.
What revenue growth does Amber expect for FY27?
Amber expects Railway Sub-systems & Defence Division revenue growth of around 15% to 20% in FY27, with project delays affecting the outcome. The division generated Rs 297 crore of revenue in H1 FY27, compared with Rs 255 crore in H1 FY26, and its Q2 FY27 revenue was Rs 152 crore, compared with Rs 132 crore a year earlier.
The reported Q2 FY27 growth rate was 15%, placing the quarter at the lower end of management's stated 15% to 20% full-year growth expectation. Revenue was Rs 124 crore in Q2 FY25 and Rs 219 crore in H1 FY25, compared with Rs 132 crore and Rs 255 crore respectively in FY26. That comparison shows growth from the FY25 base, while the FY27 forecast explicitly incorporates project delays.
The presentation says the division's revenue and operating EBITDA figures are not comparable with published segment results. It defines operating EBITDA as before employee stock option plan expenses and other non-operating income and expenses. The Rs 7 crore Q2 FY27 and Rs 24 crore H1 FY27 figures are therefore the management measures used in its margin-recovery outlook rather than necessarily statutory segment-profit measures.
How large is Amber's Railway Sub-systems & Defence order book?
Amber reports Railway Sub-systems & Defence order-book visibility of more than Rs 2,750 crore. The presentation does not provide a split by customer, delivery year, product or contract pricing, so it does not establish how much of the order book will be executed during FY27 or FY28.
The order-book figure accompanies product expansion across railway and metro heating, ventilation and air conditioning, or HVAC, micro-processor controllers, pantry systems, doors, gangways, couplers, pantographs, driving gears and brakes. Beyond railways, the listed offerings are defence HVAC, data-centre HVAC and bus HVAC. The disclosed portfolio is wider than the FY20 starting point of HVAC shown in the product-expansion timeline.
H1 FY27 revenue of Rs 297 crore was Rs 42 crore higher than the Rs 255 crore reported in H1 FY26, while Q2 revenue increased by Rs 20 crore year on year to Rs 152 crore. Amber has not disclosed an order-book conversion rate, cancellations, project milestones or an annual revenue schedule for the more than Rs 2,750 crore figure.
Got a follow-up? Ask IRIS
Which new rail products and facilities is Amber adding?
Amber is adding doors and gangways through technology transfer, while its joint venture with Yujin Machinery is developing couplers, pantographs, driving gears and brakes. The Sidwal greenfield facility is operational, with its production capacity being scaled up to support future growth.
The Yujin joint-venture facility is ready, but commercial production remains conditional on product development, design work and requisite Research Designs and Standards Organisation, or RDSO, approval. Amber anticipates commercial production from the facility in H2 FY27 following that approval. This is a disclosed future plan rather than reported production or revenue.
The division's portfolio includes railway and metro HVAC, which was the sole product category shown for FY20, alongside newer railway components and systems in FY27. The addition of doors, gangways, couplers, pantographs, driving gears and brakes broadens the stated offering, but the presentation provides no separate revenue, margin or order-book values for individual product categories.
How did Amber's rail revenue and profitability change in Q2 FY27?
Amber's Q2 FY27 revenue rose to Rs 152 crore from Rs 132 crore, but operating EBITDA fell to Rs 7 crore from Rs 21 crore. The quarter's 15% revenue growth therefore coincided with a 65% decline in operating EBITDA and a margin reduction from 16.2% to 4.9%.
The multi-year comparison also shows the profitability change. Q2 operating EBITDA was Rs 31 crore, or 23.5% of revenue, in Q2 FY24; it was Rs 21 crore, or 17.0%, in Q2 FY25; and it remained Rs 21 crore, or 16.2%, in Q2 FY26 before declining to Rs 7 crore in Q2 FY27. Revenue, by contrast, rose from Rs 132 crore in Q2 FY24 to Rs 152 crore in Q2 FY27.
At the consolidated level, Amber reported Q2 FY27 operating EBITDA of Rs 127 crore on revenue of Rs 2,627 crore, producing a 4.8% operating EBITDA margin. That consolidated margin was 5.9% in Q2 FY26, while the Railway Sub-systems & Defence Division's margin fell to 4.9% from 16.2%. These measures are not directly interchangeable because Amber separately notes that division operating figures are not comparable with published segment results.
Conclusion
Amber's Railway Sub-systems & Defence Division combines more than Rs 2,750 crore of reported order-book visibility and an expanded rail product range with a near-term profitability constraint. Revenue increased 15% in Q2 FY27 and 16% in H1 FY27, but fixed-price contracts, commodity inflation, foreign-currency movements and Haryana wage revisions reduced operating EBITDA to Rs 7 crore in the quarter and Rs 24 crore in the half year.
The next disclosed milestones are management's FY27 revenue-growth expectation of around 15% to 20%, progress on delayed projects, delivery of old projects, and anticipated H2 FY27 commercial production at the Yujin joint venture after RDSO approval. Management has placed the margin-normalization point in FY28, making execution of those projects and approvals the stated matters to watch.