










Anawil Targets Rs 450-500 Crore FY27 Revenue After H1 Surge
Key highlights
- Anawil reported H1FY27 revenue from operations of Rs 153.97 crore, up 272.2% year on year.
- Anawil's confirmed order book was Rs 395.58 crore, excluding Rs 44.05 crore of LOIs.
- Anawil guided for FY27 revenue of Rs 450-500 crore and PAT of Rs 55-60 crore.
- Anawil produced 107 towers in H1FY27, up 72.6% year on year.
powered by IRIS
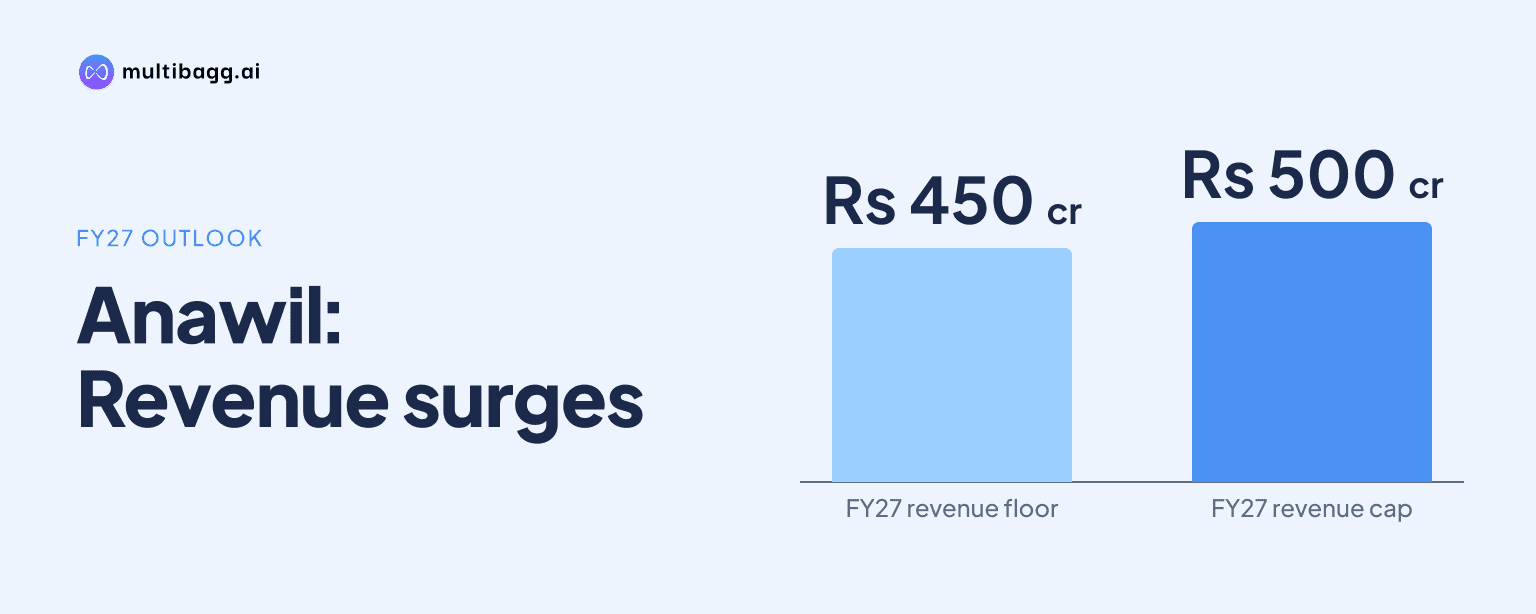
Anawil Wire & Engineering Limited has guided for FY27 revenue of Rs 450-500 crore after reporting Rs 153.97 crore of revenue from operations in H1FY27, with a Rs 395.58 crore confirmed order book targeted for execution by the end of Q1FY28. Management expects higher second-half execution as Kutch trial runs continue.
Know Anawil Wire and Engineering inside out
Results, valuation, peers and who's buying, in one view.
What is Anawil's FY27 revenue and profit target?
Anawil has guided for FY27 revenue of Rs 450-500 crore and profit after tax, or PAT, of Rs 55-60 crore. Management linked this outlook to stronger H2FY27 tower execution, increased utilisation and the existing confirmed order book, in its results release for the half year ended September 30, 2026.
H1FY27 revenue of Rs 153.97 crore means a larger volume of work must be executed in the remaining half of FY27 to meet the stated range. Management said the first half is typically seasonally softer than H2 for tower production and expects a significant H2FY27 pick-up, subject to planned order execution and capacity ramp-up.
H1FY27 revenue of Rs 153.97 crore exceeded Anawil's full-year FY26 revenue of Rs 143.27 crore. While this compares six months with a full financial year, Anawil attributed the increase to production of 107 towers, up 72.6% year on year, and higher realisations from integrated supply contracts.
How much of Anawil's order book is confirmed?
Anawil's confirmed order book stood at Rs 395.58 crore, excluding letters of intent, or LOIs, worth Rs 44.05 crore. The company has targeted execution of the confirmed order book by the end of Q1FY28, its disclosed timetable for converting contracted work into revenue.
Model 3 represented 51.3% of the confirmed order book, compared with 24.5% for Model 1 and 24.2% for Model 2. The mix differs from H1FY27 revenue, in which Model 3 contributed 64.3%, Model 1 contributed 21.2%, Model 2 contributed 10.8% and other business contributed 3.7%.
The reported mix means Model 2 accounts for a greater share of future confirmed work, at 24.2%, than it did of H1FY27 revenue, at 10.8%. The Rs 44.05 crore of LOIs is separate from the Rs 395.58 crore confirmed-order figure, and the release does not identify customers, delivery schedules or order dates.
Why does Anawil expect stronger execution in H2FY27?
Anawil expects stronger H2FY27 execution because management describes H1 as seasonally softer for tower production and has a Rs 395.58 crore confirmed order book. Tower output reached 107 units in H1FY27, up 72.6% year on year, while the company expects order execution to increase in the second half.
The Kutch, Gujarat capacity expansion was nearing completion, with trial runs under way as of November 6, 2026. Anawil did not disclose the project's incremental tower capacity or commercial-operation date, but said its Kutch and Koppal, Karnataka facilities together have annual capacity of 612 towers and can manufacture customised towers of up to 140 metres.
Management also cited in-house kits manufacturing at Koppal as a backward-integration measure supporting operational self-reliance. The release gives no separate revenue, cost-saving or capacity figure for kits manufacturing, so its expected contribution remains part of management's plan to scale production and undertake larger orders.
Got a follow-up? Ask IRIS
What happened to Anawil's profitability in H1FY27?
Anawil reported H1FY27 EBITDA of Rs 36.08 crore, up 255.8% year on year, and PAT of Rs 14.39 crore, up 539.3%. EBITDA margin was 23.4% and PAT margin was 9.3%, with management attributing the margin profile partly to its contract mix.
Model 3 contracts include materials and carry relatively lower percentage margins, according to management, although they generate higher absolute EBITDA per tower. Model 3 accounted for 64.3% of H1FY27 revenue, making it Anawil's largest first-half revenue model and a key factor in the reported mix.
Anawil reported EBITDA per tower of Rs 32.82 lakh, up 104.7% year on year and 14.8% from FY26. Management uses the measure because material requirements differ across models, and said initial operating expenses at Kutch limited further improvement before the plant's full ramp-up.
What needs to happen for Anawil to meet its FY27 plan?
Anawil needs to convert its Rs 395.58 crore confirmed order book into production and revenue while raising Kutch utilisation after trial runs. The company aims to execute the existing confirmed orders by the end of Q1FY28, while management expects H2FY27 to be stronger than the seasonally softer first half.
Kutch's expanded capacity and Koppal's in-house kits manufacturing are intended to support production scale and larger orders. Initial Kutch operating expenses affected H1FY27 profitability, according to management, so the pace of utilisation is relevant to both revenue execution and the expected improvement in cost absorption; no quarterly utilisation target was disclosed.
The Rs 450-500 crore revenue range and Rs 55-60 crore PAT range are management guidance, not reported results. The November 6, 2026 release cautions that forward-looking statements are subject to risks and uncertainties, including government actions and local, political, economic and technological developments.
Conclusion
Anawil's H1FY27 results combined Rs 153.97 crore of revenue, Rs 36.08 crore of EBITDA, Rs 14.39 crore of PAT and 107 towers produced. The Rs 395.58 crore confirmed order book provides the disclosed execution base, while Model 3 was the largest contributor to both H1FY27 revenue, at 64.3%, and confirmed orders, at 51.3%.
The next disclosures to watch are progress on Kutch trial runs and utilisation, alongside execution against the end-Q1FY28 order-book target. Management's FY27 guidance of Rs 450-500 crore in revenue and Rs 55-60 crore in PAT depends on the anticipated H2FY27 increase in execution, cost absorption at Kutch and the planned operational contribution from Koppal kits manufacturing.