










Anupam Rasayan expects Rs 100-150 crore from U.S. deal
Key highlights
- Anupam Rasayan expects Rs 100-150 crore of current-year revenue from its six-year U.S. specialty-metals contract.
- Anupam Rasayan commercialised the customer’s product in four months and plans to start supplies in November 2026.
- Anupam Rasayan reported Q2 FY27 consolidated EBITDA of Rs 202 crore, up 41% year on year.
- Management said the U.S. contract’s monthly revenue run rate could double over the next 12 to 18 months.
powered by IRIS
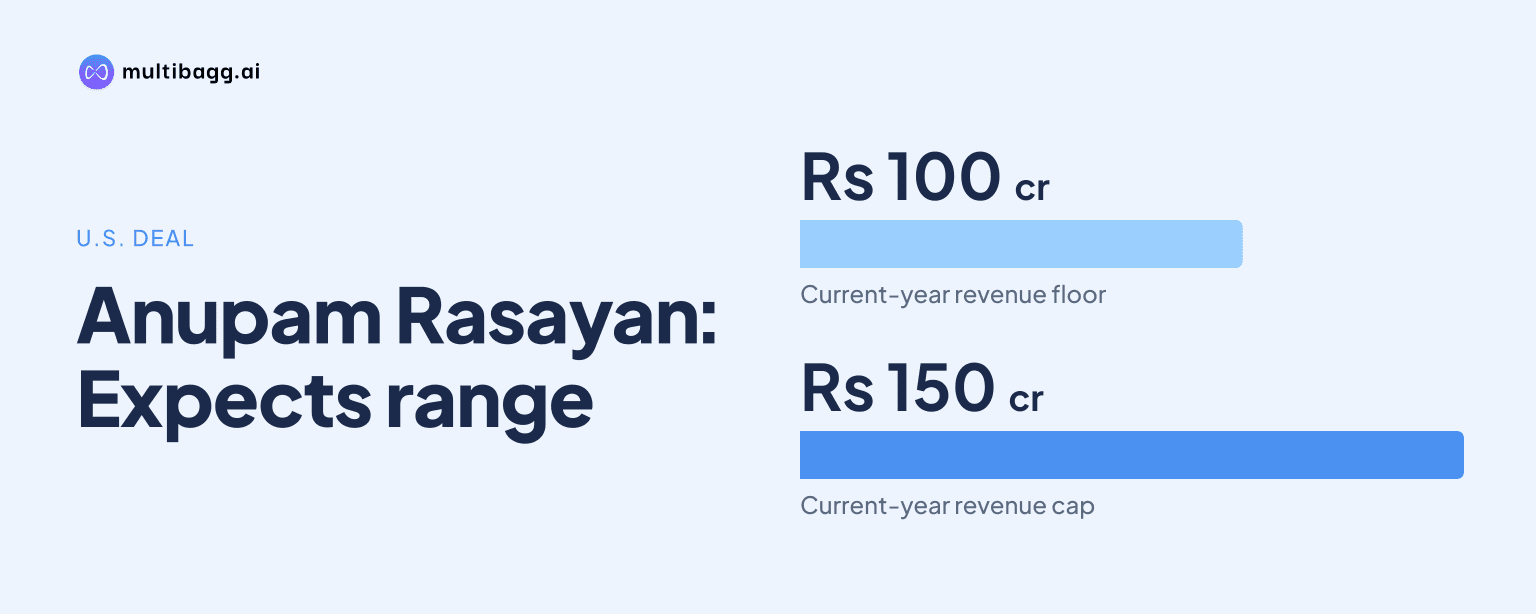
Anupam Rasayan India Limited expects Rs 100-150 crore of revenue in the current year from its six-year supply agreement with a U.S.-based specialty metal manufacturer, with supplies scheduled to start in November 2026. Management said it commercialised the customer’s product in four months and expects the monthly revenue run rate to increase materially over the next year to 18 months.
Know Anupam Rasayan India inside out
Results, valuation, peers and who's buying, in one view.
What does Anupam Rasayan’s U.S. supply agreement cover?
Anupam Rasayan signed a six-year long-term supply agreement in Q2 FY27 with a leading U.S.-based global specialty metal manufacturer, entering a new segment within geological resources. Management did not identify the customer, product, contract value, volumes or pricing, but said the agreement expands its customer base into specialised industrial applications.
The agreement sits outside the three revenue categories reported for Q2 FY27. Life science-related specialty chemicals accounted for 42% of revenue, Performance Materials for 28%, and other fluorinated products for 29%. Management described the company as sector-agnostic because it applies chemistry and manufacturing capabilities across customer end markets.
Management said the opportunity had been offered to some peers, but Anupam Rasayan developed the product within the customer’s required timeline. It attributed the contract conversion to the technical team’s process-development work, capital expenditure already in place, multipurpose manufacturing plants and its practice of retaining some available capacity for new opportunities.
The contract was announced alongside a broader effort to diversify beyond agrochemicals. Management said it is increasing the contribution of pharmaceuticals and Performance Materials, while commercialising its product-development pipeline and adding specialised industrial applications to its customer portfolio.
How quickly did Anupam Rasayan commercialise the new product?
Anupam Rasayan commercialised the specialty-metals product in four months and said product approval took about three months from the initial customer inquiry. Management said the customer had an urgent requirement and planned to begin taking supply volumes in November 2026.
The company said ready capacity was an important part of the timeline. Its multipurpose plants allowed production to be ramped without management disclosing a new dedicated facility for the contract. The transcript does not state the capacity allocated to the agreement, whether the initial November supplies represent full output, or whether further capital expenditure will be required.
Management also linked the development speed to its established process chemistry capabilities. It said that the product was technically challenging enough to have been evaluated by peers, but did not disclose the chemistry involved, the raw materials used or whether its fluorination and continuous-flow capabilities are part of this specific contract.
Anupam Rasayan cited commercialisation of ethyl tetrafluoroethylene, or ETFA, through continuous-flow chemistry as a separate technology milestone. However, management did not say that ETFA is the product being supplied to the U.S. specialty metal customer, so the two developments should be treated separately.
Got a follow-up? Ask IRIS
How much revenue does Anupam Rasayan expect from the agreement?
Anupam Rasayan expects Rs 100-150 crore of revenue from the U.S. agreement in the current year, with management allowing for variation of a few tens of crores. It said the monthly run rate could double over the following year to year and a half, but did not give a total revenue forecast for the six-year contract.
The current-year estimate is meaningful against the group’s reported scale, though the periods are not directly comparable. Anupam Rasayan reported consolidated total income of Rs 1,489 crore in H1 FY27, while the contract estimate relates to the remaining period after the planned November 2026 supply start.
Management’s wider H2 FY27 target of Rs 2,400-2,500 crore of consolidated revenue includes contributions from Anupam Rasayan, Jayhawk Fine Chemicals, Tanfac Industries and Bliss GVS Pharma. It said this would imply an annualised revenue run rate of around Rs 4,800-5,000 crore, rather than a forecast solely linked to the U.S. contract.
The company separately reported a cumulative standalone portfolio of letters of intent and long-term contracts of about Rs 17,496 crore. Management said dividing that portfolio across six to seven years indicates an average annual opportunity of about Rs 2,500 crore, and it expected delivery from this portfolio to rise to about 1.8 to 2 times the roughly Rs 350 crore achieved in the prior year.
How does the U.S. agreement fit Anupam Rasayan’s financial and expansion plans?
Anupam Rasayan reported Q2 FY27 consolidated total income of Rs 821 crore, up 11% from Rs 739 crore in Q2 FY26, while earnings before interest, tax, depreciation and amortisation, or EBITDA, increased 41% to Rs 202 crore from Rs 144 crore. Profit after tax rose 14% to Rs 65 crore from Rs 57 crore.
Consolidated EBITDA margin increased to about 25% in Q2 FY27 from 19.4% a year earlier. In H1 FY27, EBITDA rose 38% to Rs 377 crore from Rs 273 crore and margin increased to 25.5% from 22.2%. Management attributed the improvement primarily to product mix and a higher contribution from Performance Materials, rather than to the U.S. agreement, for which supplies are scheduled to begin in November.
Performance Materials represented 29% of H1 FY27 revenue, compared with 28% in Q2 FY27. Life science-related specialty chemicals moved from 42% in Q2 to 41% in H1, while other fluorinated products represented 29% in Q2 and 28% in H1. The one-percentage-point difference reflects a slightly higher Performance Materials share in the half-year mix.
The company is also integrating recent acquisitions. It completed the acquisition of approximately 50.07% of Bliss GVS Pharma on September 28, 2026, adding pharmaceutical formulations to its existing intermediates and custom-synthesis activities. Bliss GVS contributed only three days of revenue and operating performance to Q2 FY27 consolidated results, although its balance sheet was consolidated from the acquisition date.
Management said operating cash flow reached Rs 328 crore in H1 FY27, compared with Rs 334 crore for the previous full year. Excluding the Bliss GVS balance sheet, it said the working-capital cycle improved to 271 days from 276 days, while the group continues to focus on inventory, receivables and cash-flow management.
Conclusion
The six-year U.S. supply agreement gives Anupam Rasayan a disclosed entry into geological resources and a new specialised industrial application. The immediate financial contribution is management’s Rs 100-150 crore current-year estimate, while the strategic element is the reported four-month commercialisation timeline and the use of existing flexible manufacturing capacity to start supplies in November 2026.
The next point to watch is the pace of volumes after the November start and whether the monthly run rate develops in line with management’s indication of a potential doubling over the following 12 to 18 months. Management’s H2 FY27 consolidated revenue target of Rs 2,400-2,500 crore will also reflect fuller-period contributions from Bliss GVS Pharma and other group businesses.