










APM TERMINALS first-half EBITDA margin rises to 63% in FY27
Key highlights
- APM TERMINALS reported first-half FY27 EBITDA of Rs 425.803 crore, up 31% year on year.
- APM TERMINALS' reported first-half EBITDA margin rose to 63% from 59% in the prior-year half.
- First-half FY27 revenue rose 22% to Rs 670.919 crore while total expenditure increased 9% to Rs 245.116 crore.
- First-half container volume rose 10% to 361,603 TEUs, while RORO volume increased 24% to 123,926 units.
powered by IRIS
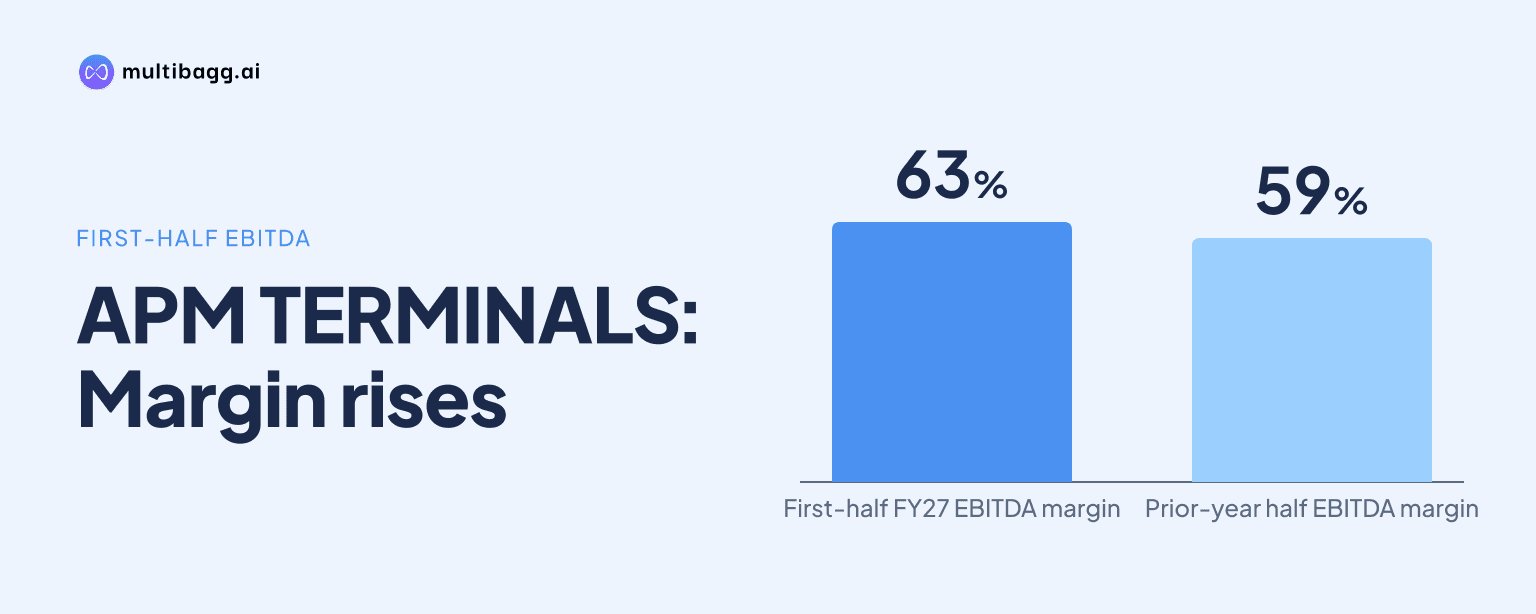
APM TERMINALS reported a 63% EBITDA margin for the half year ended September 2026, up from 59% a year earlier, as revenue rose 22% to Rs 670.919 crore while total expenditure increased 9% to Rs 245.116 crore. EBITDA consequently increased 31% to Rs 425.803 crore in first-half FY27.
Know Gujarat Pipavav Port inside out
Results, valuation, peers and who's buying, in one view.
How did APM TERMINALS expand its first-half EBITDA margin?
APM TERMINALS expanded its reported EBITDA margin by four percentage points because its first-half revenue increase exceeded the rise in total expenditure. Revenue from operations for the half year ended September 2026 was Rs 670.919 crore, compared with Rs 549.278 crore in the half year ended September 2025. Total expenditure was Rs 245.116 crore, against Rs 224.365 crore, leaving EBITDA of Rs 425.803 crore versus Rs 324.913 crore.
The resulting change was a 22% rise in revenue and a 31% increase in EBITDA, compared with a 9% increase in expenditure. EBITDA means earnings before interest, tax, depreciation and amortisation. In the reported profit and loss statement, the EBITDA-to-revenue ratio was 63% for the September 2026 half year, versus 59% for the comparable prior-year half year.
Which costs changed during the September 2026 half year?
APM TERMINALS' expenditure increased by Rs 20.751 crore in the first half, with employee benefits and other expenses accounting for most of the increase. Employee benefits expense rose 14% to Rs 51.863 crore from Rs 45.375 crore, while other expenses increased 13% to Rs 86.917 crore from Rs 76.704 crore. Operating expenses increased 4% to Rs 106.336 crore.
The mix differed in the September 2026 quarter, when total expenditure rose 5% year on year to Rs 127.332 crore and EBITDA increased 19% to Rs 211.820 crore. Operating expenses in that quarter were broadly unchanged year on year at Rs 62.648 crore, employee benefits rose 15% to Rs 26.313 crore, and other expenses increased 5% to Rs 38.371 crore. The quarterly EBITDA margin was 62%, compared with 59% in September 2025.
What volume trends supported APM TERMINALS' revenue growth?
APM TERMINALS recorded higher container and roll-on/roll-off volumes in the September 2026 half year, while dry bulk and liquid volumes declined. Container volume increased 10% to 361,603 twenty-foot equivalent units, or TEUs, and roll-on/roll-off, or RORO, volume rose 24% to 123,926 units. The presentation linked RORO growth to higher exports from original equipment manufacturers, or OEMs.
Dry bulk volume declined 9% to 1,463,053 metric tonnes and liquid volume declined 32% to 550,048 metric tonnes during the same period. The presentation linked the cargo trends to the Middle East conflict, citing transshipment volume in containers, lower fertiliser and mineral imports in bulk, and lower liquefied petroleum gas, or LPG, imports in liquid cargo. Despite the declines in two cargo categories, reported first-half revenue rose 22%.
The September 2026 quarter shows a similar contrast among segments. Container throughput rose 18% to 192,944 TEUs and RORO volume rose 3% to 58,515 units, while dry bulk fell 10% to 942,575 metric tonnes and liquid declined 15% to 328,868 metric tonnes. Within containers, non-inland container depot volume rose to 94,000 TEUs in September 2026 from 55,000 TEUs in September 2025, while inland container depot volume was 99,000 TEUs versus 109,000 TEUs.
Got a follow-up? Ask IRIS
How do reported and adjusted first-half performance measures differ?
APM TERMINALS reported 22% revenue growth, 31% EBITDA growth and 14% net-profit growth in the profit and loss statement for the September 2026 half year. Net profit was Rs 295.362 crore, compared with Rs 258.368 crore a year earlier, while earnings before interest and tax, or EBIT, increased 39% to Rs 363.288 crore. Depreciation decreased 1% to Rs 62.515 crore.
The key-updates page gives a separate comparison excluding duty benefit scrips and cyclone recovery. On that basis, the presentation states that revenue increased 16%, expenses rose 9%, EBITDA increased 21%, EBIT increased 27%, and margin was 62%, up 300 basis points. A basis point is one-hundredth of a percentage point, and this adjusted measure is not the same as the reported 63% margin in the profit and loss statement.
Other items also affected the difference between operating profit and net profit. Other income in the half year declined 19% to Rs 36.593 crore, finance cost declined 47% to Rs 1.759 crore, and there was no exceptional item, compared with an exceptional item of Rs 43.135 crore in the September 2025 half year. Profit before tax increased 15% to Rs 398.122 crore and tax expense increased 15% to Rs 101.143 crore.
What does the latest quarter show about the margin trend?
APM TERMINALS' September 2026 quarterly EBITDA margin was 62%, below 64% in the June 2026 quarter but above 59% in September 2025. Revenue from operations rose 2% sequentially to Rs 339.152 crore from Rs 331.767 crore in June 2026, while EBITDA declined 1% to Rs 211.820 crore from Rs 213.983 crore. Total expenditure increased 8% sequentially to Rs 127.332 crore.
Year on year, the September quarter produced a different result: revenue increased 13% from Rs 299.149 crore and EBITDA rose 19% from Rs 177.634 crore. EBIT increased 24% to Rs 180.717 crore. However, reported net profit fell 6% to Rs 148.485 crore because the September 2025 quarter included an exceptional item of Rs 43.135 crore, which was absent in September 2026.
Conclusion
APM TERMINALS' first-half figures show that revenue growth of 22% outpaced the 9% increase in expenditure, lifting reported EBITDA by 31% and the margin to 63% from 59%. Container and RORO volume gains coincided with lower dry bulk and liquid volumes, so the revenue increase occurred alongside a mixed cargo-volume pattern.
The next reported figures will show whether the September-quarter margin of 62%, below June's 64%, changes the first-half trajectory. The presentation identifies the unresolved Middle East conflict, lower fertiliser, mineral and LPG imports, and higher OEM exports as factors affecting cargo categories; it also separately reports measures excluding duty benefit scrips and cyclone recovery.