










Behari Lal Engineering Limited lifts high-value Q2 mix to 62.9%
Key highlights
- High-value products accounted for 62.9% of Behari Lal Engineering’s Q2 FY27 revenue, versus 57.8% in FY26.
- Q2 FY27 revenue from operations rose 21.7% year on year to Rs 154.2 crore.
- Q2 FY27 EBITDA margin, including other income, rose 74 basis points year on year to 17.9%.
- Behari Lal Engineering had a Rs 179.4 crore order book at September 30, 2026.
powered by IRIS
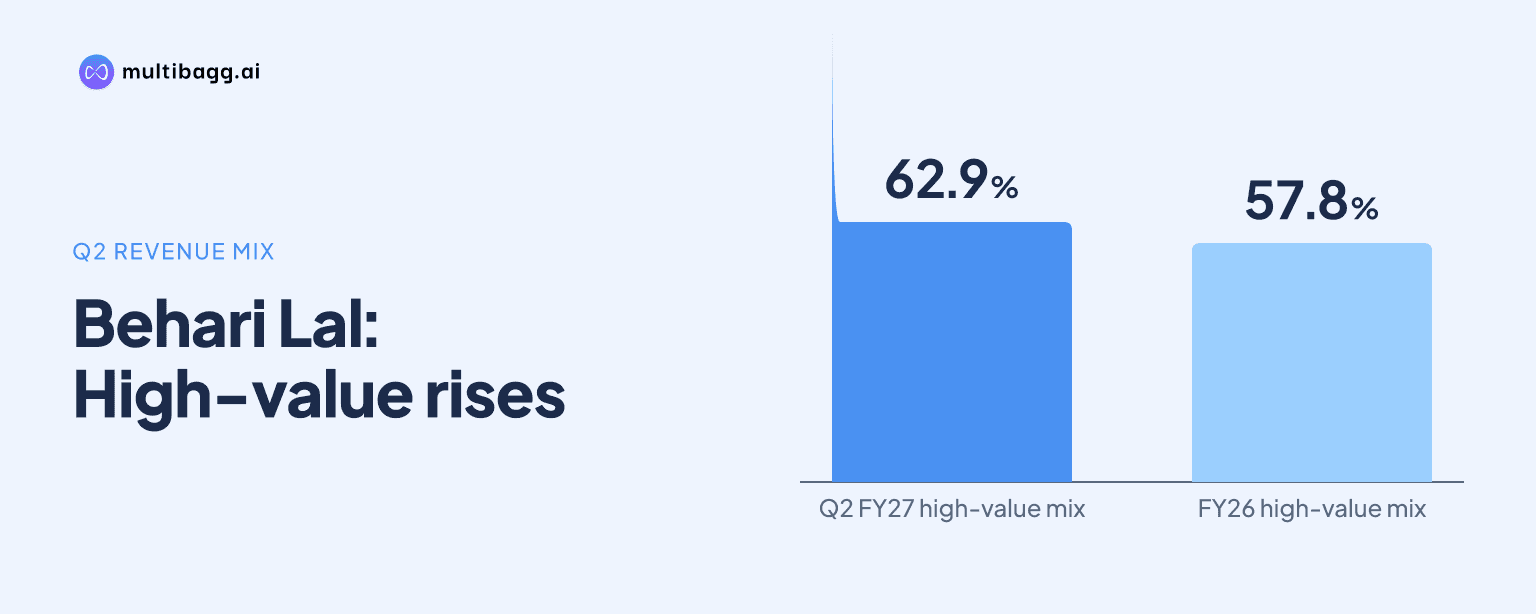
Behari Lal Engineering Limited reported that high-value products accounted for 62.9% of Q2 FY27 revenue, up from 60.4% in Q1 FY27 and 57.8% in FY26, helping the company maintain a 17.9% EBITDA margin, including other income, while scrap and alloy prices rose and selling-price resets lagged.
Know Behari Lal Engineering inside out
Results, valuation, peers and who's buying, in one view.
How did Behari Lal Engineering’s product mix change in Q2 FY27?
Behari Lal Engineering increased the high-value-product share of revenue to 62.9% in Q2 FY27, a rise of 2.5 percentage points from 60.4% in Q1 FY27 and 5.1 percentage points from 57.8% in FY26. Management said the shift was deliberate and was the main reason margins held as input costs moved higher during the quarter.
Revenue from operations rose 21.7% year on year to Rs 154.2 crore in Q2 FY27 from Rs 126.6 crore in Q2 FY26. Chief Financial Officer Aakarsh Goyal said this growth came from volume and a richer product mix, rather than from price increases. The company operates in metal rolls, engineering castings and specialty alloy steel products.
Management said metal rolls and engineering castings together accounted for about 55% to 60% of the order book at September-end, with alloy steel making up the balance. It added that the order-book split was broadly consistent with monthly sales. This provides the base for its effort to increase the contribution from engineered and import-substitution products.
Why did Behari Lal Engineering’s EBITDA margin hold despite cost inflation?
Behari Lal Engineering reported a Q2 FY27 EBITDA margin, including other income, of 17.9%, up 74 basis points from 17.2% in Q2 FY26, because the higher-value product mix partly offset firmer scrap, alloy, fuel and power costs. EBITDA rose 26.9% year on year to Rs 27.6 crore, faster than the 21.7% increase in revenue.
The Q2 margin was, however, below 19.6% in Q1 FY27. Management attributed the 1.7-percentage-point sequential decline to scrap and alloy prices firming during Q2 while selling prices reset with a lag, as well as to a more favourable product and customer mix in Q1. Management said neither factor reflected a change in the business.
For H1 FY27, EBITDA including other income increased 25.1% to Rs 57.4 crore and the margin reached 18.8%, compared with 18.0% in the prior-year half. Q2 profit after tax rose 27.7% year on year to Rs 17.4 crore, while H1 profit after tax increased 26% to Rs 36.6 crore. The comparison shows year-on-year margin expansion despite the quarter-on-quarter moderation.
Management said it absorbed part of the increase in raw-material and energy costs and passed on the remainder through its usual pricing process. In response to an investor question, management said realizations could improve in the next quarter, but it gave no numerical guidance for Q3 FY27, the second half or the full year.
Got a follow-up? Ask IRIS
What did inventory buying add to Behari Lal Engineering’s Q2 performance?
Behari Lal Engineering said it built Rs 23.6 crore of inventory in H1 FY27 to cover confirmed orders as raw-material prices firmed, and management said this action was also part of why Q2 margins held. The company had an order book of Rs 179.4 crore at the end of September 2026 and purchased additional scrap to support its execution.
Cash generated from operations was Rs 16.9 crore in H1 FY27, compared with Rs 1.8 crore in H1 FY26, against H1 profit after tax of Rs 36.6 crore. Management described the inventory as working capital held against confirmed orders, rather than slow-moving stock, and said inventory would begin to normalize from the next quarter.
The inventory purchase and the product-mix shift addressed different parts of the same cost environment. Inventory covered the Rs 179.4 crore order book when raw-material prices were firming, while high-value products represented 62.9% of Q2 revenue. The call did not disclose inventory volumes, procurement prices or margin effects by product line.
At September 30, 2026, net worth stood at Rs 427.3 crore and all term loans had been repaid, according to management. Cash and bank balances were Rs 114.6 crore, largely deposits intended for future capital expenditure and operating needs. Of Rs 93 crore of fresh issue proceeds, Rs 30.4 crore had been used and Rs 62.6 crore remained unutilised, mainly in bank deposits.
Which new products could increase Behari Lal Engineering’s high-value mix?
Behari Lal Engineering is constructing a third unit for Indefinite Chilled Double Poured, or ICDP, rolls and high-speed steel, or HSS, rolls, which management said are currently imported into India. Management expected commissioning in the first half of the next year, although it did not provide a specific date, project cost or capacity figure.
Management said it had received numerous customer inquiries for ICDP and HSS rolls but had not yet begun production or commercial deliveries. Its stated plan is to send trial lots after production starts and seek repeat orders within one or two months. These are management expectations, rather than reported sales or confirmed order-book additions.
The company said normal-category metal rolls already represent about 10% to 12% of India’s demand. It has also raised maximum single cast-piece size to 25 metric tons from 20 metric tons and established an accredited laboratory under the National Accreditation Board for Testing and Calibration Laboratories, or NABL. Management said the laboratory shortens qualification cycles for demanding customers.
Exports accounted for 5% to 10% of the September-end order book, according to management. About 90% of exports are engineering castings and about 10% are metal rolls, while alloy-steel exports are very small. Behari Lal Engineering has shipped to 24 countries to date, but the call did not disclose Q2 FY27 export revenue.
Conclusion
Behari Lal Engineering’s higher-value mix was the principal operational support for Q2 FY27 profitability as input costs rose. The 62.9% share of high-value products, compared with 57.8% in FY26, coincided with 21.7% revenue growth to Rs 154.2 crore and a 74-basis-point year-on-year increase in EBITDA margin to 17.9%.
The next disclosures to watch are whether selling-price resets improve realizations after the lag described by management and whether the Rs 23.6 crore H1 inventory build normalizes. Management also expects the third unit for ICDP and HSS rolls to start in the first half of the next year, after which customer trials and potential repeat orders would be the relevant milestones.