










BRG H1 revenue rose 60.7% while EBITDA margin fell 165 bps
Key highlights
- BRG’s H1 FY27 operational revenue rose 60.67% year on year to Rs 549.71 crore.
- BRG’s H1 FY27 EBITDA margin declined 165 basis points to 6.38% from 8.03%.
- BRG’s order book was Rs 1,755.06 crore at September 30, 2026, up 42% from March 2026.
- BRG’s ready-mix concrete plant utilisation reached 70% in H1 FY27, compared with 66% in FY26.
powered by IRIS
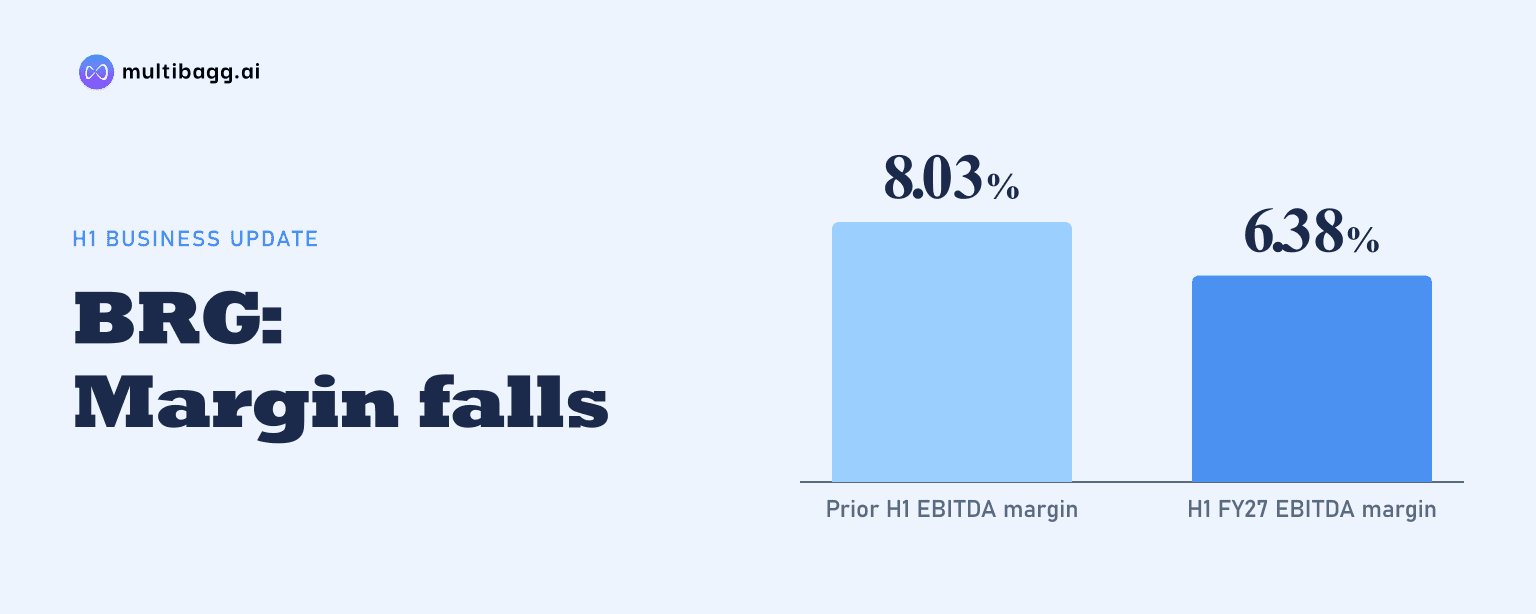
B R Goyal Infrastructure Ltd, referred to as BRG, reported H1 FY27 operational revenue of Rs 549.71 crore, up 60.67% year on year, while EBITDA margin fell 165 basis points to 6.38%. EBITDA increased 27.63% to Rs 35.06 crore, slower than revenue, according to its September 2026 presentation.
Know B.R.Goyal Infrastructure inside out
Results, valuation, peers and who's buying, in one view.
Why did BRG’s H1 FY27 revenue rise 60.7%?
BRG’s operational revenue rose to Rs 549.71 crore in H1 FY27 from Rs 342.13 crore in H1 FY26. Total income increased 60.43% to Rs 551.38 crore from Rs 343.68 crore, while other income changed only to Rs 1.67 crore from Rs 1.54 crore. The income statement therefore shows that operating revenue accounted for nearly all of the reported increase.
BRG’s remaining order book was Rs 1,755.06 crore at September 30, 2026, up 42% from Rs 1,235 crore at March 2026. The 36 contracts comprised Rs 962 crore of toll collection contracts, Rs 589.03 crore of engineering, procurement and construction, or EPC, road work, Rs 132.03 crore of wastewater infrastructure and Rs 72 crore of EPC building work.
H1 FY27 operational revenue also exceeded the Rs 478.19 crore reported in H2 FY26, although these are sequential half-year periods rather than a year-on-year comparison. BRG’s financial-highlights page separately reports H1 FY27 revenue of Rs 531.38 crore, while the half-year income statement reports operational revenue of Rs 549.71 crore; the presentation does not explain the difference.
Why did BRG’s EBITDA margin decline despite higher revenue?
BRG’s EBITDA margin declined to 6.38% in H1 FY27 from 8.03% in H1 FY26, a reduction of 165 basis points, where 100 basis points equal one percentage point. EBITDA, or earnings before interest, tax, depreciation and amortisation, increased to Rs 35.06 crore from Rs 27.47 crore, but its 27.63% growth was below the 60.67% rise in operational revenue.
The H1 FY27 cost profile included Rs 392.10 crore of other expenses, compared with Rs 305.37 crore in H1 FY26. Cost of materials consumed rose to Rs 79.94 crore from Rs 43.79 crore, and employee costs increased to Rs 17.98 crore from Rs 14.27 crore. Changes in inventories of finished goods, work-in-progress and stock in trade were Rs 24.84 crore in H1 FY27, compared with negative Rs 48.76 crore in H1 FY26.
BRG also reported a lower margin than in H2 FY26, when EBITDA was Rs 47.47 crore and the EBITDA margin was 9.93% on Rs 478.19 crore of operational revenue. H1 FY27 revenue was Rs 71.52 crore higher than H2 FY26, but EBITDA was Rs 12.41 crore lower. The presentation provides the reported cost lines but does not attribute the margin change to a project, segment or specific expense category.
How does BRG’s H1 profitability compare with FY26?
BRG’s H1 FY27 margin decline followed margin expansion in FY26. In FY26, operational revenue rose 60.91% to Rs 820.32 crore from Rs 509.80 crore in FY25, while EBITDA increased 81.91% to Rs 74.93 crore from Rs 41.19 crore. The FY26 EBITDA margin consequently increased 105 basis points to 9.13% from 8.08%.
Profit after tax, or PAT, rose 37.82% to Rs 22.12 crore in H1 FY27 from Rs 16.05 crore in H1 FY26. PAT margin nevertheless declined 67 basis points to 4.02% from 4.69%, while profit before tax rose 24.29% to Rs 27.58 crore. Finance costs increased to Rs 4.33 crore from Rs 3.04 crore and depreciation increased to Rs 4.28 crore from Rs 3.77 crore.
The FY26 comparison showed a different full-year outcome, with PAT increasing 77.76% to Rs 44.92 crore from Rs 25.27 crore in FY25. PAT margin rose to 5.48% from 4.96%, and basic earnings per share increased to Rs 23.87 from Rs 13.41. In H1 FY27, basic earnings per share were Rs 9.04, compared with Rs 8.55 in H1 FY26.
Got a follow-up? Ask IRIS
What operating capacity and contracts could affect BRG’s next period?
BRG’s Rs 1,755.06 crore order book is led by Rs 962 crore of toll collection contracts, with the balance spread across road, building and wastewater EPC work. BRG operates 10 toll collection contracts from the National Highways Authority of India and Uttar Pradesh Expressways Industrial Development Authority, with more than 800 personnel in that vertical across eight states.
The EPC portion of remaining work was Rs 793.06 crore at September 30, 2026, combining Rs 589.03 crore of road work, Rs 72 crore of building work and Rs 132.03 crore of wastewater infrastructure. BRG also reported more than 230 equipment items and vehicles, together with more than 1,400 employees, supporting execution across its projects.
BRG’s ready-mix concrete plant in Indore has annual capacity of 1.80 lakh cubic metres. Utilisation rose to 70% in H1 FY27 from 66% in FY26 and 64% in FY25. The company states that the higher utilisation leaves capacity headroom for further production and incremental revenue.
What do BRG’s balance sheet and plans show?
BRG reported shareholders’ funds of Rs 298.82 crore at September 30, 2026, up from Rs 274.02 crore at March 31, 2026. Current borrowings increased to Rs 49.42 crore from Rs 45.43 crore, while cash and cash equivalents rose to Rs 33.07 crore from Rs 30.05 crore. Operating cash flow was Rs 22.26 crore in H1 FY27, compared with Rs 1.94 crore for FY26.
Return on equity was 15.00% in H1 FY27, compared with 18.00% in FY26 and 16.71% in FY25. Return on capital employed was 16.29%, compared with 20.00% in FY26 and 23.07% in FY25. BRG’s debt-to-equity ratio was 0.27 in H1 FY27, against 0.28 in FY26 and 0.31 in FY25.
Management says BRG plans to invest in public-private partnership projects and identifies toll, hybrid annuity model and toll-operate-transfer projects as bidding opportunities. It also identifies scaling ready-mix concrete and residential plotting, and strategic partnerships in wastewater treatment and water-supply lines. These are management’s disclosed plans and opportunities, not revenue or margin targets.
Conclusion
BRG’s first-half figures show that the increase in operational activity did not translate into profit growth at the same rate. The contrast with FY26 is clear: that year EBITDA grew faster than operational revenue and the annual EBITDA margin reached 9.13%, whereas H1 FY27 EBITDA was lower than H2 FY26 despite higher revenue.
The next reporting period will show execution from the Rs 1,755.06 crore order book, including Rs 962 crore of toll contracts and Rs 132.03 crore of wastewater work. Investors can also monitor progress on management’s public-private partnership plan, ready-mix concrete utilisation above the H1 FY27 level of 70%, and whether BRG clarifies the difference between its two H1 FY27 revenue figures.