










Caliber Mining net debt-to-equity falls to 0.95x by September
Key highlights
- Caliber Mining reported net debt-to-equity of 0.95x at 30 September 2026, down from 1.48x at 31 March 2026.
- Net worth rose 77% to Rs 1,148.42 crore at 30 September 2026.
- Property, plant and equipment increased 38% to Rs 1,777.08 crore over the six-month comparison.
- CRISIL upgraded Caliber Mining's long-term rating to A- with a Positive outlook in August 2026.
powered by IRIS
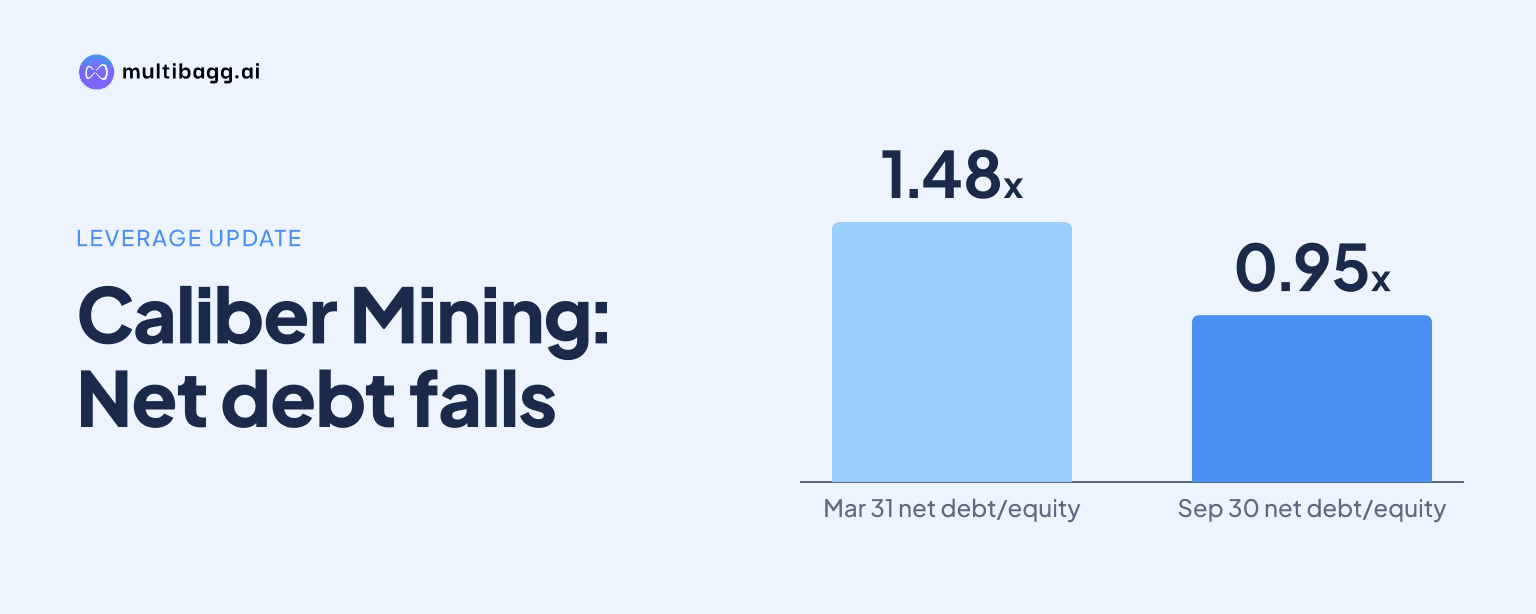
Caliber Mining and Logistics Limited reported net debt-to-equity of 0.95x at 30 September 2026, down from 1.48x at 31 March 2026, despite property, plant and equipment rising 38% to Rs 1,777.08 crore. The lower ratio coincided with net worth increasing 77% to Rs 1,148.42 crore and cash and bank balances increasing 59%.
Know Caliber Mining and Logistics inside out
Results, valuation, peers and who's buying, in one view.
Why did Caliber Mining's net debt-to-equity fall?
Caliber Mining's net debt-to-equity fell to 0.95x at 30 September 2026 from 1.48x at 31 March 2026, alongside higher net worth and cash balances. Caliber Mining defines net debt as borrowings less cash and bank balances, and excludes lease liabilities from borrowings. Net worth increased by Rs 500.88 crore over the six-month comparison, reaching Rs 1,148.42 crore from Rs 647.54 crore. The presentation identifies the post-initial public offering, or IPO, equity increase as part of the stronger equity base.
Cash and bank balances rose to Rs 156.38 crore at 30 September 2026 from Rs 98.15 crore at 31 March 2026, an increase of Rs 58.23 crore. The cash increase affects Caliber Mining's stated net-debt calculation because cash is deducted from borrowings. The presentation separately discloses borrowings of Rs 1,314 crore at 30 June 2026, but does not provide a gross-borrowings figure for 30 September 2026. The reported 0.95x ratio is therefore the disclosed leverage measure for the September date.
How much did Caliber Mining expand its equipment base?
Caliber Mining increased property, plant and equipment, or PPE, by Rs 485.75 crore, or 38%, to Rs 1,777.08 crore at 30 September 2026 from Rs 1,291.33 crore at 31 March 2026. The presentation describes this movement as a step-up in capital expenditure. The simultaneous reduction in net debt-to-equity shows that the reported leverage ratio declined while Caliber Mining added Rs 485.75 crore of recorded fixed assets during the six-month period.
The balance-sheet shift also extended beyond PPE. Total outside liabilities relative to net worth declined to 1.48x at 30 September 2026 from 2.21x at 31 March 2026, a reduction of 0.73x. The current ratio rose to 1.19x from 1.02x, an increase of 0.17x. These measures, together with the 77% increase in net worth, were reported for the same 31 March 2026 to 30 September 2026 comparison.
Got a follow-up? Ask IRIS
What changed in Caliber Mining's credit rating?
Caliber Mining's long-term CRISIL rating was upgraded in August 2026 to CRISIL A- with a Positive outlook from BBB+ with a Stable outlook. Its short-term rating was raised to CRISIL A2+ from A2. The presentation places the rating actions beside the lower 0.95x net debt-to-equity ratio and the 77% increase in net worth, but does not reproduce CRISIL's detailed rating rationale.
The rating upgrade occurred after the 31 March 2026 balance-sheet date and before the 30 September 2026 reporting date. At the later date, Caliber Mining reported Rs 156.38 crore of cash and bank balances and Rs 1,777.08 crore of PPE. Caliber Mining characterises the profile as having lower leverage despite higher capital expenditure, while the presentation records the revised rating categories without disclosing a further rating target or review date.
How does Caliber Mining's balance sheet compare with operations?
Caliber Mining generated Rs 100.83 crore of cash profit in H1 FY27, compared with Rs 63.29 crore in H1 FY26, a 1.6-times increase. Caliber Mining calculates this non-GAAP measure as profit after tax, or PAT, plus depreciation and amortisation, plus impairment loss on financial assets, less lease rentals paid. H1 FY27 PAT was Rs 22.25 crore, depreciation and amortisation was Rs 97.97 crore, impairment loss was Rs 4.16 crore, and lease rentals paid were Rs 23.55 crore.
Normalised revenue, which excludes diesel cost pass-through, rose 59.5% to Rs 992.40 crore in H1 FY27 from Rs 622.07 crore in H1 FY26. Normalised earnings before interest, tax, depreciation and amortisation, or EBITDA, increased 48.7% to Rs 183.57 crore, while the normalised EBITDA margin declined to 18.50% from 19.85%. For the trailing 12 months, or TTM, to September 2026, normalised revenue was Rs 2,047.99 crore and normalised EBITDA was Rs 490.79 crore.
Conclusion
Caliber Mining reported net debt-to-equity of 0.95x at 30 September 2026 while PPE rose 38% to Rs 1,777.08 crore. The lower ratio was accompanied by net worth rising 77%, cash and bank balances rising 59%, total outside liabilities relative to net worth declining by 0.73x, and the current ratio increasing to 1.19x. The August 2026 CRISIL upgrade marked a separate credit-profile change during the same financial year.
The next disclosed operating marker is H2 FY27, which Caliber Mining says is seasonally stronger. In FY26, H2 revenue of Rs 1,055.59 crore was 1.7 times H1 revenue and H2 EBITDA of Rs 307.21 crore was 2.5 times H1 EBITDA. Execution of the Rs 8,633.94 crore closing order book at 30 September 2026, spanning nine sites with an average tenure of 2.5 years, is another disclosed item to watch.