










Carborundum Universal Posts Record Rs 911 Crore Q2 Sales
Key highlights
- CARBORUNIV reported record Q2 FY27 standalone sales of Rs 911 crore, up 28% year on year.
- Consolidated sales rose 13.1% year on year to Rs 1,455 crore in Q2 FY27.
- Consolidated Ceramics sales grew 36.1% year on year and PBIT increased 62.1%.
- The reported Q2 FY27 net profit was Rs 12.45 crore, down 83.29% year on year.
powered by IRIS
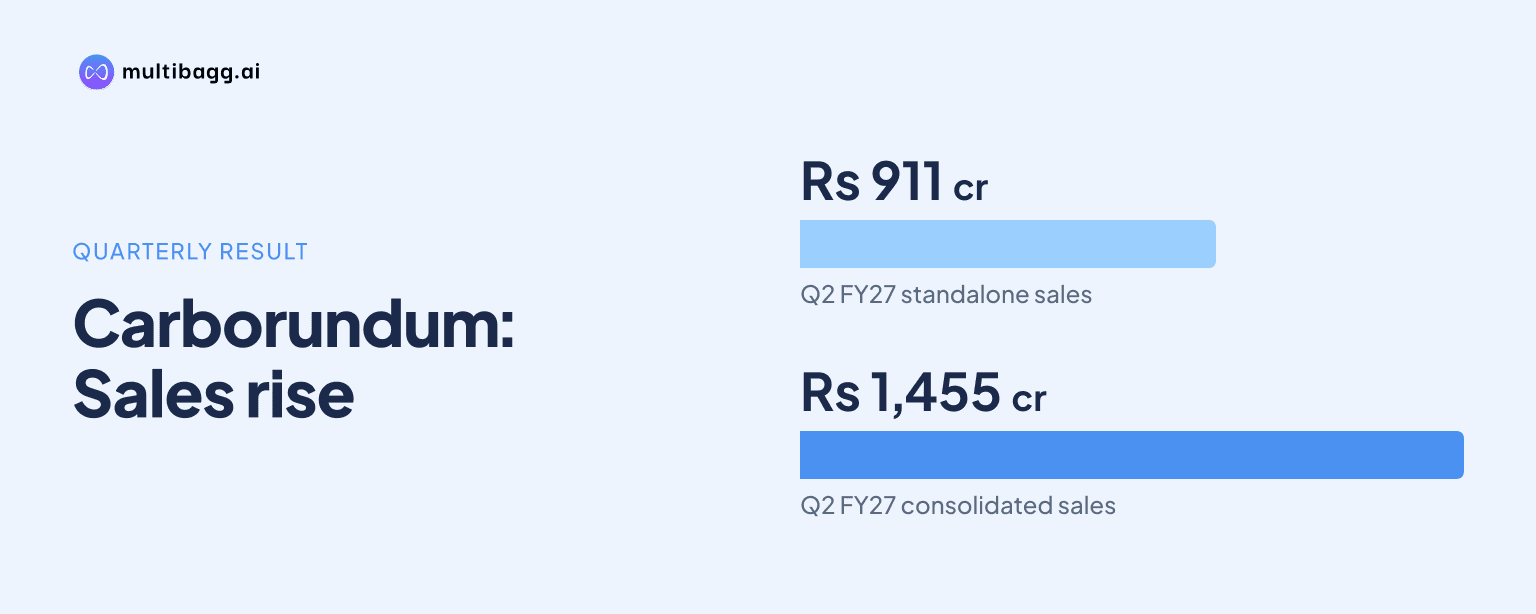
Carborundum Universal Limited reported record standalone sales of Rs 911 crore in Q2 FY27, up 28% year on year from Rs 712 crore, while its reported quarterly net profit was Rs 12.45 crore, down 83.29% from the corresponding prior-year quarter.
Know Carborundum Universal inside out
Results, valuation, peers and who's buying, in one view.
What did CARBORUNIV report for Q2 FY27?
CARBORUNIV reported its highest-ever quarterly standalone sales in the July-September 2026 quarter. Standalone sales rose to Rs 911 crore from Rs 712 crore a year earlier and from Rs 846 crore in the preceding quarter. This represented year-on-year growth of 28% and sequential growth of 7.7%.
Consolidated sales in the earnings-call presentation were Rs 1,455 crore, compared with Rs 1,287 crore in Q2 FY26, an increase of 13.1%. Consolidated sales were also 3.1% higher than Rs 1,411 crore in Q1 FY27. Separately, the results summary cited revenue of Rs 1,469.05 crore, against Rs 1,298.08 crore a year earlier, implying 13.17% growth.
Profit measures showed a sharper divergence because the available disclosures refer to different reporting bases. The company stated that standalone profit after tax was Rs 72 crore, up 12.4% from Rs 64 crore in Q2 FY26. The results summary reported net profit of Rs 12.45 crore, down 83.29% year on year from Rs 74.51 crore. The supplied earnings material also noted that consolidated PAT was affected by exceptional items and closure costs.
Which businesses drove CARBORUNIV's growth?
CARBORUNIV said all three segments delivered double-digit growth in the quarter, with Ceramics providing the strongest reported operating momentum. Consolidated Ceramics sales rose 36.1% year on year, while Ceramics PBIT increased 62.1%, supported by industrial ceramics and refractory operations across India, the Americas and Australia.
On a standalone basis, Ceramics sales were Rs 313 crore in Q2 FY27, compared with Rs 228 crore in Q2 FY26. Standalone Ceramics PBT rose 48.2% to Rs 67 crore from Rs 45 crore. Electrominerals PBT increased 49.1% to Rs 29 crore from Rs 20 crore.
Abrasives showed a different pattern. Consolidated Abrasives sales declined marginally to Rs 607 crore from Rs 610 crore. Standalone Abrasives PBT fell 19.9% to Rs 37 crore from Rs 47 crore, even as the wider company recorded record standalone sales.
What did management say about margins and FY27 guidance?
Managing Director Sridharan Rangarajan said margins had bottomed out during the earnings call. He also said all three key geographies - the US, Australia and India - were performing well, supporting the difference between consolidated and standalone business performance.
Management identified Engineered Ceramics, including Bloom-related products and metallized cylinders, as the fastest-growing vectors within the Ceramics portfolio. This is relevant because the segment had the strongest sales and profit growth among the businesses detailed in the call.
CARBORUNIV raised its FY27 consolidated Ceramics growth guidance to 25%-28%. It had initially indicated 15%-15.5%, then revised the range to 23%-25% during the previous earnings call. For consolidated sales, management said reported growth could be about 4%-4.5% in FY27, but comparable growth excluding Foskor and AWUKO revenue contributions of Rs 343 crore in FY26 could be 11%-12%.
Got a follow-up? Ask IRIS
How does the Q2 performance affect investors and operations?
The record Rs 911 crore standalone sales figure indicates strong quarterly demand across CARBORUNIV's domestic operations. Consolidated growth was lower than standalone growth, but remained positive at 13.1% year on year. The company linked its overseas performance to activity in the US and Australia alongside India.
For investors, the quarter presents two separate considerations. Operating data showed higher sales, stronger consolidated profit before exceptional items and tax, and substantial Ceramics growth. Consolidated profit before exceptional items and tax rose 22.9% to Rs 138 crore from Rs 113 crore, and was 16% above Rs 119 crore in Q1 FY27.
However, the reported net-profit number was materially lower year on year. The available material attributes pressure on consolidated PAT to exceptional items and closure costs. Investors assessing the result therefore need to distinguish between the operating-profit indicators discussed in the earnings call and the reported quarterly profit figure in the results summary.
What is the broader context for CARBORUNIV's first-half performance?
For the first half of FY27, standalone sales grew 24.6% and consolidated sales grew 14.9%, according to the earnings-call material. Consolidated segment results rose 36.1% in the first half, indicating that the improvement was not confined to a single quarter.
The segment mix also shows why Ceramics is central to the current result. In H1 FY27, consolidated segment sales were Rs 1,217 crore for Abrasives, Rs 759 crore for Ceramics and Rs 916 crore for Electrominerals. Their respective growth rates were 11.5%, 26.3% and 15%, placing Ceramics ahead of the other two segments.
CARBORUNIV held its investor call on November 3, 2026, after reporting results for the quarter ended September 30, 2026. The company subsequently made the audio recording of the call available on its website, allowing shareholders to review management's commentary on sales, margins and segment guidance.
Conclusion
CARBORUNIV's Q2 FY27 result combined record standalone sales with uneven profitability measures. Standalone sales reached Rs 911 crore and Ceramics delivered the fastest segment expansion, while the reported net profit of Rs 12.45 crore reflected the effect of exceptional items and closure costs cited in the earnings material.
The next disclosures to monitor are management's progress toward 25%-28% consolidated Ceramics growth guidance and the stated 11%-12% comparable consolidated-sales growth range excluding prior-year Foskor and AWUKO revenue. Margin trends and the treatment of exceptional and closure costs will also remain relevant to assessing subsequent reported profit figures.