










CUMI raises FY27 ceramics growth outlook to 25%-28% range
Key highlights
- CUMI increased FY27 consolidated ceramics sales-growth guidance to 25%-28% from 23%-25%.
- CUMI raised FY27 consolidated ceramics margin guidance to 22.5%-23.5% from 20.5%-21%.
- CUMI's consolidated ceramics sales rose 36.1% year on year to Rs 410 crore in Q2 FY27.
- CUMI's consolidated ceramics PBIT increased 62.1% year on year to Rs 101 crore in Q2 FY27.
powered by IRIS
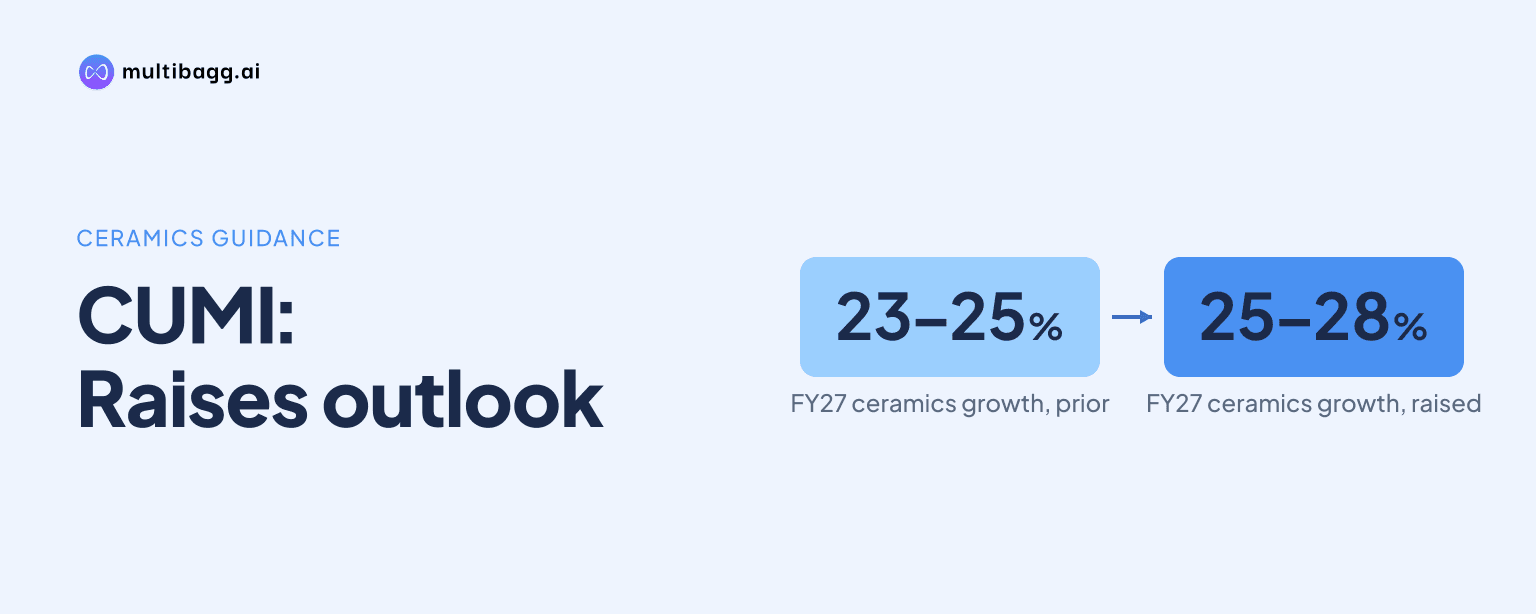
Carborundum Universal Limited, or CUMI, raised its FY27 consolidated ceramics sales-growth guidance to 25%-28% and its margin outlook to 22.5%-23.5%, after ceramics sales rose 26.3% to Rs 759 crore in the first half, or H1, of FY27. Management attributed the upgraded outlook principally to demand for engineered ceramics and metallised cylinders.
Know Carborundum Universal inside out
Results, valuation, peers and who's buying, in one view.
Why did CUMI raise its ceramics guidance?
CUMI raised its FY27 consolidated ceramics sales-growth outlook to 25%-28%, from the 23%-25% range communicated in its previous earnings call. The new range is also above its initial FY27 growth guidance of 15%-15.5%, following consolidated ceramics sales of Rs 759 crore in H1 FY27, compared with Rs 601 crore in H1 FY26.
CUMI also increased its FY27 consolidated ceramics margin outlook to 22.5%-23.5%, from 20.5%-21% previously. Management said the revised sales and margin outlook reflects projected demand in industrial engineered ceramics and metallised cylinders, while the bare-ceramics business is also expanding at a slower rate than those two product areas.
The revised guidance came while CUMI retained its 15% consolidated sales-growth guidance for FY27. Management said reported consolidated growth is affected by the closure or wind-down of Foskor Zirconia and AWUKO, which together contributed Rs 343 crore of revenue in FY26.
How fast is CUMI's ceramics business growing?
CUMI's consolidated ceramics sales increased 36.1% year on year to Rs 410 crore in the second quarter, or Q2, of FY27, from Rs 301 crore in Q2 FY26. Sales also rose 17.6% sequentially from Rs 349 crore in Q1 FY27, indicating that the H1 increase was supported by growth in both FY27 quarters.
CUMI reported ceramics growth across India, the Americas and Australia in H1 FY27. Management said industrial ceramics and refractory products contributed, alongside metallised cylinders, engineered ceramics, ceramics used in solid oxide fuel cells, or SOFCs, and wear ceramics.
The quarterly sales result was higher than both the prior-year quarter and the immediately preceding quarter. That differs from consolidated electrominerals sales, which declined 6.3% sequentially to Rs 443 crore in Q2 FY27, primarily because of lower sales at Foskor Zirconia.
Which ceramics products are driving CUMI's upgraded outlook?
CUMI identified industrial engineered ceramics as its fastest-growing ceramics area, with Bloom-related products included within that business. Management named metallised cylinders as the second key growth vector, while saying that bare ceramics continues to grow but not at the same rate as engineered ceramics and metallised cylinders.
CUMI said its ceramics business typically exports more than 85% of sales, and that proportion was maintained in H1 FY27. The company also recorded ceramics growth in all three disclosed regions, with India, the Americas and Australia contributing to the Rs 759 crore H1 sales total.
Management's comments tied the increased FY27 sales range and margin range to demand from the two higher-growth product vectors. The company did not disclose separate revenue, customer concentration or margin figures for engineered ceramics, Bloom-related products or metallised cylinders during the call.
Got a follow-up? Ask IRIS
What do ceramics profits indicate about CUMI's earnings mix?
CUMI's consolidated ceramics profit before interest and tax, or PBIT, increased 62.1% year on year to Rs 101 crore in Q2 FY27 from Rs 62 crore in Q2 FY26. The increase in PBIT exceeded the segment's 36.1% sales growth in the quarter, alongside management's increase in FY27 ceramics margin guidance to 22.5%-23.5%.
For H1 FY27, consolidated ceramics PBIT rose 28.1% to Rs 176 crore from Rs 137 crore in H1 FY26. Q2 FY27 PBIT was also 36.5% above the Rs 74 crore reported in Q1 FY27, compared with sequential sales growth of 17.6% over the same period.
The ceramics result contrasted with standalone abrasives, where Q2 FY27 PBIT declined 19.9% to Rs 37 crore from Rs 47 crore a year earlier. CUMI said higher fuel, phenol and resin costs raised manufacturing costs in abrasives, while only a small portion of the increase could be passed on to customers.
What could affect CUMI's FY27 ceramics outlook?
CUMI retained consolidated capital-expenditure guidance of Rs 400 crore for FY27 after spending Rs 127 crore in H1 FY27, compared with Rs 162 crore in H1 FY26. Management said its growth programmes and capital expenditure were on track, while the ceramics guidance depends on the demand trajectory in engineered ceramics and metallised cylinders.
CUMI reported consolidated debt of Rs 362 crore and cash of Rs 251 crore at the reported period end, excluding cash at VAW, resulting in net debt of Rs 111 crore. The consolidated debt-to-equity ratio was 0.09, and the company said it was progressing with the closure of Foskor Zirconia and AWUKO.
Management said Foskor Zirconia was commercially unviable because of sustained losses, rising input costs and market pressures, and it continued low-level operations in Q2 FY27 with sales of ZAR 53 million and a loss of ZAR 24 million. Management said it realistically expected to complete the Foskor Zirconia closure during the current quarter.
Conclusion
CUMI's higher FY27 ceramics guidance reflects sales growth of 36.1% in Q2 FY27 and 26.3% in H1 FY27, with engineered ceramics and metallised cylinders identified as the main contributors. The segment's Q2 PBIT rose 62.1% to Rs 101 crore, while standalone abrasives faced input-cost pressure that reduced its Q2 PBIT by 19.9%.
The next measures to watch are whether H2 FY27 demand supports the 25%-28% ceramics sales-growth target and 22.5%-23.5% margin target, and progress on the Rs 400 crore FY27 consolidated capital-expenditure plan. Management also expects the Foskor Zirconia closure to be completed in the current quarter, following its reported Q2 FY27 loss of ZAR 24 million.