










Ceigall India Limited Q2 margin reaches 17% as mix broadens
Key highlights
- Ceigall India’s consolidated Q2 FY2027 EBITDA margin rose to 17% from 14.1% a year earlier.
- Consolidated Q2 FY2027 revenue increased 26.8% to Rs 1,022.5 crore and EBITDA grew 53.2% to Rs 174 crore.
- Ceigall India generated almost Rs 143 crore of renewable-sector turnover in FY2027 to date, compared with none in the prior year.
- The order book stood at Rs 22,681 crore on September 30, 2026, including 21% transmission and distribution and 16% renewable energy.
powered by IRIS
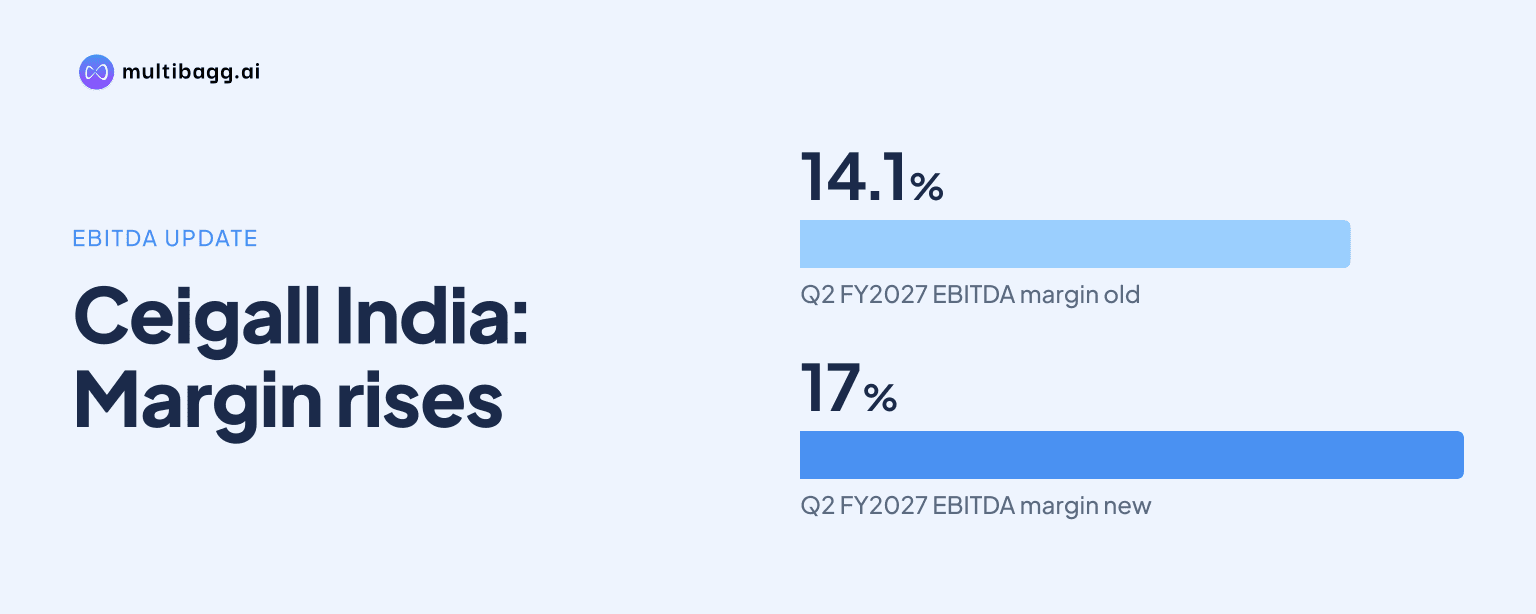
Ceigall India Limited reported a 17% consolidated earnings before interest, tax, depreciation and amortisation (EBITDA) margin in the second quarter (Q2) of financial year (FY) 2027, up from 14.1% a year earlier, as revenue rose 26.8% to Rs 1,022.5 crore and management cited renewable, transmission and profitable highway work.
Know Ceigall India inside out
Results, valuation, peers and who's buying, in one view.
Why did Ceigall India’s Q2 EBITDA margin rise to 17%?
Ceigall India’s consolidated EBITDA margin increased by 2.9 percentage points year on year to 17% in Q2 FY2027 because management said renewable energy and transmission work earned healthy margins, while recently started hybrid annuity model (HAM) projects VRK 11 and 12 were profitable. Consolidated EBITDA rose 53.2% to Rs 174 crore from Rs 113.6 crore, growing faster than revenue.
Renewable work was the key incremental contributor to turnover in FY2027 to date, according to management. Ceigall India recorded almost Rs 143 crore of renewable-sector turnover during the period, compared with no renewable turnover in the prior year. Management also said renewable and transmission projects should add to turnover going forward, but did not provide segment-level revenue or margin guidance.
The improvement also extended below EBITDA. Consolidated profit after tax (PAT) grew 64.1% to Rs 92.2 crore in Q2 FY2027 from Rs 56.2 crore in Q2 FY2026, while the PAT margin rose to 9% from 7%. Standalone EBITDA margin increased to 13.4% from 11.7%, showing that the consolidated margin expansion was larger than the standalone improvement.
How did Ceigall India perform in H1 FY2027?
Ceigall India’s consolidated revenue from operations rose 21.1% to Rs 1,992.1 crore in the first half (H1) of FY2027 from Rs 1,644.7 crore in H1 FY2026, while EBITDA increased 42.5% to Rs 317.4 crore. The H1 EBITDA margin consequently expanded to 15.9% from 13.5%, a 2.4-percentage-point increase that was smaller than the Q2 increase but still showed higher profitability over six months.
Consolidated PAT for H1 FY2027 was approximately Rs 156 crore, around 45% above the previous year, and its margin rose to 7.8% from 6.5%. The Q2 PAT margin of 9% was higher than the H1 margin of 7.8%, based on the company’s reported figures, indicating that profitability was higher in the second quarter than across the aggregate half-year period.
Standalone operations also expanded, although at a lower reported revenue base than consolidated operations. Standalone Q2 revenue was Rs 974.5 crore, up 23.8% from Rs 787 crore, and standalone EBITDA grew 42.3% to Rs 130.5 crore. In H1 FY2027, standalone revenue increased 16.9% to Rs 1,876 crore and EBITDA rose 35.8% to Rs 251.6 crore, with margin reaching 13.4% from 11.5%.
Got a follow-up? Ask IRIS
What work is changing Ceigall India’s project mix?
Ceigall India’s Rs 22,681 crore order book at September 30, 2026 remained led by roads and highways, but the mix had broadened into power and energy. Roads and highways accounted for about 55% of the book, followed by transmission and distribution at 21%, renewable energy at 16%, metro projects at 4% and industrial infrastructure at 3%.
The order book contained 18 engineering, procurement and construction (EPC) projects, 10 HAM projects, one design-build-finance-operate-transfer project and 10 tariff-based projects. The company received a letter of intent for the Lakadia-Jam Khambhaliya-Jamnagar transmission project in Gujarat, valued at approximately Rs 5,700 crore including goods and services tax (GST).
The Gujarat project includes 765 kilovolt and 400 kilovolt substations and around 300 kilometres of transmission lines, with a 36-month construction period followed by a 35-year operational period. Management said the EPC value was Rs 5,300 crore including GST and was targeting a start before March 31, while describing that timetable as aggressive.
In renewable energy, Ceigall India’s wholly owned subsidiary commissioned 10 megawatts from its 147-megawatt Maharashtra solar plant during Q2 FY2027, ahead of schedule. For the Morena project in Madhya Pradesh, management said land was available and one transmission line was complete, but the remaining transmission contractor was being finalised; it said commencement during the current year appeared difficult.
What does Ceigall India’s execution pipeline indicate for FY2027?
Ceigall India’s execution pipeline includes three HAM projects worth Rs 4,050 crore that received appointed dates: Varanasi-Ranchi-Kolkata greenfield highway packages 11 and 12, known as VRK 11 and 12, and the Indore-Ujjain Greenfield Highway. Management said financial closure had been completed for all its highway projects, and that monthly running-bill payments were being received for VRK 11 and 12.
Management also expected the first payment for Indore-Ujjain before Diwali, which would mark further movement from order-book status into construction execution. These projects were among the profitable HAM works management cited when explaining the Q2 FY2027 EBITDA margin improvement to 17%.
Through a joint venture, Ceigall India won five packages of the NH 913 Frontier Highway in Arunachal Pradesh, aggregating approximately Rs 3,128 crore and 278 kilometres. Management cited more than 10 years of Himalayan-terrain experience, including a 6.5-kilometre tunnel at Ramban-Banihal and a nearby viaduct it said was 60% complete, as relevant to executing the Northeast packages.
Management retained its minimum 15% growth guidance despite consolidated H1 FY2027 revenue already increasing 21.1%. It said renewable and transmission businesses were providing the growth push, while it had secured close to Rs 5,400 crore against FY2027 order-inflow guidance of Rs 6,000 crore and had quoted for tenders exceeding Rs 10,000 crore. These are management targets and tendering disclosures, rather than confirmed future revenue.
Conclusion
Ceigall India’s Q2 FY2027 results showed EBITDA and PAT increasing faster than revenue, with consolidated EBITDA up 53.2% and margin reaching 17%. Management attributed the mix-led change to renewable energy, transmission and newly executing profitable HAM projects, while the Rs 22,681 crore order book showed roads remained the largest segment at 55% but not the only substantial source of work.
The next markers are execution of the Rs 4,050 crore HAM projects, further commissioning at the 147-megawatt Maharashtra solar plant and progress toward starting the Gujarat transmission project before March 31. Management also plans to complete Bathinda-Dabwali monetisation in the current quarter and Jalbehra-Shahbad monetisation in the following quarter, expecting around Rs 250 crore of inflow and approximately Rs 540 crore of debt reduction.