










Chandan Healthcare Limited Q2 PAT Rises 224% to ₹18.61 Crore
Key highlights
- Chandan Healthcare Limited's Q2 FY27 standalone total income rose 44.78% year on year to ₹59.36 crore.
- Q2 FY27 standalone EBITDA increased 54.79% to ₹22.12 crore, with margin expanding to 37.26%.
- Q2 FY27 standalone PAT rose 224.19% to ₹18.61 crore and included a ₹10.23 crore exceptional gain.
- H1 FY27 standalone PAT increased 256.72% year on year to ₹25.37 crore.
powered by IRIS
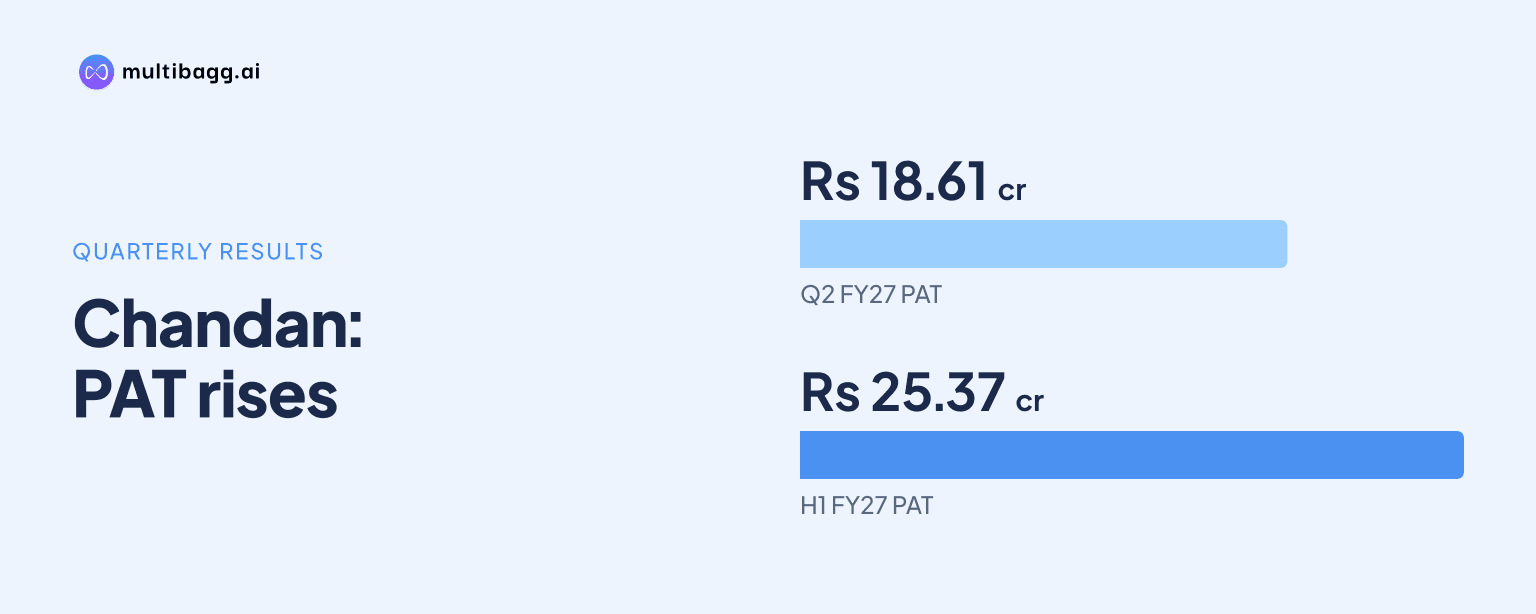
Chandan Healthcare Limited reported Q2 FY27 standalone profit after tax of ₹18.61 crore, up 224.19% year on year, as total income rose 44.78% to ₹59.36 crore and the quarter included a ₹10.23 crore one-time gain from the Chandan Pharmacy Limited stake sale.
Know Chandan Healthcare inside out
Results, valuation, peers and who's buying, in one view.
How did Chandan Healthcare Limited perform in Q2 FY27?
Chandan Healthcare Limited recorded broad growth in its standalone financial metrics for the July-September 2026 quarter. Total income rose 44.78% year on year and 19.30% sequentially to ₹59.36 crore. EBITDA increased 54.79% year on year to ₹22.12 crore, while the EBITDA margin expanded by 241 basis points to 37.26%.
Profitability rose faster than income during the quarter. Standalone PAT climbed 224.19% year on year and 175.45% quarter on quarter to ₹18.61 crore. PAT margin stood at 31.35%, up 1,735 basis points from a year earlier. Earnings per share increased 226.90% year on year to ₹6.44.
The company also separately reported Q2 revenue from operations of ₹57.94 crore, up about 45% year on year. Total income was ₹59.36 crore. The reported PAT includes an exceptional, one-time gain of ₹10.23 crore arising from the sale of its stake in Chandan Pharmacy Limited.
Why did Chandan Healthcare Limited's reported profit rise sharply?
Chandan Healthcare Limited's reported Q2 profit was supported by both operational growth and the pharmacy divestment-related exceptional gain. The ₹10.23 crore one-time gain formed part of the reported quarterly PAT of ₹18.61 crore, making it an important consideration when comparing the quarter's profit growth with recurring operations.
The operational data nonetheless showed income and EBITDA growing year on year, with EBITDA growth of 54.79% exceeding total-income growth of 44.78%. The EBITDA margin of 37.26% was also higher than the prior-year period by 241 basis points. These figures indicate that operating profitability improved during the reported quarter.
Chandan Healthcare Limited has stated that it is now a pure-play diagnostics business after the pharmacy divestment. Its earnings-call commentary linked the business focus to a shift away from lower-margin government National Health Mission, or NHM, contracts toward a business-to-consumer franchise model.
What does the H1 FY27 performance show?
Chandan Healthcare Limited reported H1 FY27 standalone total income of ₹109.12 crore, up 40.56% year on year, while EBITDA grew 66.52% to ₹40.31 crore. The half-year EBITDA margin increased 576 basis points to 36.95%, extending the margin improvement reported in the September quarter.
H1 FY27 PAT rose 256.72% year on year to ₹25.37 crore, and PAT margin increased 1,409 basis points to 23.25%. EPS for the six-month period was ₹8.78, up 122.84% year on year. As with the quarterly figures, the company has indicated that H1 profit included the one-time gain from the Chandan Pharmacy stake sale.
The difference between the 36.95% H1 EBITDA margin and the 37.26% Q2 margin shows that the September-quarter operating margin was modestly above the half-year average. But the reported PAT figures should be read with the disclosed exceptional item in mind, as it is not described as recurring diagnostics income.
Got a follow-up? Ask IRIS
What expansion plans has Chandan Healthcare Limited outlined?
Chandan Healthcare Limited has guided for standalone growth of 40% to 50% in FY27 and FY28, according to the earnings-call summary. Management linked this outlook to the expected contribution from franchise expansion, while caution is appropriate because this is company guidance rather than a reported result.
The company has set a target of 1,500 franchise centres by the end of FY27 and more than 4,000 centres by the end of FY28. It reported a presence in 15 states and outlined plans to enter three additional states over the following three months. It also said it added 280 franchisees in October and aims to increase monthly franchisee additions to 500.
Management said it had acquired three centres during the current financial year and was targeting at least four or five acquisitions in the year. It also outlined PET scan centre plans for Gorakhpur, Kanpur, Haldwani, Jodhpur, Bhopal and Raipur. The Gorakhpur centre was expected to start within the next two months, based on the call commentary.
How could the strategy affect investors and operations?
Chandan Healthcare Limited's move away from NHM contracts is central to its stated operating strategy. Management expects to complete its exit from the government business within two or three months and said it would not apply again for NHM government contracts. This increases the importance of franchise execution, diagnostic-centre expansion and acquisition integration for the business.
For investors, the key distinction is between improved operating metrics and the reported PAT that includes the ₹10.23 crore exceptional gain. Total income, EBITDA and margin expansion provide measures of the diagnostics business's reported operating performance, while the profit figure includes a non-recurring divestment component.
For customers and local operations, the expansion plan points to a larger diagnostics network across existing and new states. However, the source does not provide centre-level revenue, customer volumes, pricing data or capital expenditure figures, so the financial contribution of individual expansion projects is not yet quantifiable.
Conclusion
Chandan Healthcare Limited delivered higher standalone income, EBITDA and margins in Q2 and H1 FY27, while reported PAT growth was amplified by the one-time ₹10.23 crore gain from selling its Chandan Pharmacy Limited stake. The results also mark a clearer strategic focus on diagnostics following the pharmacy divestment.
The next disclosures to watch are progress on the planned NHM exit, franchise additions toward the 1,500-centre FY27 target, the announced acquisitions and commissioning of the proposed PET scan centres. These updates will provide further evidence on how the company's franchise-led diagnostics strategy is progressing.