










Cohance Pharma CDMO revenue rises 34.5% sequentially in Q2 FY27
Key highlights
- Cohance Pharma CDMO revenue increased 34.5% quarter-on-quarter in Q2 FY27 but remained 27% below the prior-year quarter.
- Cohance secured three large-pharma programs in Q2 FY27: two commercial awards and one Phase III award.
- Cohance reported Q2 FY27 revenue of Rs 476.7 crore and adjusted EBITDA of Rs 45.8 crore, compared with Rs 9.2 crore in Q1 FY27.
- Sapala revenue grew 33.6% year-on-year in Q2 FY27 and 83% in H1 FY27.
powered by IRIS
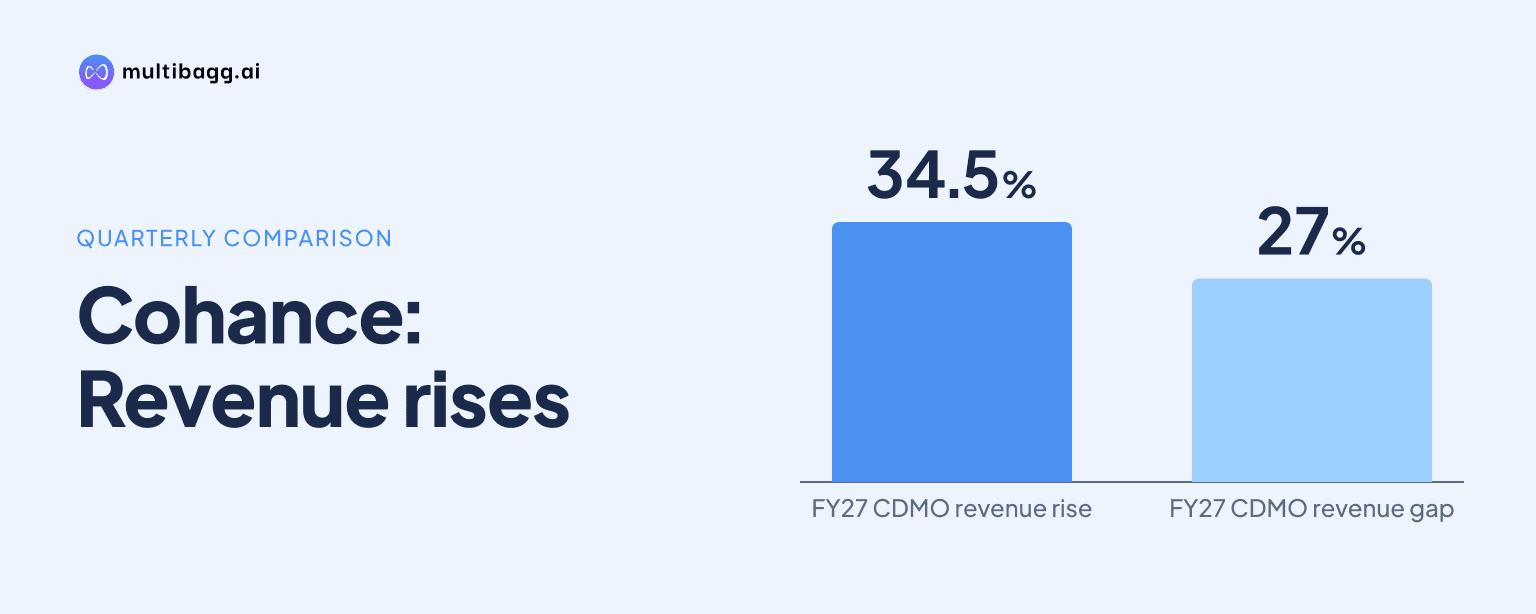
In Q2 FY27, Cohance Lifesciences Limited’s Pharma contract development and manufacturing organisation (CDMO) revenue rose 34.5% sequentially, led by a higher small-molecule contribution, while multiple reload orders and three large global pharmaceutical-customer programs improved visibility for Q3 and Q4. Pharma CDMO revenue nevertheless remained 27% below the prior-year quarter.
Know Cohance Lifesciences inside out
Results, valuation, peers and who's buying, in one view.
Why did Cohance Pharma CDMO recover in Q2 FY27?
Cohance said Pharma CDMO led its Q2 FY27 sequential recovery, with revenue increasing 34.5% quarter-on-quarter primarily because small molecules made a larger contribution. At the group level, Q2 revenue rose 13% sequentially to Rs 476.7 crore, while adjusted earnings before interest, tax, depreciation and amortisation (EBITDA) increased to Rs 45.8 crore from Rs 9.2 crore in Q1 FY27.
Management had described Q1 FY27 as the low point and expected sequential improvement from Q2 before a return to year-on-year growth in H2 FY27. The Q2 adjusted EBITDA margin reached 10%, and adjusted profit after tax returned to positive territory, although Cohance said year-on-year performance remained lower because Pharma CDMO and agrochemical contributions had declined and product mix was unfavourable.
How far is Cohance Pharma CDMO below last year?
Cohance Pharma CDMO remained below the prior year despite the Q2 FY27 improvement, with revenue down 27% year-on-year in Q2 and 32% in H1 FY27. Management attributed the near-term pressure in antibody-drug conjugates (ADCs) to customer inventory destocking across commercial programs during the first half.
Niche technologies contributed 13.7% of Pharma CDMO revenue in Q2 FY27 and 14.4% in H1 FY27, while commercial revenue at Cohance standalone was about 78% of sales. Management also cited an adverse product mix in the quarter, while higher raw-material prices affected select active pharmaceutical ingredient (API) products outside the CDMO recovery.
The contrast between the sequential and annual comparisons reflects the recovery pattern described by management. Small-molecule orders lifted Q2 FY27 from Q1, but the year-on-year comparison still reflected lower Pharma CDMO sales, particularly ADC commercial demand. Cohance said its strengthened forward order position, rather than Q2 performance alone, supported its expectation that momentum would continue through H2 FY27.
What do Cohance’s new large-pharma programs add?
Cohance said it secured three significant programs from large global pharmaceutical customers in Q2 FY27: two commercial programs and one Phase III program. Management said these awards deepen participation with strategic customers and broaden the medium-term opportunity base.
Cohance also received multiple reload orders across existing commercial programs, providing better visibility for Q3 FY27, Q4 FY27 and the following year. Its Phase III program count stood at net 11, while commercial products increased to 19, alongside stronger request-for-proposal activity in late-stage and commercial work.
The reload orders can support existing commercial production, while the two commercial awards and Phase III program add potential future work. Cohance did not disclose program values, customer names or production timing, so the transcript does not quantify the FY27 revenue contribution from the three awards.
Got a follow-up? Ask IRIS
Can Cohance’s ADC and nucleic-acid businesses support recovery?
Cohance said ADC demand remained affected by destocking in two established commercial programs during H1 FY27, but the development funnel and order visibility were improving toward H2. The company reported a broader range of requests for quotations across payloads and linkers, including opportunities that could be developed and manufactured from India.
NJ Bio delivered two ADC good manufacturing practice (GMP) campaigns in Q2 FY27, including one program that moved from early research and development through toxicology studies to GMP manufacturing. It also supported an accelerated 28-day drug-substance-to-drug-product program for another customer, while management said bioconjugation capacity expansion remained on track for commercial availability by early FY2028.
Sapala provided a separate growth point in nucleic acids, with revenue up 33.6% year-on-year in Q2 FY27 and 83% in H1 FY27. Management said Q2 growth did not include early Phase III supplies and was supported by demand for specialised nucleotides, amidites and other building blocks used in newer nucleic-acid technologies.
What does Cohance expect for H2 FY27?
Cohance expects H2 FY27 to deliver year-on-year growth in both revenue and EBITDA, based on stronger small-molecule orders, reloads and improved ADC order visibility. Management described the intended progression as a move from sequential recovery in Q2 FY27 to year-on-year growth in the second half.
That outlook is subject to an unresolved operational matter: Cohance said it was assessing any further impact from the Suryapet closure order. The company also said United States Food and Drug Administration inspections at Pashamylaram, Shamshabad and Jaggayyapeta had concluded, and that it had submitted comprehensive responses while progressing corrective and preventive action (CAPA) measures within committed timelines.
Management said capital investment would be phased against customer visibility, with plans to strengthen bioconjugation, integrate ADC payload-linker capabilities and enhance research and development infrastructure across payload linkers, APIs and specialty chemicals. The stated objective is to address a larger portion of the customer value chain and improve program conversion, with the expanded bioconjugation capacity targeted for commercial availability in early FY2028.
Conclusion
Cohance’s Q2 FY27 results show a sequential Pharma CDMO recovery led by small molecules, with segment revenue rising 34.5% quarter-on-quarter even as it remained 27% below the prior-year quarter. Reload orders, two commercial awards and one Phase III award have improved the order base for Q3 and Q4, while Sapala’s 33.6% year-on-year Q2 growth added momentum in nucleic acids.
The next test is whether H2 FY27 produces the year-on-year revenue and EBITDA growth management expects despite ADC destocking and the still-unassessed impact of the Suryapet closure order. Investors will also watch CAPA implementation following inspections at three facilities and progress towards early-FY2028 commercial availability of expanded bioconjugation capacity.