










Data Patterns Q2 profit falls 55% as gross margin reaches 69%
Key highlights
- Data Patterns’ Q2FY27 revenue was Rs 133.2 crore, down 56.7% year on year but up 14.8% from Q1FY27.
- Data Patterns’ Q2FY27 gross margin reached 69.0%, up 3,052 basis points year on year.
- Data Patterns’ Q2FY27 net profit was Rs 22 crore, down 55.3% from Rs 49.2 crore in Q2FY26.
- Data Patterns recorded Rs 1,046.4 crore of H1FY27 order inflow and a reported closing order book of Rs 1,723.6 crore.
powered by IRIS
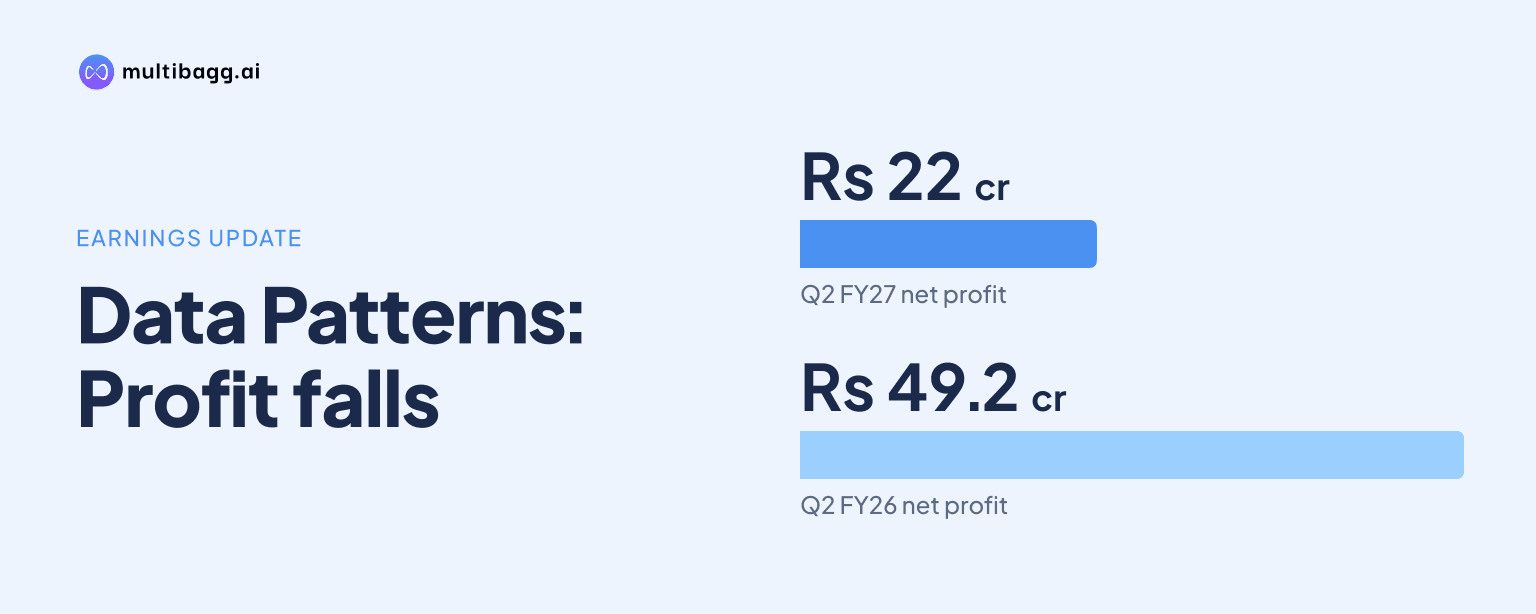
Data Patterns reported Q2FY27 net profit of Rs 22 crore, down 55.3% year on year, as revenue fell 56.7% to Rs 133.2 crore while gross margin rose 3,052 basis points to 69.0%. Gross profit declined 22.3% to Rs 92 crore, a smaller fall than revenue because total raw-material cost dropped 78.2%.
Know Data Patterns (India) inside out
Results, valuation, peers and who's buying, in one view.
Why did Data Patterns’ Q2FY27 revenue and profit decline?
Data Patterns’ Q2FY27 revenue and profit declined against a quarter that management described as having exceptionally strong execution in Q2FY26. Net revenue fell to Rs 133.2 crore from Rs 307.5 crore a year earlier, while net profit declined to Rs 22 crore from Rs 49.2 crore. Revenue was nevertheless 14.8% above the Rs 116 crore reported in Q1FY27.
The first-half comparison also remained lower. H1FY27 revenue was Rs 249.3 crore, down 38.7% from Rs 406.8 crore in H1FY26, and net profit was Rs 44 crore, down 41.1% from Rs 74.7 crore. Reported earnings per share were Rs 3.9 in Q2FY27 compared with Rs 8.8 in Q2FY26, while H1FY27 earnings per share were Rs 7.9 against Rs 13.3.
Earnings before interest, tax, depreciation and amortisation (EBITDA) fell to Rs 31.4 crore in Q2FY27 from Rs 68.5 crore, a 54.1% decline. Earnings before interest and tax fell 61.2% to Rs 24.4 crore after depreciation rose 24.8% to Rs 7.1 crore. Profit before tax was Rs 29.5 crore, down 55.5%, while tax expense declined 56.0% to Rs 7.6 crore.
How did Data Patterns lift gross margin to 69%?
Data Patterns lifted Q2FY27 gross margin to 69.0% from 38.5% in Q2FY26 as total raw-material cost fell faster than revenue. Total raw-material cost was Rs 41.3 crore, down 78.2% from Rs 189 crore, and represented 31.0% of sales versus 61.5% a year earlier. The 30.52-percentage-point reduction in raw-material cost as a share of sales matched the 30.52-percentage-point increase in gross margin.
The gross-margin result was lower sequentially: gross margin was 78.9% in Q1FY27, making Q2FY27 lower by 983 basis points. Cost of materials consumed rose 88.0% quarter on quarter to Rs 57.8 crore, while changes in inventories, work in progress and semi-finished products were negative Rs 16.5 crore, compared with negative Rs 6.2 crore in Q1FY27. These movements produced total raw-material cost of Rs 41.3 crore, up 68.3% sequentially.
The higher gross margin did not produce a similarly large expansion in operating margin because staff and other expenses represented greater shares of revenue. Employee-benefit expense increased 16.3% year on year to Rs 44 crore and equalled 33.1% of Q2 sales, compared with 12.3% in Q2FY26. Other expenses rose 36.8% to Rs 16.5 crore, or 12.4% of sales, leaving EBITDA margin at 23.6%, up 132 basis points from 22.3%.
Got a follow-up? Ask IRIS
What was Data Patterns’ Q2FY27 revenue mix?
Data Patterns’ Q2FY27 revenue mix comprised 58% development work, 34% production and 9% service on revenue of Rs 133.2 crore. In Q2FY26, development accounted for 64%, production for 33% and service for 4%. The year-on-year change was therefore a six-percentage-point lower development share, a one-percentage-point higher production share and a five-percentage-point higher service share.
The contrast with Q1FY27 was larger. Production contributed 61% of Q1FY27 revenue, development 30% and service 9%, compared with 34%, 58% and 9%, respectively, in Q2FY27. For H1FY27, production represented 46% of revenue, development 45% and service 9%; H1FY26 had a 43%, 51% and 6% mix.
By product, electronic warfare accounted for 52.0% of Q2FY27 revenue and radar for 19.1%, together representing 71.1% of the quarter’s Rs 133.2 crore revenue. Avionics contributed 18.2% and annual maintenance contracts contributed 7.4%. The Ministry of Defence accounted for 51.0% of Q2 revenue, Bharat Electronics Limited for 20.0%, Defence Research and Development Organisation for 9.0% and exports for 8.8%.
What does Data Patterns expect after the first half?
Data Patterns expects H2FY27 to be stronger than H1FY27 as programme milestones progress and deliveries pick up, according to its Chairman and Managing Director. The company reported Rs 929.1 crore of Q2FY27 order inflow and Rs 1,046.4 crore in H1FY27, compared with Rs 350.6 crore in H1FY26. Q2FY27 inflow was 475% above the Rs 167.1 crore reported in Q2FY26.
The reported H1FY27 closing order book was Rs 1,723.6 crore, built from the FY26 order book of Rs 926.5 crore, H1FY27 inflow of Rs 1,046.4 crore and Rs 249.3 crore of order execution in the half. Management separately cited an approximately Rs 2,698 crore current order book including orders received and negotiated, making that measure broader than the reported H1 closing order book. Production represented 43% of the H1 closing book, development 36% and services 21%.
Management said it expects Rs 2,000 crore of FY2027 order inflow other than orders already received and negotiated, while FY27 guidance remains unchanged. Data Patterns acquired a 100% stake in ST Advanced Composites Pvt. Ltd. for Rs 10 crore after board approval in Q1FY27. The presentation says the added composite-manufacturing capability could support gradual gross-margin improvement, production planning and bids for larger integrated radar and defence-system contracts.
Conclusion
Data Patterns’ Q2FY27 results combined a 56.7% revenue contraction and a 55.3% net-profit decline with a substantial shift in gross margin. Gross profit fell 22.3% to Rs 92 crore because total raw-material cost declined 78.2% to Rs 41.3 crore, but higher staff and other-expense ratios limited EBITDA-margin expansion to 23.6% from 22.3%.
What to watch next is management’s plan for stronger H2FY27 execution and deliveries, its unchanged FY27 guidance, and the stated target for Rs 2,000 crore of additional FY2027 orders beyond those received and negotiated. The conversion of the Rs 1,723.6 crore reported H1 order book, alongside the broader Rs 2,698 crore current order book cited by management, remains the disclosed execution measure for the remainder of FY27.