










Dhoot Transmission H1 EBITDA margin falls 290 basis points
Key highlights
- Dhoot Transmission’s detailed H1 FY27 revenue from operations rose 55.7% to Rs 3,273.6 crore.
- Dhoot Transmission’s detailed H1 EBITDA margin declined to 14.7% from 17.6%, a 290-basis-point reduction.
- Dhoot Transmission’s material costs increased 66.3% to Rs 2,233.9 crore in H1 FY27.
- Multilink generated Rs 188.5 crore of H1 FY27 revenue at a 10.4% EBITDA margin.
powered by IRIS
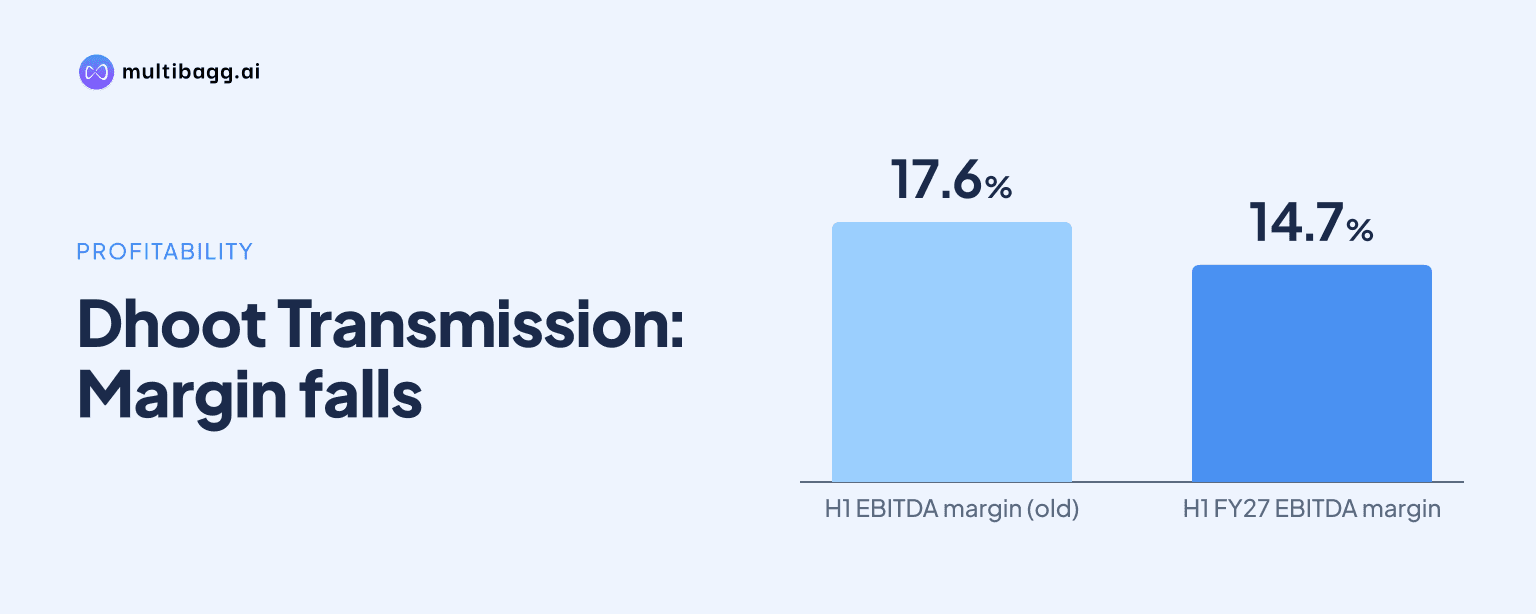
Dhoot Transmission Limited’s detailed first-half (H1) FY27 statement shows earnings before interest, tax, depreciation and amortisation (EBITDA) margin fell 290 basis points to 14.7% from 17.6%, even as revenue from operations rose 55.7% to Rs 3,273.6 crore. The presentation attributes the contraction to input, manpower and acquisition-mix pressures.
Know Dhoot Transmission inside out
Results, valuation, peers and who's buying, in one view.
Why did Dhoot Transmission’s H1 EBITDA margin fall?
Dhoot Transmission’s H1 FY27 EBITDA margin fell because material costs increased faster than revenue, while manpower costs and the acquired Multilink business also affected the mix. Revenue from operations increased 55.7% year on year to Rs 3,273.6 crore, but total material cost rose 66.3% to Rs 2,233.9 crore. Employee benefits expense increased 36.7% to Rs 246.9 crore, while other expenses rose 49.9% to Rs 312.5 crore.
The presentation attributes about 120 basis points of the H1 movement to higher copper costs and 130 basis points to higher direct and indirect manpower costs, including employee stock-option plan, or ESOP, costs. It also identifies higher polyvinyl chloride, or PVC, and electronics costs, without quantifying their combined effect. One basis point is one-hundredth of a percentage point, so 290 basis points equals 2.9 percentage points.
The presentation’s H1 financial summary reports EBITDA of Rs 479 crore and a 14.6% margin, while its detailed profit-and-loss statement reports Rs 480.2 crore and a 14.7% margin. The detailed statement puts H1 FY26 EBITDA at Rs 371 crore and its margin at 17.6%, showing EBITDA increased 29.4% despite the 290-basis-point margin reduction.
How fast did Dhoot Transmission’s revenue grow in H1 FY27?
Dhoot Transmission reported H1 FY27 revenue growth of 56%, with battery and electronics growing faster than wiring harnesses. Its financial summary lists revenue of Rs 3,272.4 crore, compared with Rs 2,103.1 crore in H1 FY26, while the detailed statement reports Rs 3,273.6 crore of revenue from operations. The presentation says growth excluding Multilink was about 47%, compared with about 20% industry retail growth.
Wiring harness revenue increased 43% in H1 FY27 and battery and electronics revenue increased 98%. Electric-vehicle revenue represented 31% of second-quarter (Q2) FY27 revenue, compared with 24% in FY26. Dhoot Transmission’s current portfolio includes low-voltage, high-voltage and battery harnesses, 48-volt traction packs, charging guns, connectors, terminals and junction boxes.
Q2 revenue from operations was Rs 1,827.2 crore, up 60.7% from Rs 1,136.8 crore in Q2 FY26 and 26.5% from Rs 1,446.4 crore in Q1 FY27. However, Q2 EBITDA margin was 14.3%, below 15.1% in Q1 FY27 and 17.6% in Q2 FY26, indicating that the H1 cost pressure continued in the latest quarter.
What was Multilink’s effect on Dhoot Transmission’s margin?
Multilink reduced Dhoot Transmission’s consolidated H1 margin because its 10.4% EBITDA margin was below the 14.9% reported for the business excluding Multilink. Multilink contributed Rs 188.5 crore of H1 revenue and Rs 19.7 crore of EBITDA. The presentation estimates that Multilink reduced the reported H1 margin by about 30 basis points.
Excluding Multilink, Dhoot Transmission recorded H1 revenue of Rs 3,085.1 crore, up 47% year on year, and EBITDA of Rs 460.6 crore, up 25%. Its resulting margin was 14.9%, compared with 17.5% in H1 FY26. This comparison shows that the bulk of the margin decline remained in the pre-acquisition business, alongside the copper, PVC, electronics and manpower costs identified in the presentation.
In Q2 FY27, Multilink generated Rs 161.5 crore of revenue and Rs 16.8 crore of EBITDA, again producing a 10.4% margin. The business excluding Multilink generated Rs 1,665.6 crore of Q2 revenue, up 47% year on year, with a 14.7% EBITDA margin versus 17.5% a year earlier. The presentation estimates Multilink’s Q2 impact at about 38 basis points.
Got a follow-up? Ask IRIS
What happened to Dhoot Transmission’s profit after tax?
Dhoot Transmission’s adjusted profit after tax (PAT) rose 33.4% to Rs 296.4 crore in H1 FY27 in the detailed statement, while adjusted PAT margin declined to 9.1% from 10.6%. EBITDA grew 29.4% to Rs 480.2 crore, but depreciation and amortisation increased 58.4% to Rs 90.1 crore. The presentation attributes adjusted PAT growth trailing the EBITDA increase to the higher depreciation and amortisation expense.
Reported PAT increased 16.8% to Rs 250.5 crore in H1 FY27 after exceptional items of Rs 57.8 crore, compared with Rs 10.3 crore in H1 FY26. Dhoot Transmission says these items include Rs 48 crore of management fees, a Rs 4.3 crore investment write-off and Rs 9.7 crore of initial public offering expenses charged to the profit-and-loss statement. Its H1 financial summary separately lists adjusted PAT of Rs 235.1 crore and an 11.2% prior-year margin, whereas the detailed statement lists Rs 222.3 crore and 10.6%.
Q2 reported PAT was Rs 117.8 crore, marginally below Rs 118.2 crore in Q2 FY26, despite EBITDA increasing 30.5% to Rs 261.8 crore. Adjusted Q2 PAT rose 30.4% to Rs 161.5 crore, and its margin was 8.8%, down from 10.9% a year earlier.
Did Dhoot Transmission’s cash flow keep pace with earnings?
Dhoot Transmission’s H1 FY27 operating cash flow was Rs 40.2 crore, below its Rs 388.6 crore profit before tax because trade working capital absorbed Rs 283 crore. Trade working capital increased to Rs 1,096.4 crore in September 2026 from Rs 870 crore in March 2026, while trade working-capital days rose to 61 from 55.
Capital expenditure of Rs 292.9 crore resulted in negative free cash flow of Rs 252.6 crore in H1 FY27. Dhoot Transmission also spent Rs 421.2 crore on the Multilink acquisition, while initial public offering proceeds of Rs 1,400 crore were received. The presentation states that these cash-flow movements are derived from balance-sheet changes rather than a statutory cash-flow statement.
Cash and bank balances were Rs 1,127.5 crore at September 2026, compared with Rs 1,095.8 crore in March 2026. Borrowings declined to Rs 223.8 crore from Rs 841.4 crore, and net cash excluding leases was Rs 903.7 crore, versus Rs 254.4 crore at March 2026. These balance-sheet changes occurred alongside higher working-capital and capital-expenditure requirements.
Conclusion
Dhoot Transmission paired H1 FY27 revenue growth of 55.7% with a 290-basis-point EBITDA-margin decline, as material costs grew 66.3% and Multilink operated at a 10.4% margin. Excluding Multilink, the H1 margin was still 14.9%, down from 17.5%, indicating that input and manpower costs were the larger contributors to the reduction.
The next reported periods will show whether copper, PVC, electronics and ESOP-related costs continue to affect the margin and how Multilink changes the consolidated mix. Dhoot Transmission also identifies pipeline products including off-board chargers, DC-DC converters, battery-management systems and high-voltage harnesses, but the presentation provides no financial targets or programme milestones for these opportunities.