










Digitide keeps 200-basis-point margin target after Q2 FY27
Key highlights
- Digitide's Q2 FY27 EBITDA margin rose 45 basis points sequentially to 10.4%, while revenue fell 2% to about Rs 760 crore.
- Digitide maintained its FY27 commitment to improve EBITDA margin by 200 basis points.
- Digitide reduced headcount from about 53,000 in Q1 FY27 to nearly 50,000 in Q2 FY27, while revenue per staff rose almost 12%.
- Digitide's AI-led revenue doubled sequentially to Rs 30.5 crore in Q2 FY27 and TCV bookings rose 95% to almost Rs 400 crore.
powered by IRIS
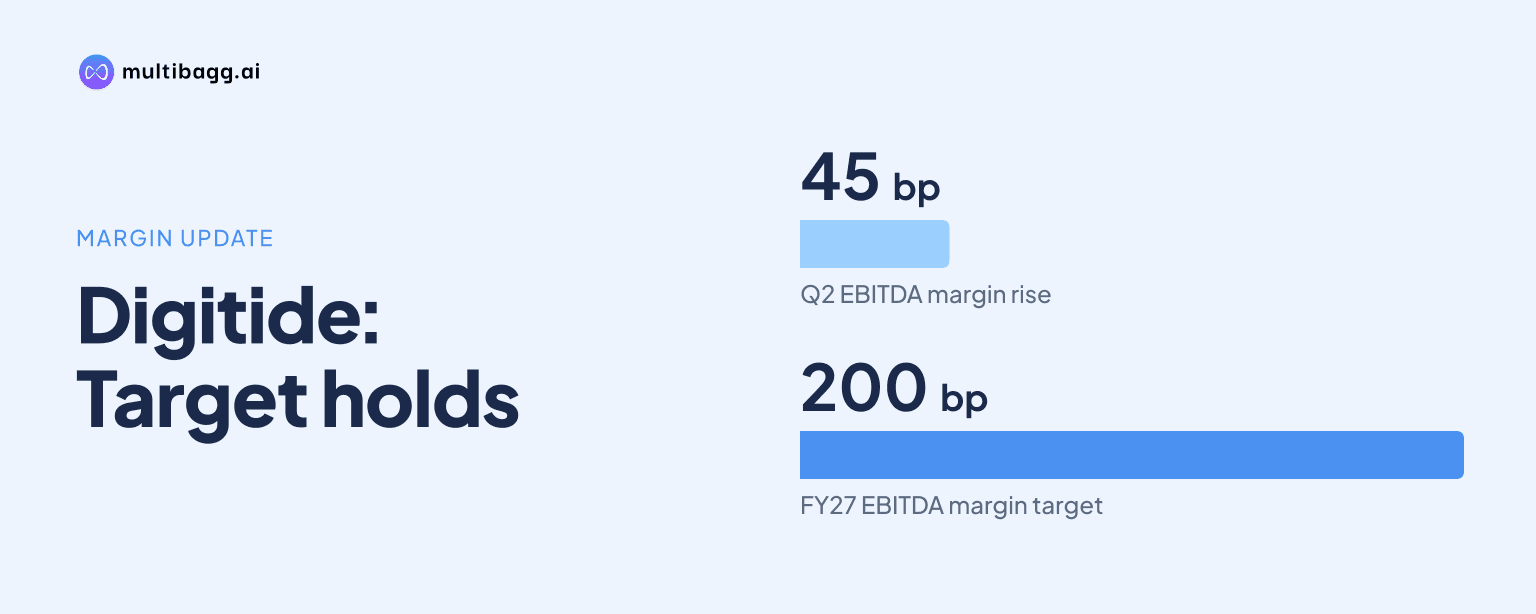
Digitide Solutions Limited maintained its FY27 target of a 200-basis-point improvement in EBITDA margin after Q2 FY27 margin rose 45 basis points sequentially to 10.4%, despite revenue falling 2% to about Rs 760 crore. Management linked the trade-off to contract repricing, exits from low-return work and cost restructuring.
Know Digitide Solutions inside out
Results, valuation, peers and who's buying, in one view.
Is Digitide still committed to its FY27 margin target?
Yes, Digitide remains committed to improving its FY27 EBITDA margin by 200 basis points. Management reiterated the target after earnings before interest, tax, depreciation and amortisation, or EBITDA, rose 2.5% sequentially to about Rs 79 crore in Q2 FY27, even though consolidated revenue declined to about Rs 760 crore.
The reported margin improvement came with a sharp increase in profit after tax, or PAT. Reported PAT increased from Rs 2.9 crore in Q1 FY27 to Rs 8.9 crore in Q2 FY27, and management said there were no exceptional items in the second quarter. It did not provide a revised revenue, EBITDA or PAT range for FY27.
The margin gains were not uniform across businesses. Tech and digital margin expanded 315 basis points from 8.0% to 11.1% in Q2 FY27, while business process management, or BPM, margin declined slightly to 13.6%. Digitide said its response would centre on account-level profitability, cost discipline and a shift in revenue mix.
Why did Digitide's revenue decline in Q2 FY27?
Digitide's revenue declined because management chose not to retain work that failed its return thresholds. The group reported about Rs 760 crore of Q2 FY27 revenue, down 2% sequentially, while saying it was renegotiating contracts and leaving businesses that did not meet its economic criteria.
The contract action is focused particularly on the core BPM business. Digitide said it was repricing contracts, exiting or restructuring low-return work, and applying artificial intelligence, or AI, to BPM services to improve productivity, differentiation and margins. Management said the quantum of contract renegotiation and repricing in Q2 FY27 was 2.5 times the level reported in Q1 FY27, without disclosing a contract value.
The portfolio reset also reduced the workforce from about 53,000 people in Q1 FY27 to nearly 50,000 in Q2 FY27. That represented a reduction of almost 7% sequentially and almost 11.6% year on year. Management said revenue per staff increased by almost 12%, indicating that revenue had risen relative to employee numbers during the period.
Management said it was not satisfied with the profitability of the rest of the portfolio when asked about operations excluding Alldigi. It described lower costs, contract repricing, exits or restructuring of low-return work, and a greater focus on tech and digital and international activity as the turnaround mechanisms. Management also said the transformation could take a couple of quarters to produce the outcomes it sought.
Got a follow-up? Ask IRIS
Which businesses are supporting Digitide's mix shift?
Digitide's tech and digital and international businesses grew faster than the group in Q2 FY27. Tech and digital revenue increased 6.6% year on year to Rs 244 crore, accounting for 32.1% of revenue, while international revenue rose 13.5% to Rs 323 crore, representing 42.5% of revenue.
Sales activity accelerated as total contract value, or TCV, booked increased 95% sequentially from Rs 205 crore in Q1 FY27 to almost Rs 400 crore in Q2 FY27. Digitide attributed the increase to dedicated go-to-market structures for its India++ and International corridors, supported by service-line teams handling capabilities, solutions and partnership alliances.
AI-led revenue doubled sequentially from Rs 15 crore in Q1 FY27 to Rs 30.5 crore in Q2 FY27. Digitide said its AI work spans AI-infused BPM, AI-enabled platforms and AI professional services, with applications in insurance, banking and healthcare, including collections, healthcare revenue-cycle management and insurance customer operations.
Digitide also reported six new live implementations in data, AI and cloud between Q1 and Q2 FY27. During Q2, it formed strategic alliances with AWS and Anthropic and signed a sizable build-operate-transfer, or BOT, mandate to be delivered from its Philippines office. Management did not quantify expected revenue from these alliances or the BOT mandate.
What are Digitide's cost and cash priorities for H2 FY27?
Digitide plans to continue right-sizing its cost structure and portfolio in H2 FY27. Management said the effect of certain cost decisions would become visible in the second half, alongside high-impact cost optimisation, pricing actions and tighter account-level profitability management intended to support margins.
Cash conversion is also a stated H2 FY27 priority because billed plus unbilled days sales outstanding, or DSO, increased to about 84 days in Q2 FY27 from 82 days in Q1 FY27. In H1 FY27, operating cash flow increased 27.5% year on year from Rs 40 crore to Rs 51 crore, while consolidated revenue rose 2.3% year on year to Rs 1,535 crore.
Digitide closed Q2 FY27 with net cash of about Rs 76 crore. Management said Alldigi's proposed buyback was sized at Rs 48 crore and Digitide owned about 73.39% of Alldigi, although its eventual receipt would depend on other shareholders' participation. The chief financial officer said proceeds would predominantly reduce standalone debt, with excess cash retained on the balance sheet.
Conclusion
Digitide's Q2 FY27 figures show the immediate effect of its profitability-first approach: revenue declined 2% sequentially to about Rs 760 crore, while EBITDA rose 2.5% to about Rs 79 crore and margin improved 45 basis points to 10.4%. Growth in tech and digital, international revenue, TCV bookings and AI-led revenue provides the operating support for management's planned mix shift.
The next test is H2 FY27 execution against management's 200-basis-point full-year margin-improvement target. Management plans further contract repricing, portfolio exits, cost actions and collection discipline, while seeking better DSO than the 84 days reported in Q2 FY27. It also expects some cost-structure effects to become visible in H2 FY27.