










Ellenbarrie Q2 revenue rises 28% as EBITDA margin falls
Key highlights
- Ellenbarrie reported Q2FY27 revenue from operations of Rs 114.3 crore, up 28% year on year and 16% sequentially.
- Ellenbarrie’s Q2FY27 EBITDA was Rs 40.7 crore, up 21% year on year, while EBITDA margin declined to 36% from 39% in Q1FY27.
- Ellenbarrie’s gases division generated Rs 112.1 crore in Q2FY27, up 27% year on year, with a 39% segment-result margin.
- Ellenbarrie won a Rs 480.7 crore Bharat Heavy Electricals Limited order in September 2026 for a 1,200-tonnes-per-day cryogenic air separation unit.
powered by IRIS
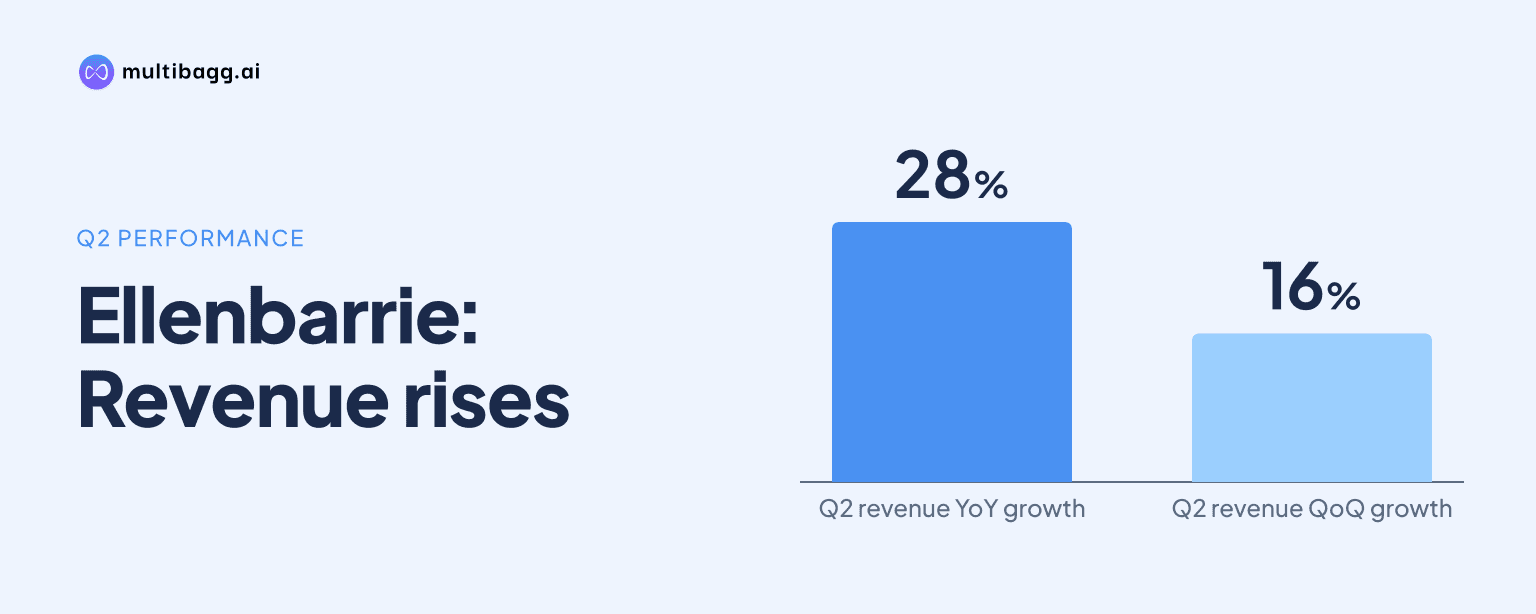
Ellenbarrie Industrial Gases Ltd reported Q2FY27 revenue from operations of Rs 114.3 crore, up 28% year on year, as new plants ramped up volumes, while its earnings before interest, tax, depreciation and amortisation (EBITDA) margin fell to 36% from 39% in Q1FY27 because of higher transport costs and salary-hike arrears.
Know Ellenbarrie Industrial Gases inside out
Results, valuation, peers and who's buying, in one view.
Why did Ellenbarrie’s Q2FY27 revenue rise 28%?
Ellenbarrie’s Q2FY27 revenue rose 28% year on year to Rs 114.3 crore because higher volumes from newly commissioned and ramping plants lifted gases sales. Revenue from operations was also 16% above Rs 98.7 crore in Q1FY27 and Rs 25.1 crore higher than the Rs 89.2 crore reported in Q2FY26.
The gases, related products and services division generated Rs 112.1 crore of revenue in Q2FY27, compared with Rs 97.4 crore in Q1FY27 and Rs 87.9 crore in Q2FY26. Ellenbarrie attributed the division’s 15% sequential and 27% year-on-year growth to higher volumes as merchant plants continued to ramp up.
Bulk supply delivered the largest absolute increase among customer categories. Bulk revenue reached Rs 82 crore in Q2FY27, up from Rs 69.4 crore in Q1FY27 and Rs 63.1 crore in Q2FY26, while package revenue rose to Rs 15.4 crore from Rs 13.6 crore sequentially. Onsite revenue was Rs 13.9 crore, marginally below Rs 14 crore in Q1FY27.
What caused Ellenbarrie’s EBITDA margin to decline?
Ellenbarrie’s EBITDA margin declined to 36% in Q2FY27 as power expenses, transport costs and salary-hike arrears increased faster than operating profit. EBITDA rose 21% year on year to Rs 40.7 crore and 5% sequentially from Rs 38.7 crore, but revenue increased 16% from Q1FY27.
The 36% margin was below 38% in Q2FY26 and 39% in Q1FY27. Gross margin also decreased to 66% in Q2FY27 from 70% a year earlier and 67% sequentially, indicating that cost pressure was evident before employee and other operating expenses.
Power expense increased 40% year on year to Rs 25.7 crore in Q2FY27 and 17% from Rs 22 crore in Q1FY27. Employee costs rose 32% year on year to Rs 8.6 crore, while other expenses rose 17% to Rs 25.9 crore and 29% sequentially. Management said it was negotiating price increases to offset higher transport costs over the next couple of quarters.
How did Ellenbarrie’s gases division perform in Q2FY27?
Ellenbarrie’s gases division reported Rs 112.1 crore of Q2FY27 revenue and a 39% segment-result margin, supported by merchant-plant ramp-up, capacity utilisation and some improvement in realisations. Segment result represents segment revenue less directly attributable expenses and is not the same measure as company-wide EBITDA.
The division’s 39% segment-result margin improved from 38% in Q1FY27 despite higher power costs, but remained below 41% in Q2FY26. Ellenbarrie stated that the year-on-year decline was 248 basis points, with one basis point equal to one-hundredth of a percentage point.
Oxygen represented 49% of Q2FY27 gases revenue, compared with 50% in Q1FY27, while nitrogen’s share declined to 35% from 40%. Argon and mixtures increased to 16% from 10%, and sale of gases accounted for 98% of revenue, compared with 99% in each of the prior comparison quarters. Steel was the largest industry exposure at 34%, followed by pharmaceuticals and chemicals at 23% and the dealer and retail network at 18%.
Got a follow-up? Ask IRIS
Why did Ellenbarrie’s profit after tax fall year on year?
Ellenbarrie’s profit after tax fell 3% year on year to Rs 35.6 crore in Q2FY27 because Q2FY26 included a Rs 4.5 crore deferred-tax credit. The result was nevertheless 2% above the Rs 35 crore reported in Q1FY27, while profit before tax increased 20% year on year to Rs 47.9 crore.
Tax expense was Rs 12.3 crore in Q2FY27, compared with Rs 3.2 crore in Q2FY26 and Rs 11.5 crore in Q1FY27. The profit-after-tax margin therefore declined to 27% from 36% a year earlier and 30% sequentially, reflecting both the lower EBITDA margin and the prior-year tax-credit comparison.
Depreciation increased to Rs 6.9 crore in Q2FY27 from Rs 5.1 crore in Q2FY26, while finance costs rose to Rs 2.5 crore from Rs 1.1 crore. Impairment loss on financial assets was Rs 0.5 crore in Q2FY27, compared with Rs 0.2 crore a year earlier, although profit before tax remained above Rs 46.5 crore in Q1FY27.
What could affect Ellenbarrie’s next quarters?
Ellenbarrie expects the East India onsite plant commissioned in Q2FY27 to generate full revenue in Q3FY27, while Kurnool and Uluberia 2 merchant plants are expected to be key FY27 growth drivers. Management said the two merchant plants were continuing to ramp up and that improving capacity utilisation would remain a focus through FY27.
Management expects momentum to strengthen in H2FY27 as recently commissioned plants ramp further. Ellenbarrie also said new merchant plants in North India and West/Central India are planned for FY28, alongside capital-expenditure guidance of Rs 250 crore for FY27 and Rs 200 crore for FY28.
In September 2026, Ellenbarrie won a Rs 480.7 crore order from Bharat Heavy Electricals Limited to supply and erect a 1,200-tonnes-per-day cryogenic air separation unit on a turnkey basis. The unit is part of a coal-to-ammonium-nitrate project at Jharsuguda, Odisha, but the presentation does not disclose an execution timeline or revenue-recognition schedule.
Conclusion
Ellenbarrie’s Q2FY27 results combined 28% revenue growth with lower consolidated profitability margins. Revenue increased by Rs 25.1 crore year on year, led by bulk supply and merchant-plant volumes, while EBITDA rose by Rs 7 crore; however, higher power, transport and employee costs reduced EBITDA margin to 36%, and the absence of a Rs 4.5 crore deferred-tax credit lowered profit after tax year on year.
The next reported markers are full revenue from the East India onsite plant in Q3FY27, utilisation gains at Kurnool and Uluberia 2 through FY27, and management’s expected transport-cost price increases over the next couple of quarters. Progress against the Rs 250 crore FY27 capital-expenditure plan, FY28 merchant-plant additions and the September 2026 Rs 480.7 crore Bharat Heavy Electricals Limited order will also be relevant.