










Emerald Tyres targets premium mix and export-led margins
Key highlights
- Emerald Tyres reported a 75% export and 25% domestic revenue mix in HY FY27.
- Management is targeting 80% to 82% solid-tyre capacity utilisation in H2 FY27.
- Management cited solid-tyre gross margin of about 25%, versus 10% to 11% for pneumatic tyres.
- Emerald Tyres indicated 25% to 30% top-line growth and cited turnover of Rs 260 crore.
powered by IRIS
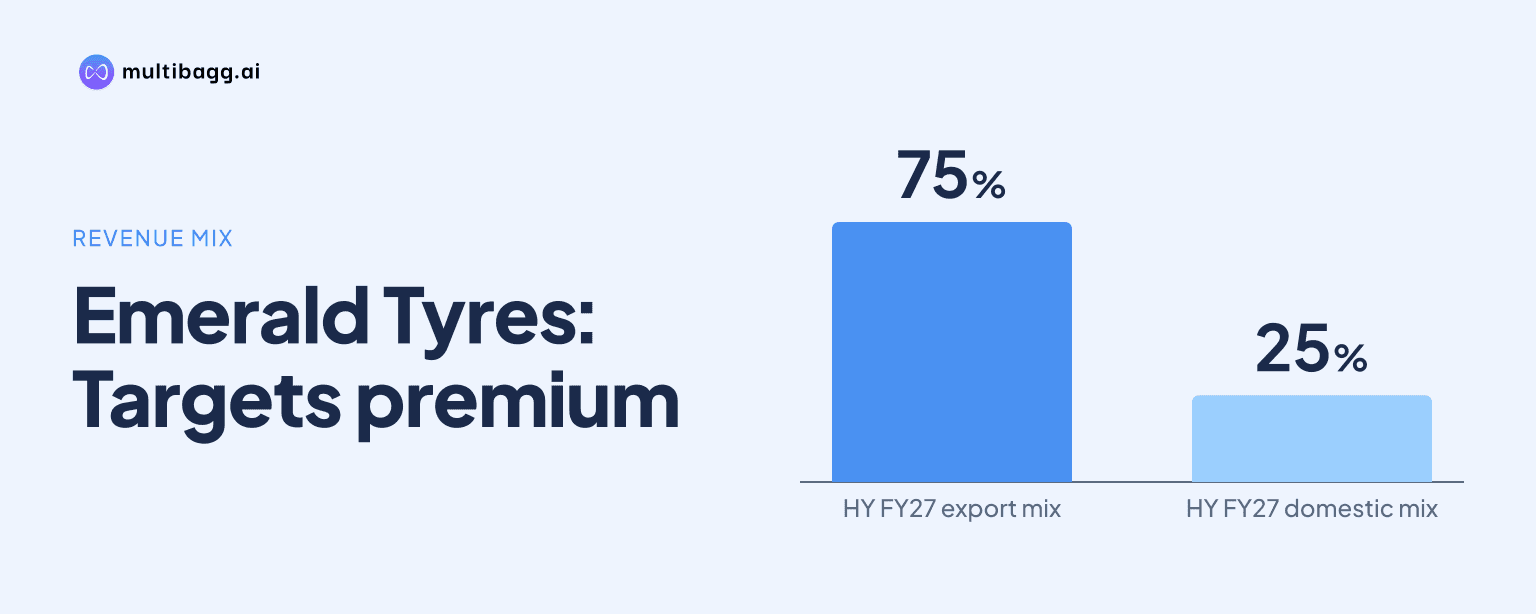
Emerald Tyre Manufacturers Limited is targeting 80% to 82% solid-tyre capacity utilisation in H2 FY27 through premium AXIMO tyres, multi-piece rims and higher-value export products. Emerald Tyres said the strategy should improve product mix after premium orders were delayed, while its HY FY27 revenue mix was 75% exports and 25% domestic sales.
Know Emerald Tyre Manufacturers inside out
Results, valuation, peers and who's buying, in one view.
Why is Emerald Tyres changing its product mix?
Emerald Tyres is putting greater emphasis on premium solid tyres because management said solid tyres currently contribute better profitability than pneumatic tyres. Domestic sales are 95% solid tyres and 5% pneumatic tyres, while exports are split 50% solid and 50% pneumatic, making the domestic portfolio more weighted to the product category management prefers.
The shift follows a sharper decline in pneumatic-tyre economics. Management said pneumatic tyres normally deliver gross margins of about 25%, but this had fallen to roughly 10% to 11% after nylon-fabric costs rose almost 45%. Solid-tyre gross margin had also declined from about 35% to 38% to 25%, but remained above the pneumatic-tyre level cited on the call.
Management said pneumatic and solid tyres had contributed almost equally in the prior year. Emerald Tyres is therefore not proposing to exit standard or budget products, but is seeking more value addition through premium products, which management said can improve market reputation and margins.
Which export markets is Emerald Tyres prioritising?
Emerald Tyres is prioritising Australia, South Africa, Germany and the United States for selected higher-end tyre products. Management said Australia has no tyre manufacturer and is dependent on imports, adding that the company’s products had moved well after a trade show held about six months earlier.
South Africa is another target because management said that market values quality and can generate a better margin for the same product. In Germany and the United States, Emerald Tyres is focusing on telehandler tyres, scissor-lift tyres and high-end ground support equipment, or GSE, tyres during H2 FY27 and into the following year.
Exports represented 75% of HY FY27 revenue, compared with 25% from the domestic market. That mix means the planned improvement depends substantially on overseas orders, particularly after management said Middle East orders had been cancelled, European customers had adopted a wait-and-watch stance and US tariff uncertainty had affected buying decisions.
Management said some original equipment manufacturer, or OEM, projects had been held up while equipment makers delayed production and exports. These projects included products under testing, approved products and approvals still pending, which management identified as potential volume sources if customer orders resume.
How do AXIMO tyres and multi-piece rims support the strategy?
Emerald Tyres is using AXIMO premium solid tyres to increase domestic sales to high-use fleet operators. Management said customers operating forklifts 24 hours a day are choosing premium tyres to reduce their operating costs, and that domestic AXIMO volumes had recently increased among such users.
Management said premium solid-tyre demand in India was currently better than in international markets. That domestic trend is important because solid tyres account for 95% of the company’s domestic portfolio, compared with 50% of its export portfolio, where pneumatic tyres have a larger presence.
The company is also moving from two-piece rims to multi-piece rims, which management described as the higher-end wheel category. Management said multi-piece rims had received substantial acceptance from domestic OEMs that had previously imported the products, creating a separate premium offering alongside AXIMO tyres.
Premium-order delays limited the first-half contribution from these products. Management said customers held back high-value orders after the AXIMO expansion, while budget-tyre demand was also resistant; the company completed premium business where it could in India while overseas customers delayed or cancelled orders.
Got a follow-up? Ask IRIS
What capacity and revenue outcomes does Emerald Tyres expect?
Emerald Tyres expects a larger-tyre project with a major OEM to lift solid-tyre capacity utilisation to about 80% to 82% in H2 FY27. Management said the project was put on hold because of US tariffs, but described a resolution as increasingly likely, which could allow the project to raise utilisation.
Management said the combined effect of higher solid-tyre utilisation and premium pricing should support turnover. When asked about the second half, management described 25% to 30% growth in top line, not volume, and separately said turnover could reach Rs 260 crore.
No unit-volume forecast was provided when the analyst asked about volume growth. The capacity target also relies partly on the large OEM project proceeding, so the 80% to 82% utilisation level remains a management expectation rather than a reported operating result.
What does the strategy imply for Emerald Tyres margins?
Emerald Tyres is seeking about 15% earnings before interest, tax, depreciation and amortisation, or EBITDA, in FY27 after the first-half impact. Management said its longer-term target is 17% to 18% EBITDA if industry conditions improve and pricing returns to the levels it anticipates.
Management linked potential margin improvement to premium tyre penetration, solid-tyre utilisation and lower raw-material prices. It said the company had implemented a 13% price increase against a 35% weighted-average rise in costs, then made two further price revisions in the second half while seeking to preserve prices.
The strategy also has a cash-flow objective. Management reported trade receivables of 113 days, down from 120 days on March 31, 2026, while inventory stood at 113 days versus 116 days at the year-end; it attributed the inventory position and slower warehouse movement partly to shipping delays.
Conclusion
Emerald Tyres is reshaping its growth approach around premium solid tyres, AXIMO demand, multi-piece rims and markets where management sees scope for higher-value sales. The 75% export share of HY FY27 revenue raises the importance of recovering overseas orders, while the domestic business gives the company a portfolio that is already 95% solid tyres.
Next, investors should watch whether the larger OEM tyre project moves ahead and supports the 80% to 82% H2 FY27 solid-tyre utilisation target. Other disclosed markers are premium-order recovery, OEM approvals, demand in Australia, South Africa, Germany and the United States, raw-material prices and progress toward management’s 15% FY27 EBITDA objective.