










Emmforce targets 20%-22% margin from December revisions
Key highlights
- Emmforce reported a standalone EBITDA margin of about 19.5% in H1 FY27, below its 20%-22% normal range.
- Emmforce plans customer price revisions from 1 December 2026 after ocean-freight costs almost doubled.
- Standalone revenue rose 71% year on year to about Rs 84 crore in H1 FY27.
- Receivables increased to Rs 63 crore in September from Rs 34 crore in March, with about Rs 40 crore linked to the US customer.
powered by IRIS
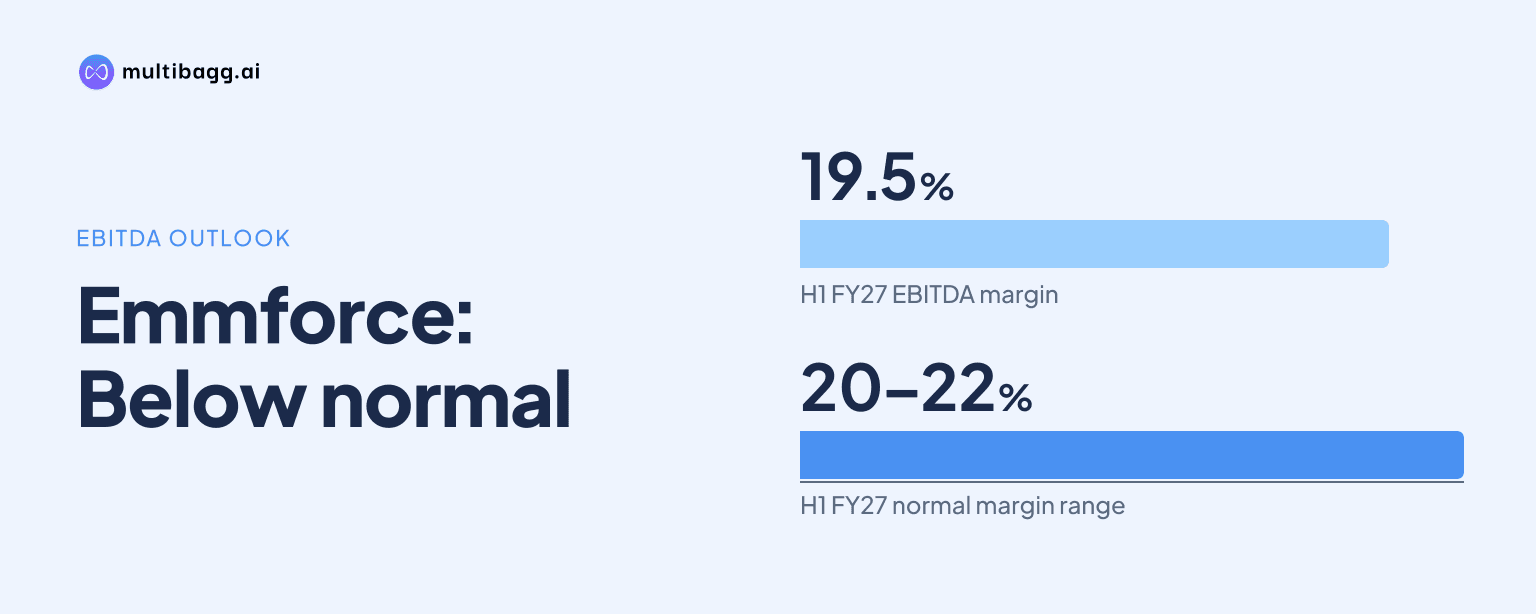
Emmforce Autotech Limited targets a return to its 20%-22% standalone earnings before interest, tax, depreciation and amortisation (EBITDA) margin range after about 19.5% in H1 FY27, as management plans customer price revisions from 1 December and expects easing US freight rates to lower costs absorbed during the first half.
Know Emmforce Autotech inside out
Results, valuation, peers and who's buying, in one view.
Why did Emmforce's standalone EBITDA margin fall in H1 FY27?
Emmforce's standalone EBITDA margin fell to about 19.5% in H1 FY27 because it absorbed higher steel, consumables, power, gas and ocean-freight costs instead of immediately passing them to customers. Management said the margin was modestly below its normal 20%-22% range after disruption associated with the West Asia conflict lasted longer than expected.
Ocean freight was a significant part of the pressure, with management saying the cost almost doubled during the period. The company said cost escalation affected both original equipment manufacturer, or OEM, business and aftermarket sales, rather than only its newer US programme. Dollar appreciation provided some benefit, but management said it did not offset rising material and logistics costs.
The margin movement occurred alongside higher core-business revenue. Standalone revenue was about Rs 84 crore in H1 FY27, up 71% year on year, while standalone EBITDA was about Rs 16 crore and profit after tax, or PAT, was about Rs 9 crore. Management said standalone PAT was close to 11% of sales.
When will Emmforce's price revisions take effect?
Emmforce plans to seek customer price revisions effective from 1 December 2026, although management had not written to any customer at the time of its 16 November earnings call. The proposed timing is therefore a management plan, not a completed price increase.
Management expects some customers to implement revisions from 1 December and others by around 15 December, while acknowledging that larger customers could take longer. For OEM customers, Emmforce said it would discuss increases through contractual indexing formulas covering input-cost changes. Management did not disclose the size of the increase it intends to seek.
Lower freight costs are the second mechanism behind the planned H2 FY27 margin recovery. Management said US freight rates had started to decline and could return close to normal levels within one to two months. It expects the combination of reduced freight expense and customer revisions to make the recovery trajectory visible during H2 FY27.
Emmforce initially treated the cost increase as temporary and did not want to disturb customers over a disruption it expected to last no more than six months. Management said the US programme began customer lifting around July, and the company chose to wait until buyers had used its parts before beginning pricing discussions.
Got a follow-up? Ask IRIS
What could still affect Emmforce's H2 FY27 profitability?
Emmforce's consolidated profitability will remain affected by Emmforce Mobility, which recorded a Rs 2.8 crore loss on revenue of Rs 14.5 crore in H1 FY27. External sales accounted for Rs 8.6 crore of that revenue, with the balance arising from group business, and management said the subsidiary would reduce consolidated margins in FY27.
Management attributed lower-than-planned Emmforce Mobility sales to two months of labour unrest at TAFE, its main agricultural customer, and to TAFE first consuming blade inventory from prior suppliers. Emmforce consequently lowered Emmforce Mobility's FY27 revenue expectation to about Rs 20 crore from Rs 30 crore and reduced consolidated FY27 revenue guidance to Rs 185 crore from Rs 195 crore.
Management expects Emmforce Mobility to have no cash loss in H2 FY27, supported by forging activity. The subsidiary has launched EMMFarm rotavators in Maharashtra, plans to enter South India and Madhya Pradesh, and is selling rotavator blades through distributors. These initiatives have no quantified H2 revenue target in the call transcript.
At the parent level, Emmforce retained standalone FY27 revenue guidance of Rs 165 crore and expects standalone PAT of about Rs 18 crore. It expects consolidated PAT of about Rs 14 crore. Management described the standalone PAT forecast as conservative because customers may draw down inventory built for the US programme before ordering reaches a steadier pattern.
How are US sales affecting Emmforce's cash flow?
Emmforce's Rs 470 crore US programme is running at full speed and is expected to deliver about Rs 60 crore of FY27 revenue, according to management. OEM business rose to 41% of revenue in H1 FY27 from 7% in FY26. A separate US OEM order worth about Rs 10.5 crore annually has production part approval process, or PPAP, samples with the customer and is expected to begin production in the next quarter.
The US programme also lengthened the cash cycle. Receivables increased to Rs 63 crore in September from Rs 34 crore in March, contributing to negative operating cash flow of Rs 5.9 crore in H1 FY27. Management said about Rs 40 crore of September receivables related to the US customer.
Management described the US cash cycle as about six months, comprising six to eight weeks of inventory in a US warehouse, roughly two months in transit and a two-month payment cycle. It expects receivables to decline to about Rs 50 crore by the end of FY27 as the initial stock build moderates.
Capital expenditure fell to Rs 3 crore in H1 FY27 from Rs 18 crore a year earlier. Emmforce said it has installed capacity of about Rs 350 crore and expects most near-term growth to come from better utilisation of existing assets rather than broad-based new capital expenditure.
Conclusion
Emmforce's margin-recovery plan depends on two linked actions: passing through a portion of higher input costs and benefiting from lower US freight rates. H1 FY27 showed that revenue expansion did not prevent margin pressure, with standalone EBITDA margin at about 19.5% and consolidated EBITDA margin at 17% as Emmforce Mobility recorded a Rs 2.8 crore loss.
The next disclosures to watch are progress against Rs 185 crore consolidated FY27 revenue guidance, the move toward the 20%-22% standalone margin range and receivables moving from Rs 63 crore toward management's roughly Rs 50 crore year-end expectation. Management also plans to announce the proposed Emmforce Automotives merger details only after board approval, independent valuation and approvals from shareholders, the stock exchange and the National Company Law Tribunal.