










Emmforce revenue reaches Rs 113 crore as FY26 returns fall
Key highlights
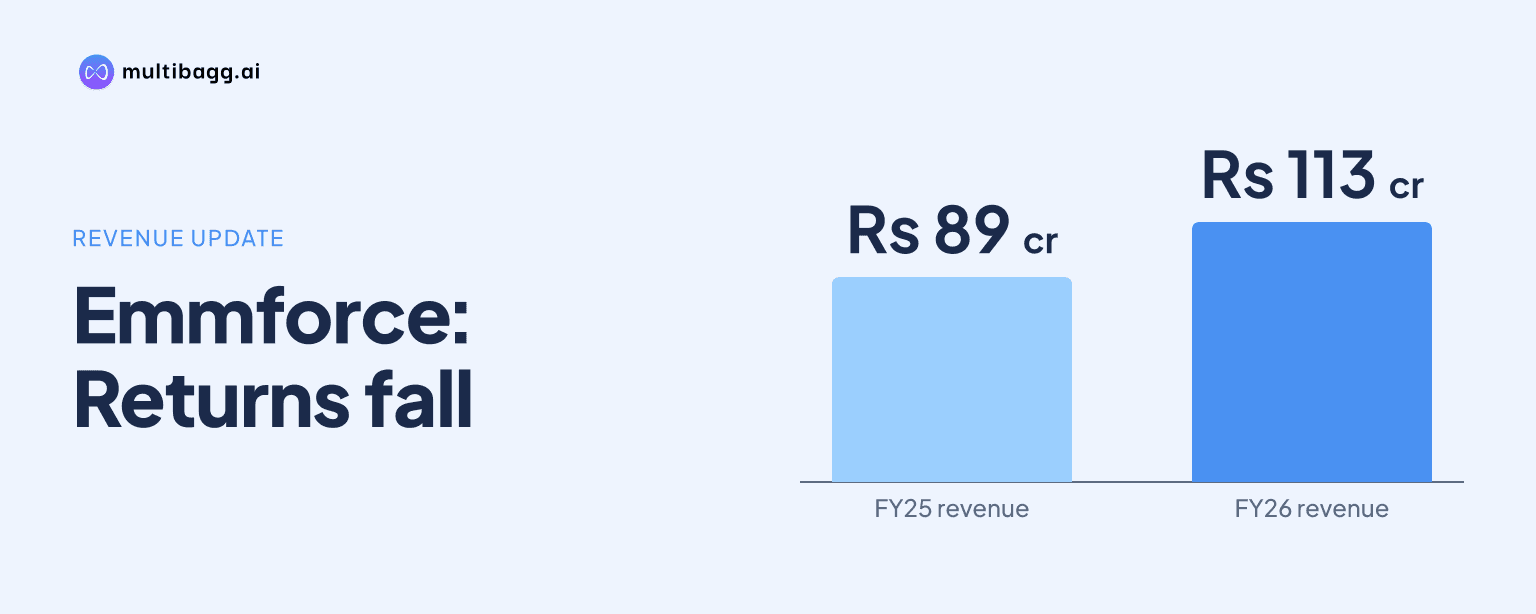
- Emmforce reported FY26 consolidated revenue of Rs 113 crore, compared with Rs 89 crore in FY25.
- FY26 EBITDA rose to Rs 23 crore, while PAT remained Rs 8 crore and PAT margin fell to 7%.
- FY26 ROCE declined to 13% from 14% in FY25 as management cited agri-division capacity-expansion capex.
- Emmforce’s FY26 cash-conversion cycle increased to 144 days and net debt to EBITDA rose to 1.92 times.
powered by IRIS
Emmforce Autotech reported consolidated FY26 revenue of Rs 113 crore, but return on capital employed (ROCE) fell to 13% and net profit stayed at Rs 8 crore. Management linked the lower return profile to agri-division capacity-expansion capital expenditure, while strategic hiring, depreciation and a 144-day cash-conversion cycle also weighed on earnings conversion.
Know Emmforce Autotech inside out
Results, valuation, peers and who's buying, in one view.
Why did Emmforce FY26 revenue reach Rs 113 crore?
Emmforce reached consolidated FY26 revenue of Rs 113 crore, up from Rs 89 crore in FY25, while earnings before interest, tax, depreciation and amortisation (EBITDA) increased to Rs 23 crore from Rs 18 crore. The financial-highlights presentation reports a 35% compound annual growth rate in revenue and 27% in EBITDA between FY23 and FY26.
The revenue increase did not produce a comparable rise in profit after tax (PAT). PAT was Rs 8 crore in FY26, compared with Rs 8 crore in FY25, which the presentation describes as a 2% increase despite revenue rising by Rs 24 crore. Management attributed the limited PAT movement mainly to manpower hiring for projects already secured and depreciation on fixed assets at EMSPL.
Emmforce’s full-year consolidated profit-and-loss statement presents a separate revenue-from-operations series of Rs 46 crore in FY23, Rs 83 crore in FY24 and Rs 88 crore in FY25, before reaching the same Rs 113 crore in FY26. The presentation says FY24 figures in that statement are pro forma and include Emmforce Autotech from October 2023 to March 2024 after conversion from a partnership firm.
How did Emmforce FY26 profit margins change?
Emmforce’s FY26 EBITDA margin declined to 20% from 21% in FY25, while PAT margin decreased to 7% from 9%. Depreciation doubled to Rs 8 crore from Rs 4 crore, reducing earnings before interest and tax (EBIT) margin to 13% from 16%, even though EBITDA rose by Rs 5 crore.
Below EBITDA, EBIT increased only to Rs 15 crore in FY26 from Rs 14 crore in FY25, while profit before tax was unchanged at Rs 12 crore. Finance cost increased to Rs 3 crore from Rs 2 crore and tax expense remained Rs 4 crore, resulting in FY26 net profit of Rs 8 crore for the second consecutive year.
Gross margin moved in the other direction, rising to 45% in FY26 from 41% in FY25. That left a 25-percentage-point gap between gross margin and EBITDA margin in FY26, versus 20 percentage points a year earlier, alongside the hiring and depreciation factors identified by management.
Why did Emmforce ROCE decline to 13% in FY26?
Emmforce’s ROCE declined to 13% in FY26 from 14% in FY25 and 33% in FY24 because of significant capacity-expansion capital expenditure for its agri division, according to the presentation. Management expects returns to improve as utilisation ramps up and revenue scales, but it does not give a timing assumption or numerical ROCE target.
The balance sheet records the investment behind that explanation. Property, plant and equipment increased to Rs 74 crore in FY26 from Rs 37 crore in FY25, while capital work in progress moved from Rs 22 crore to zero. Total non-current assets rose to Rs 80 crore from Rs 61 crore, compared with FY26 EBITDA of Rs 23 crore.
Return on equity declined to 9% in FY26 from 10% in FY25 and 44% in FY24. Total equity increased to Rs 91 crore from Rs 80 crore during FY26, while reserves and surplus rose to Rs 71 crore from Rs 59 crore, whereas PAT remained Rs 8 crore.
Got a follow-up? Ask IRIS
How did Emmforce working capital and debt change in FY26?
Emmforce’s cash-conversion cycle extended to 144 days in FY26 from 136 days in FY25 and 68 days in FY24. The presentation attributes the FY26 extension primarily to new US business beginning in March 2026, with inventory days increasing to 72 from 54 despite receivable days declining to 109 from 116.
Inventories increased to Rs 22 crore in FY26 from Rs 13 crore in FY25, and trade receivables rose to Rs 34 crore from Rs 28 crore. By H1 FY27, inventories had reached Rs 26 crore and trade receivables Rs 63 crore, while total current assets increased to Rs 106 crore from Rs 75 crore at FY26.
Net debt to EBITDA increased to 1.92 times in FY26 from 1.38 times in FY25, although it was below the 2.44 times reported in FY24. Long-term borrowings declined to Rs 20 crore from Rs 21 crore, but short-term borrowings increased to Rs 24 crore from Rs 14 crore and reached Rs 37 crore in H1 FY27.
What do Emmforce H1 FY27 results show?
Emmforce reported consolidated H1 FY27 revenue from operations of Rs 92 crore, up 73% from Rs 54 crore in H1 FY26, and net profit of Rs 6 crore, up 54% from Rs 4 crore. EBITDA rose 44% to Rs 16 crore, but EBITDA margin fell to 17% from 21% and net profit margin declined to 7% from 8%.
The standalone figures show revenue of Rs 84 crore in H1 FY27, up 71% from Rs 49 crore in H1 FY26, while net profit increased 40% to Rs 9 crore from Rs 6 crore. Standalone EBITDA margin was 19%, compared with 22% a year earlier, and standalone net profit margin was 11%, compared with 13%.
Management projects automotive-segment revenue of Rs 165 crore in FY27 and Rs 195 crore in FY28, following Rs 105 crore in FY26. It projects EMSPL revenue of Rs 30 crore in FY27 and Rs 50 crore in FY28, after Rs 8 crore in FY26, while noting that EMSPL sales to Emmforce Autotech are eliminated on consolidation.
Management has set a standalone EBITDA-margin target of 20% to 22% and a PAT-margin target of about 10%. It has also said consolidated margins will be lower in FY27 while the subsidiary ramps up, and it targets original equipment manufacturer revenue contribution of about 40% by FY27.
Conclusion
Emmforce’s FY26 results show that revenue and EBITDA growth occurred alongside greater capital and working-capital demands. Revenue rose to Rs 113 crore and EBITDA to Rs 23 crore, but agri capacity investment, depreciation rising to Rs 8 crore, hiring and a 144-day cash-conversion cycle coincided with ROCE of 13%, a 7% PAT margin and PAT of Rs 8 crore.
The next results will indicate whether H1 FY27 consolidated revenue of Rs 92 crore and EBITDA of Rs 16 crore support management’s FY27 automotive revenue projection of Rs 165 crore. Key disclosed markers are EMSPL’s planned Rs 30 crore FY27 revenue, the subsidiary’s effect on consolidated margins, and changes in inventory, receivables and short-term borrowings, which stood at Rs 26 crore, Rs 63 crore and Rs 37 crore respectively in H1 FY27.